Utilities are back in favor, and Vistra’s latest move is helping explain why: investors are treating the sector less like a sleepy bond proxy and more like a direct play on surging electricity demand, especially from data centers, electrification and grid investment.
Vistra Pullback Keeps Utilities in Focus
That matters because utilities are increasingly being valued on their ability to grow, not just defend income. When a company like Vistra can stay at the center of the power market conversation, it reinforces the idea that this is a sector with real earnings momentum — not just a place to hide when markets wobble. With the S&P 500 flashing extreme greed in Adalytica.com’s trade signals, money has clearly not abandoned risk. But some of it is rotating toward businesses with visible cash flows and long runways.
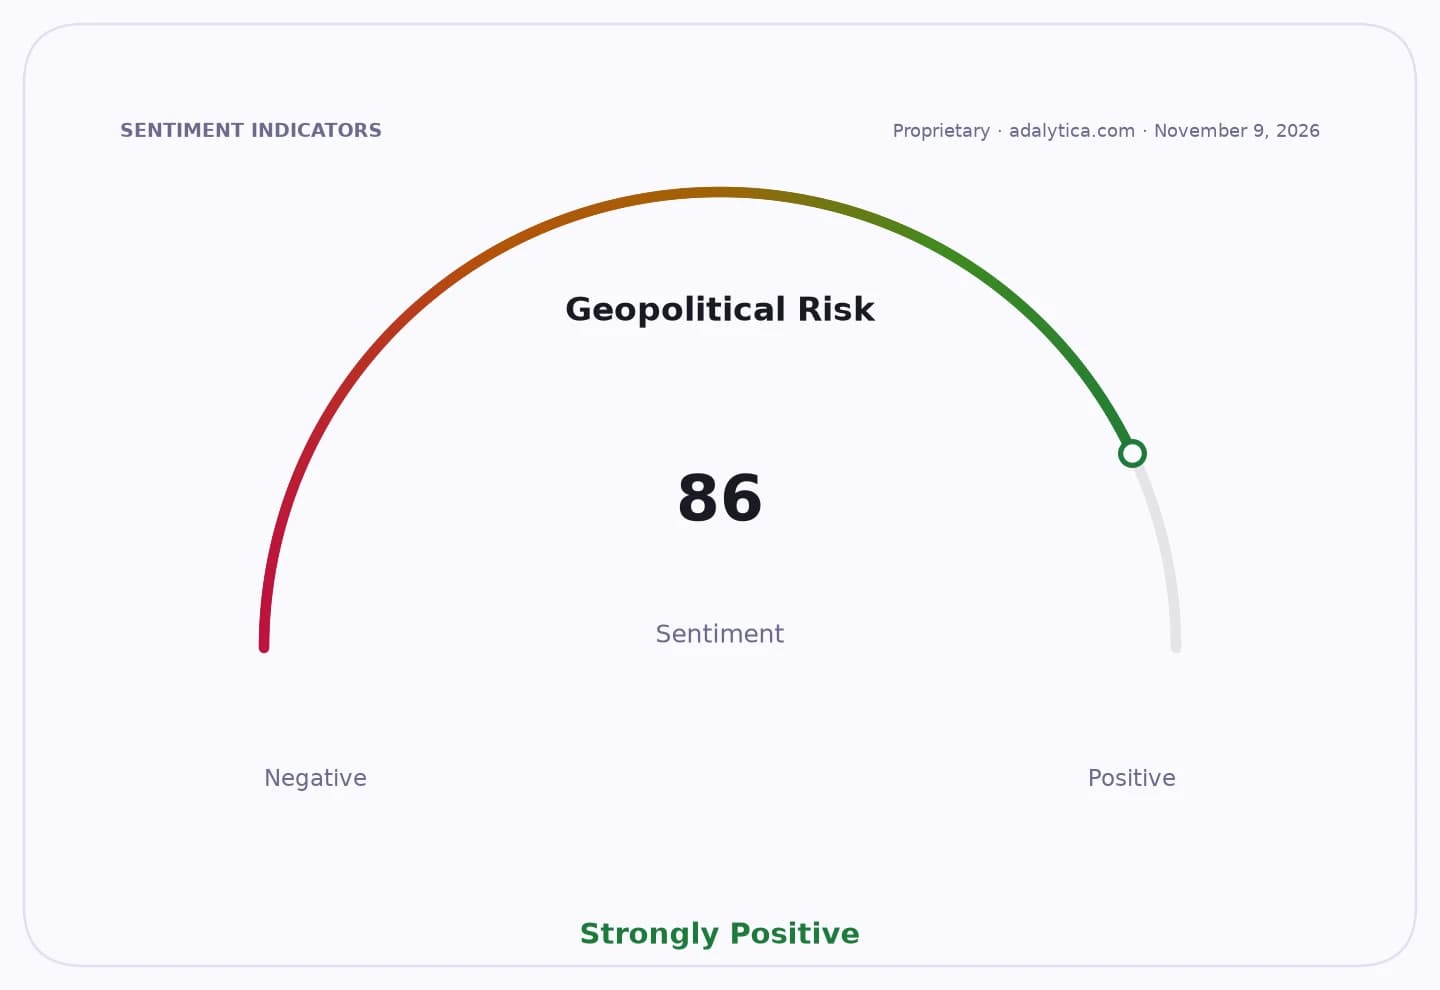
Sentiment Indicators
Vistra’s own trading action underscores that point. After a sharp selloff earlier in the month, the shares have stabilized around $134, well below the recent peak above $179 but also far off the low near $113. The stock is still trading under its 200-day moving average, while the 50-day average sits above the current price, a reminder that the chart has not fully repaired. Still, the rebound from the recent break lower suggests buyers are willing to look through short-term volatility if the long-term power story stays intact.
That broader thesis is helping the whole utilities group. NextEra Energy has held up near the mid-$80s, Duke Energy is pressing against the high end of its recent range near $129, and the group is benefiting from the same long-duration appeal: regulated assets, rising capital spending and the possibility that power demand stays stronger for longer than many investors once assumed.
S&P 500 vs VSTadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.
The economic logic is straightforward. Electricity is becoming a more scarce, strategic input as AI infrastructure, manufacturing reshoring and transportation electrification all lift load growth. Utilities that can build generation, expand transmission and earn regulated returns should have more places to invest capital — and more opportunities to compound value over years, not quarters. That is exactly why management teams keep emphasizing investment plans even when profits only inch higher.
There are risks, of course. Higher rates can pressure utility valuations, weather can still swing results, and capital spending only works if regulators allow a fair return. But for long-term investors, that is the tradeoff: slower headline growth in exchange for durable earnings, rising dividends and a clearer path to reinvestment than many mature sectors can offer.
If Vistra’s pullback has taught anything, it is that even the best utility stories will not move in a straight line. But the bigger message for investors is more encouraging: this sector is no longer just about safety. It is about owning the infrastructure behind a power-hungry economy, and that is a theme worth watching — and, for patient investors, worth holding.
| Entity | Gains | Losses |
|---|---|---|
| Vistra | ▲Power-demand narrative | ▼Short-term momentum traders |
| NextEra Energy | ▲Defensive growth appeal | ▼Cyclical value chasers |
| Duke Energy | ▲Regulated earnings visibility | ▼Investors seeking fast gains |
| Power users/data centers | ▲More supply investment | ▼Utilities facing capacity strain |