Wall Street rose broadly on Thursday, with the Dow Jones Industrial Average posting its best day in a month after a Federal Reserve governor signaled rates could stay unchanged if incoming inflation data do not surprise to the upside.
Wall Street Rises as Treasury Yields Ease
The move mattered because it eased one of the market’s most immediate drags: the jump in Treasury yields that had unsettled equities, especially interest-rate sensitive sectors and high-multiple technology stocks. The 10-year Treasury yield fell back to around 4.76% after earlier touching its highest level since November 2023, helping lift the Dow 1.18% to 53,686.11, the S&P 500 1.06% to 7,747.71 and the Nasdaq Composite 1.40% to 26,584.06. The VIX dropped 5.92% to 14.30, underscoring a sharper bid for risk.
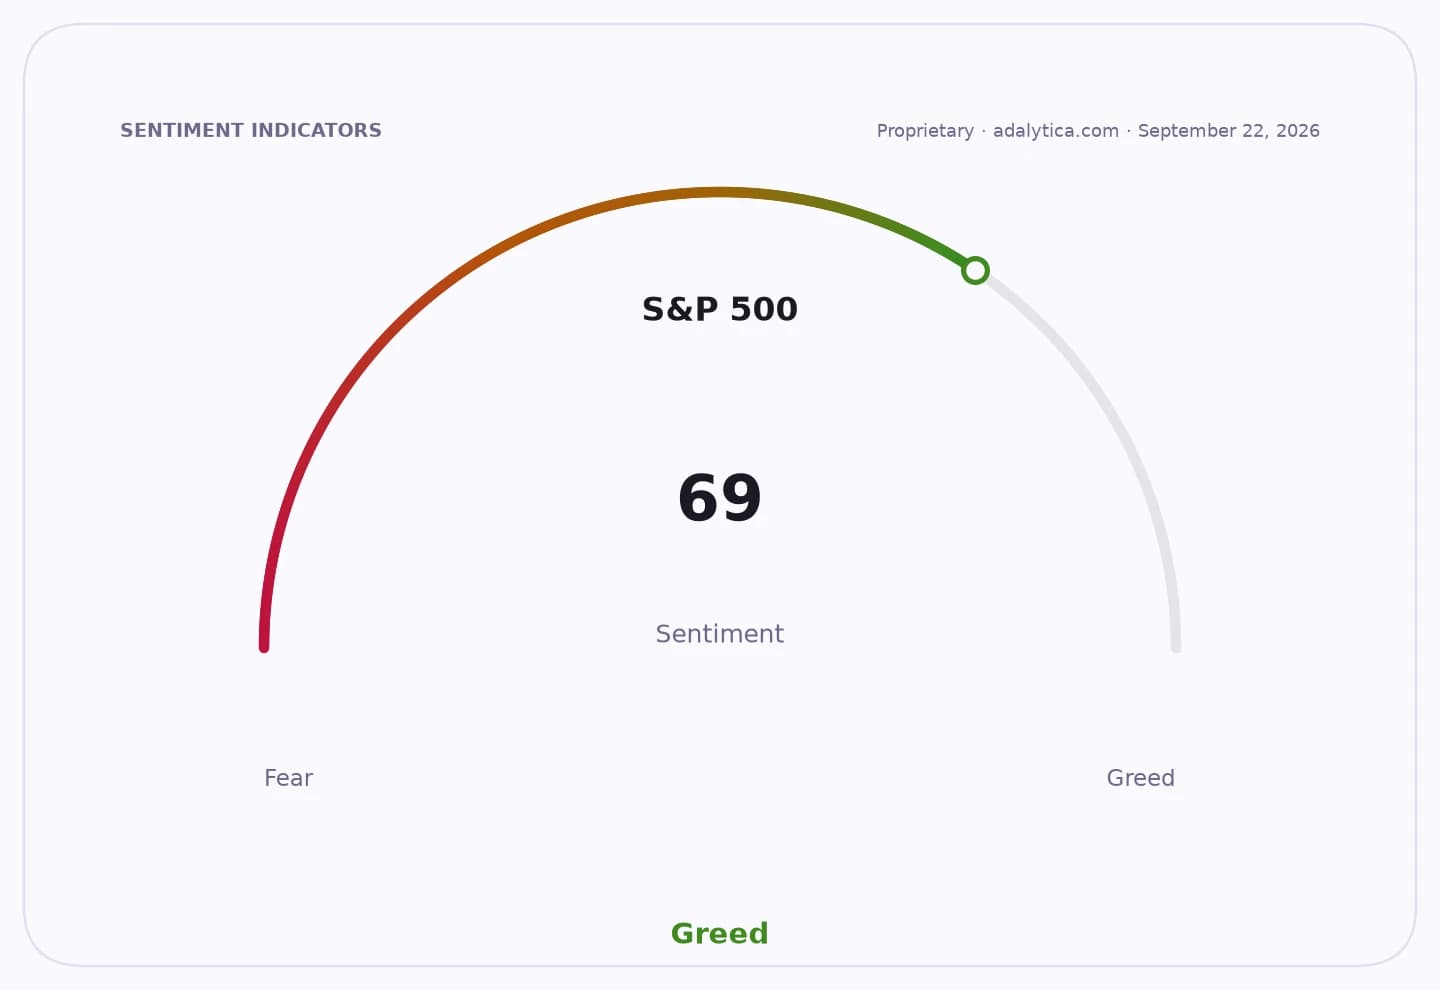
Sentiment IndicatorsⓘProprietary · adalytica.com · September 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The trigger was Christopher Waller’s comment that he was “inclined to support” keeping policy steady unless inflation data deliver a surprise. That mattered to investors because Treasury yields had been climbing on concern that higher energy prices would feed inflation and force the Fed to tighten further. Fed funds futures still imply markets expect the central bank to raise rates within weeks, so Thursday’s equity rebound looks more like relief than a decisive change in regime.
The bond-market reaction also reflected the day’s macro mix. Stronger-than-expected U.S. services data helped offset some recession anxiety but did little to calm inflation worries, with the ISM services index rising to 56.5 and the final S&P Global services and composite PMIs both holding above expectations. At the same time, crude remained elevated, with WTI near $91.72 a barrel and Brent at $95.78, keeping pressure on the inflation outlook and limiting confidence that the rate backdrop is improving in a durable way.
Rate-sensitive sectors and growth stocks benefited most from the repricing. Meta Platforms rose 3% after a new AI model launch, Dell Technologies gained 5% for a second straight session after strong results and a higher fiscal 2027 outlook, and Snowflake jumped more than 20% on better-than-expected quarterly profit and revenue plus solid guidance. Those gains helped offset weaker shares in Tyson Foods, which fell almost 7% after cutting full-year forecasts because of beef-market pressure, and Broadcom, which slipped 2% after a downbeat revenue outlook.
The day’s market tone also reflected the policy crosscurrents in Washington. Vice President J.D. Vance said the Fed should cut rates to improve housing affordability, adding political pressure on the central bank just days after Trump ally Kevin Warsh suggested the opposite approach may be needed to contain inflation. For investors, that leaves the market caught between conflicting signals: a softer rate path would support valuations, but persistent inflation and firm energy prices could keep yields elevated and make every rally fragile.
For now, Thursday looked like a classic relief rally driven by a drop in yields and a moderation in rate fears. The next catalyst is clear: inflation data and oil prices will determine whether Wall Street’s recovery has room to extend or whether Thursday was just a pause in a more volatile adjustment to higher-for-longer borrowing costs.
| Entity | Gains | Losses |
|---|---|---|
| Equities, especially Dow names | ▲Lower yields, relief buying | ▼Higher-for-longer rates |
| Fed doves / rate-cut bets | ▲Softer policy expectations | ▼Inflation hawks |
| Growth tech stocks | ▲Multiple support from easing yields | ▼Bond-market pressure |
| Oil producers | ▲Firm crude prices | ▼Consumers and rate-sensitive sectors |