China’s consumer spirits names steadied after a November 6 business-policy meeting in which senior officials signaled continued support for industrial and regional enterprises, with market attention centering on whether looser policy conditions can finally stabilize demand across discretionary sectors.
Wuliangye Yibin Rises on China Policy Support
For investors in liquor maker Wuliangye Yibin, which trades as 000568.SZ, the meeting matters less for its headline content than for what it suggests about Beijing’s current stance: policymakers are still trying to prevent a broader slowdown in private-sector activity from spilling further into consumption, manufacturing and local employment. That is significant for a premium spirits producer whose earnings are closely tied to China’s domestic spending cycle, business banqueting and consumer confidence.
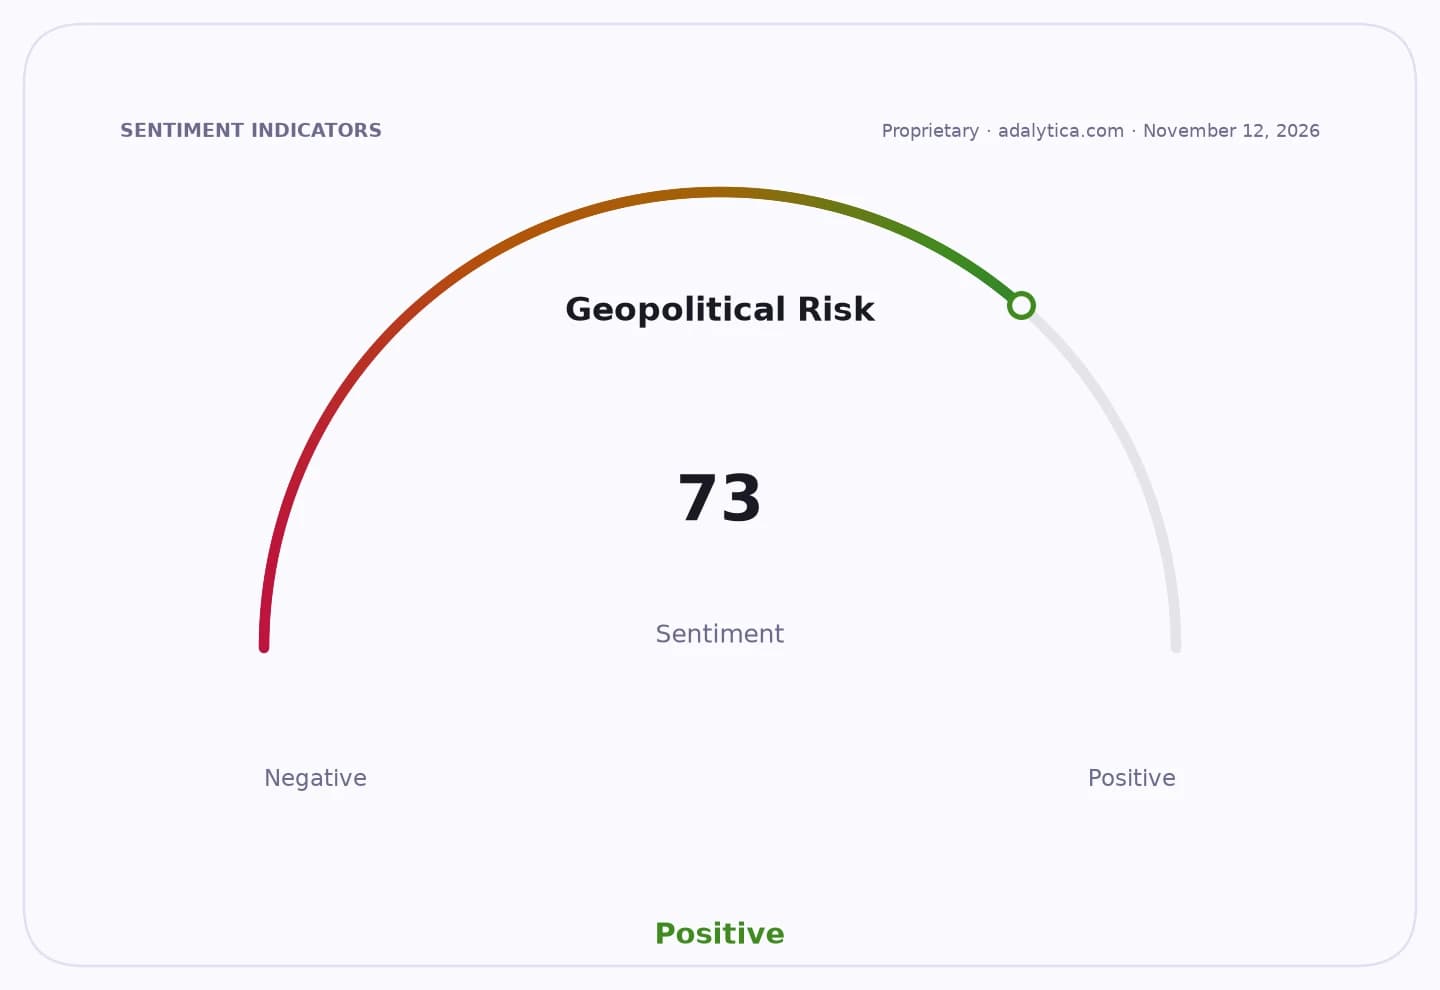
Sentiment Indicators
The stock’s recent trading suggests the market is cautiously embracing that view. Wuliangye fell to 76.99 yuan on Nov. 11 from 80.18 yuan two sessions earlier, but it remains well above its 50-day moving average of 74.3 yuan and far below its 200-day average of 87.26 yuan, underscoring both a short-term recovery and a longer-term valuation reset. Relative-strength readings near 67 show momentum is still positive, while the MACD remains above its signal line, a conventional technical indication that the rebound has not fully broken down.
The broader read-through extends beyond one company. If policy support improves confidence in manufacturing, regional enterprises and the broader private sector, the second-order effect can be better spending on higher-margin consumer products such as premium baijiu. That helps explain why investors keep tracking policy meetings even when the immediate focus appears to be on industrial or regional business groups rather than consumer demand directly. The market is effectively asking whether official support can translate into better cash flow for households and companies that buy discretionary goods.
The challenge is that the recovery is still fragile. Wuliangye’s shares have been volatile over the past year, with sharp swings between oversold and overbought territory, reflecting how quickly sentiment changes when investors try to price China’s consumer recovery. A sustained rerating would likely require more than policy rhetoric: it would need clearer evidence of stabilizing growth, firmer retail demand and more visible improvement in corporate spending.
For now, the investment case remains one of selective optimism rather than a full cyclical turn. Policy support may be enough to keep high-quality consumer names on watchlists, but the next leg higher will depend on whether macro stimulus translates into actual sales growth, not just better sentiment.
| Entity | Gains | Losses |
|---|---|---|
| Wuliangye Yibin | ▲Policy-backed demand hopes | ▼Near-term volatility |
| Premium baijiu sector | ▲Better confidence outlook | ▼Slow consumer recovery |
| Regional industrial firms | ▲Continued official support | ▼Weak private-sector activity |
| Short sellers / cautious bears | ▲— | ▼Momentum in rebound names |