1947 Oil & Gas is pressing ahead with its London listing at a smaller size than first planned, a sign that even in a receptive energy market the company is choosing to temper ambition to secure an AIM debut and fund its first acquisition.
1947 Oil & Gas cuts AIM listing to £30 million
The company now expects to raise about £30 million when it joins London’s junior market later this month, down from the £50 million it outlined in August, while keeping the offer price at 10 pence a share and targeting a market value of roughly £65 million. The revision matters because the flotation is intended not as a broad capital raise for growth at some distant point, but as the funding step that will allow 1947 to complete its acquisition of Houston-based Renaissance Offshore LLC and start operating a portfolio of producing assets immediately after admission.
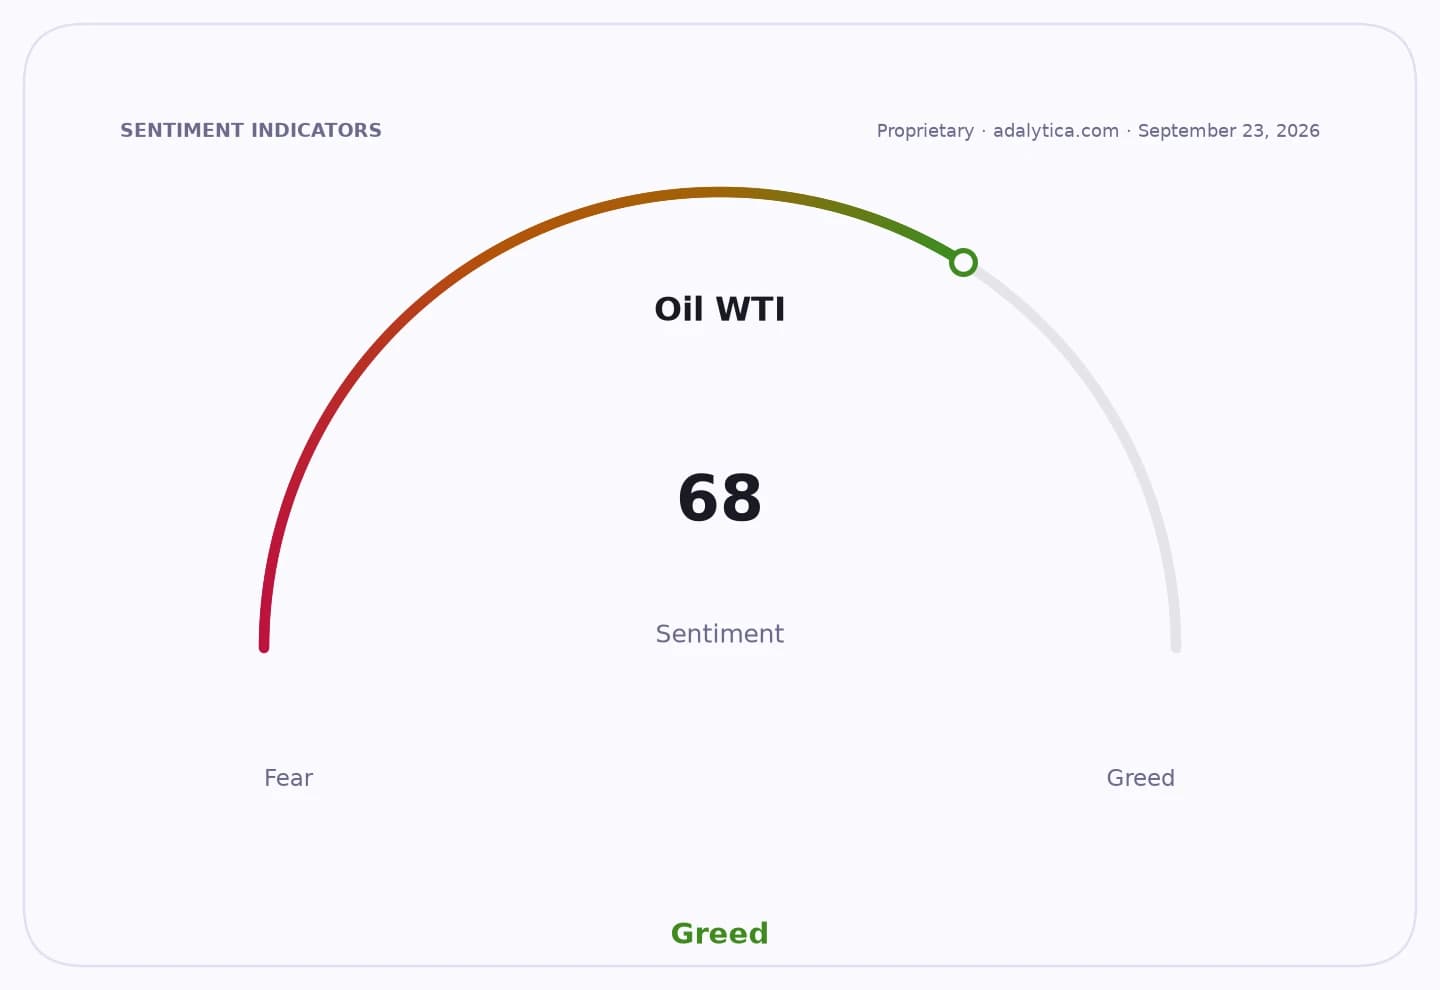
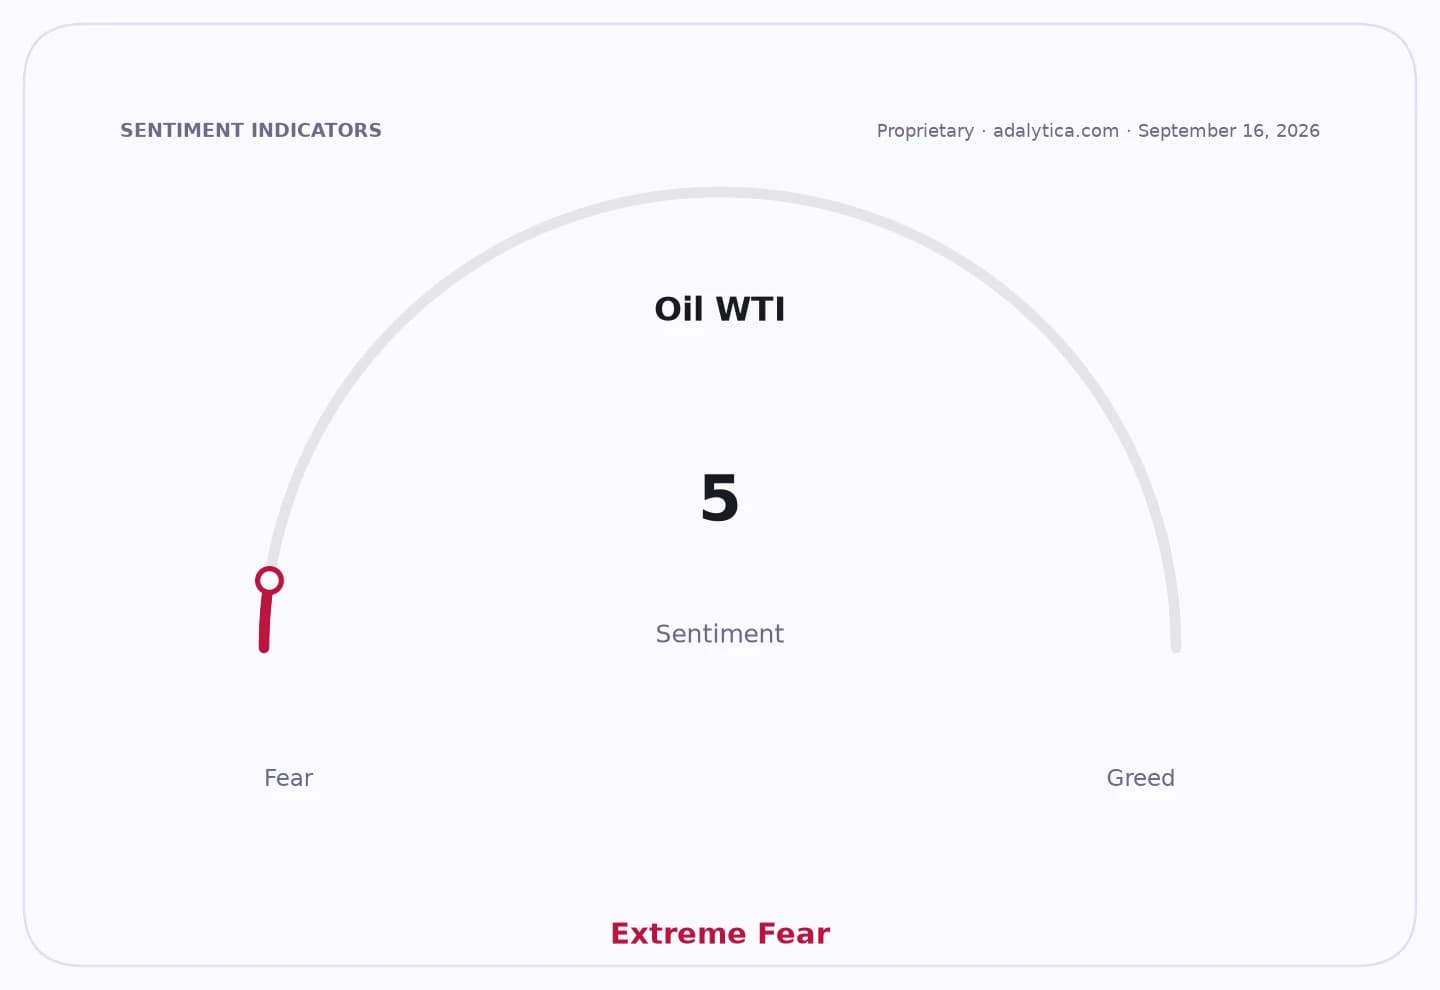
Sentiment IndicatorsⓘProprietary · adalytica.com · September 25, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That makes the deal more than a simple listing. 1947 is pitching itself as a cash-generating upstream operator built around mature hydrocarbon fields with low-cost development opportunities, a model that depends on disciplined capital deployment rather than exploration risk. In an industry where investors remain wary of heavy spending and long-dated returns, the emphasis on producing assets and immediate cash flow is designed to appeal to market demand for resilience rather than blue-sky reserves.
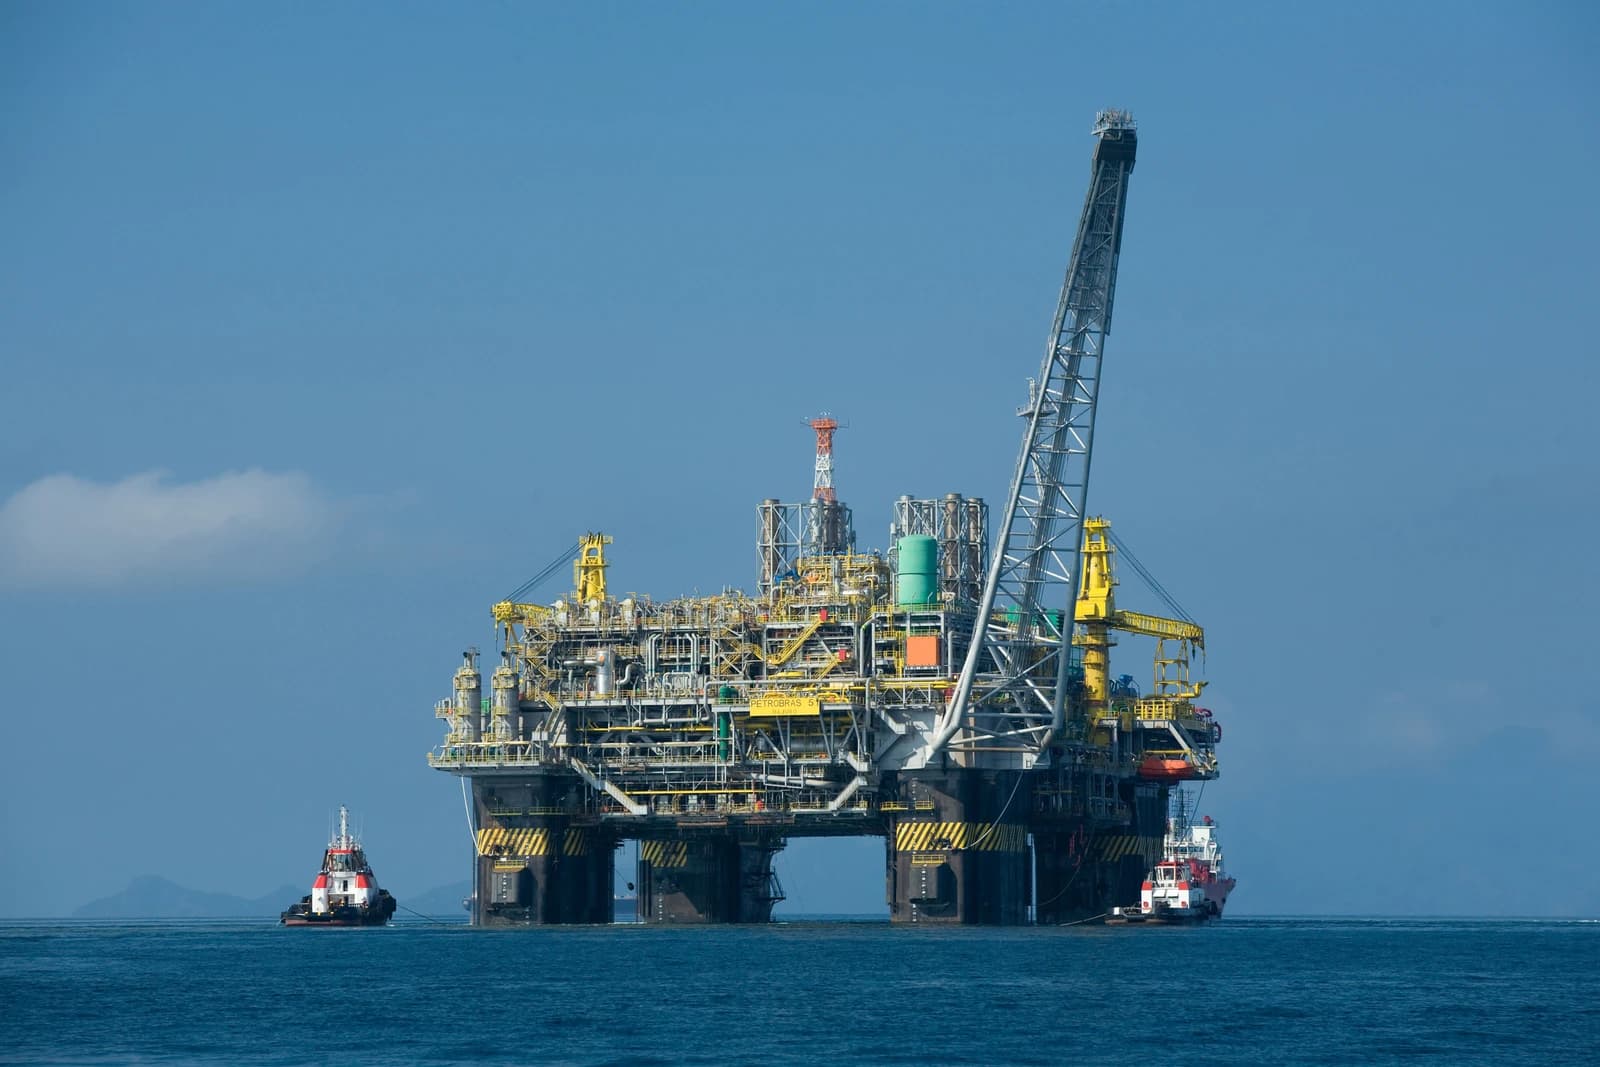
The proposed purchase of Renaissance brings 11 shallow-water Gulf of Mexico fields into the picture, giving the new London vehicle an operating base in an established basin with infrastructure already in place. That should reduce development risk versus frontier projects, though it also leaves the company exposed to oil price swings, operational decline rates and the ongoing costs of squeezing value from ageing assets. For investors, the question is whether the asset package can generate enough cash to justify the valuation and support future growth without repeated dilution.
The board composition is also notable. Executive chair Tim Duncan previously led Talos Energy, while chief financial officer Brian Romere and chief operating officer Larry Tolleson are both tied to Renaissance, underscoring that the transaction is being driven by an existing management team rather than a newly assembled listed shell. Their ownership interests in Renaissance mean they will benefit from the acquisition proceeds and from the shares issued as part of the deal, a detail that will likely be watched closely by investors assessing alignment and governance.
The move lands as oil sentiment remains firm. Adalytica’s oil trade signals show greed readings of 83, while Exxon Mobil’s shares have held above their 200-day moving average and near recent highs, suggesting continued appetite for energy exposure despite volatility in crude. Still, the broader market backdrop is mixed rather than euphoric, and the reduction in the fundraising target suggests 1947 is calibrating to that reality.
For London’s AIM market, the transaction is a reminder that the listings pipeline for energy names is still alive, but financing conditions remain selective. If 1947 can close the raise and complete the Renaissance acquisition, it will offer investors a pure-play cash-flow story tied to mature offshore production. If not, the cut in proceeds may be read as an early sign that appetite for the float is narrower than management initially hoped.
| Entity | Gains | Losses |
|---|---|---|
| 1947 Oil & Gas | ▲London listing; acquisition funding | ▼Smaller IPO proceeds |
| Renaissance Offshore | ▲Acquisition completion; public-market backing | ▼Control under new owner |
| AIM investors | ▲Exposure to producing assets | ▼Dilution; oil-price risk |
| Existing managers | ▲Equity-linked upside | ▼Governance scrutiny |