Alamos Gold investors are getting a reminder that a rising gold price does not automatically translate into rising shareholder value.
Alamos Gold target cut on costs and cash flow
CIBC cut its price target on the Toronto-listed miner to C$69 from C$75 while keeping an “Outperformer” rating, a move that underscores how much the market is now focused on production execution, cost control and free cash flow rather than simply the direction of bullion. That distinction matters because gold miners live or die by margins, and the latest broker call suggests Alamos’ valuation may have to account for a tougher operating backdrop even if the long-term investment case remains intact.
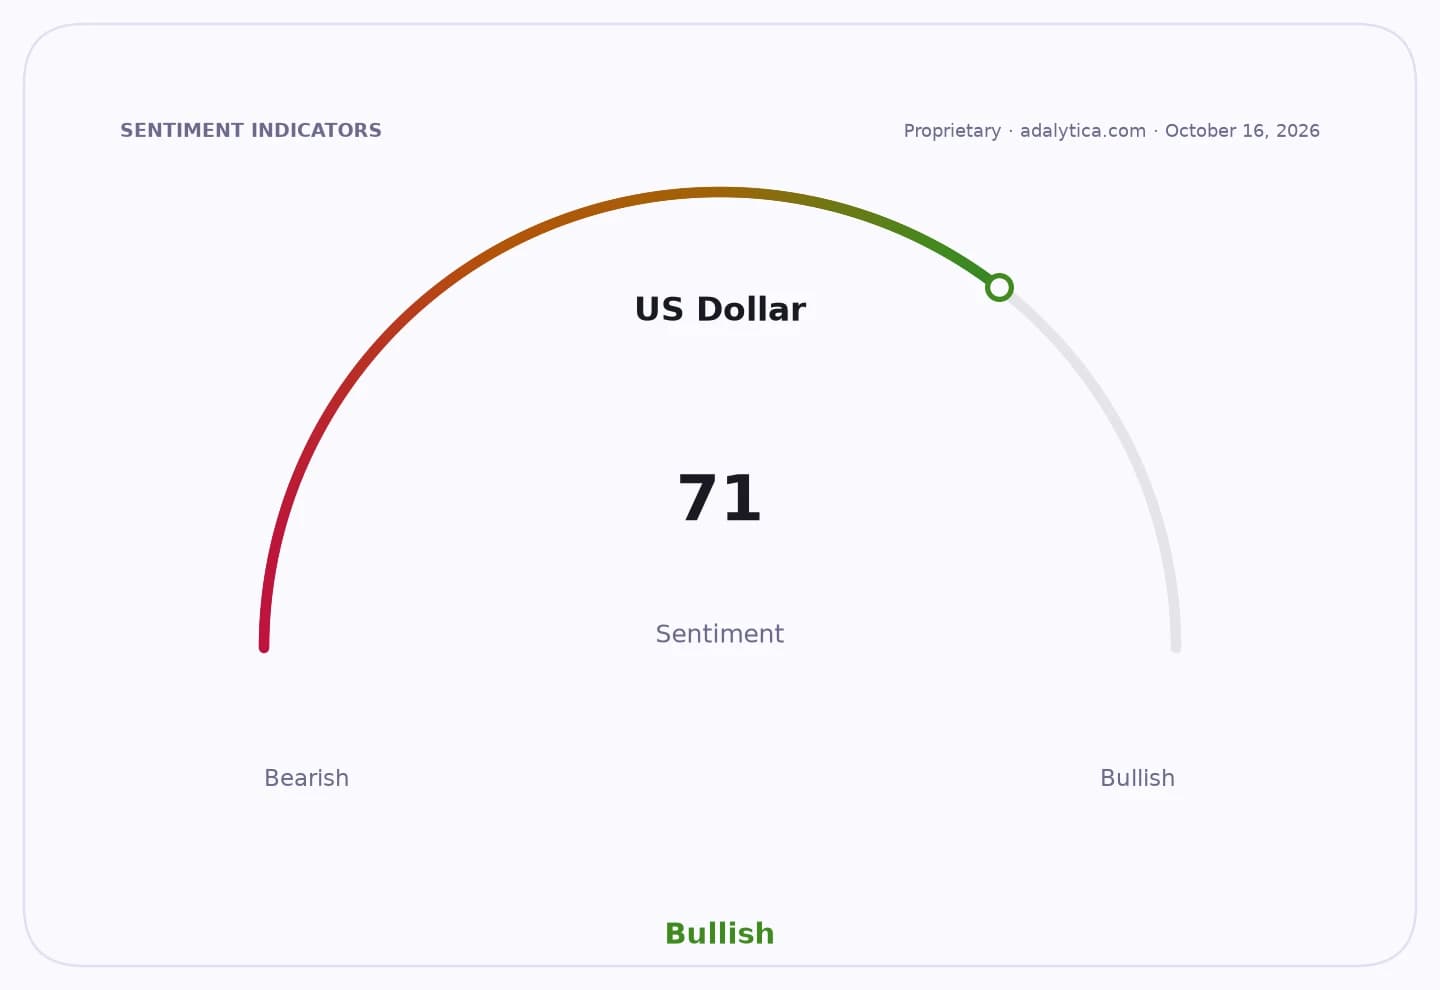
Sentiment IndicatorsⓘProprietary · adalytica.com · October 21, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The bank’s softer view reflects a broader reset across the sector. CIBC said it expects weaker production and higher costs heading into upcoming quarterly reports and also trimmed its gold and silver price forecasts as macro headwinds build. For Alamos, the issue is especially acute at Young-Davidson, where media reports have pointed to cost inflation, higher spending and remediation work weighing on cash generation. Investors buying gold stocks for leverage to the metal need to remember that mines are businesses, and businesses are priced on the cash they keep after capital spending, not just the ounces they produce.
That helps explain why the stock has fallen 16% this year, even as gold itself has remained a powerful long-term store of value. The shares have also slipped below key technical markers, with the stock recently trading under its 50-day and 200-day moving averages, while the relative strength index has hovered in neutral-to-soft territory. That is not a disaster for patient investors, but it does show a market that is waiting for proof rather than paying up for promises.
Still, the options market is telling a more upbeat story. More than 3,338 call options traded in the latest session, about 1.4 times expected volume, while the put-to-call ratio came in at 0.08. That does not guarantee a rebound, but it does suggest some traders are positioning for a recovery into November expiration. For long-term investors, the more important question is whether that optimism is grounded in improving operations or just in hopes of a better gold tape.
The next major checkpoint arrives with quarterly results due Oct. 28. That report should show whether Alamos can defend margins, contain costs and keep free cash flow from being swallowed by remediation spending at Young-Davidson. If management can show that the recent pressure is temporary and operational discipline is returning, the lower price target may prove more like caution than conviction.
For now, Alamos remains a stock worth watching rather than chasing. The long-term appeal of gold miners is intact, but investors should insist on evidence that the company can turn a strong metal backdrop into sustainable cash generation.
| Entity | Gains | Losses |
|---|---|---|
| CIBC | ▲More cautious valuation | ▼Less upside in target price |
| Alamos Gold bulls | ▲Possible rebound if execution improves | ▼Near-term pressure from costs |
| Short-term options traders | ▲Momentum-linked upside bets | ▼Risk of disappointment if earnings miss |
| Long-term value investors | ▲Lower entry point if cash flow holds | ▼Need patience for operational turnaround |