Amazon has committed more than $1 billion to a multiyear strategic deal with Synopsys, a move that broadens the cloud giant’s push to build and industrialize its own AI semiconductors at a time when infrastructure spending is reshaping the economics of cloud computing.
Amazon Synopsys deal expands AWS chip design push
The agreement matters because it is not just another software license. It ties together Amazon’s custom-chip roadmap, its AWS cloud, and Synopsys’ design tools in a way that should shorten development cycles for Trainium, Graviton and Nitro while also creating a more scalable commercial model for Synopsys. In practical terms, Amazon is paying to speed up the engineering of chips that underpin its own margins and its competitiveness against rivals that still lean heavily on Nvidia silicon.
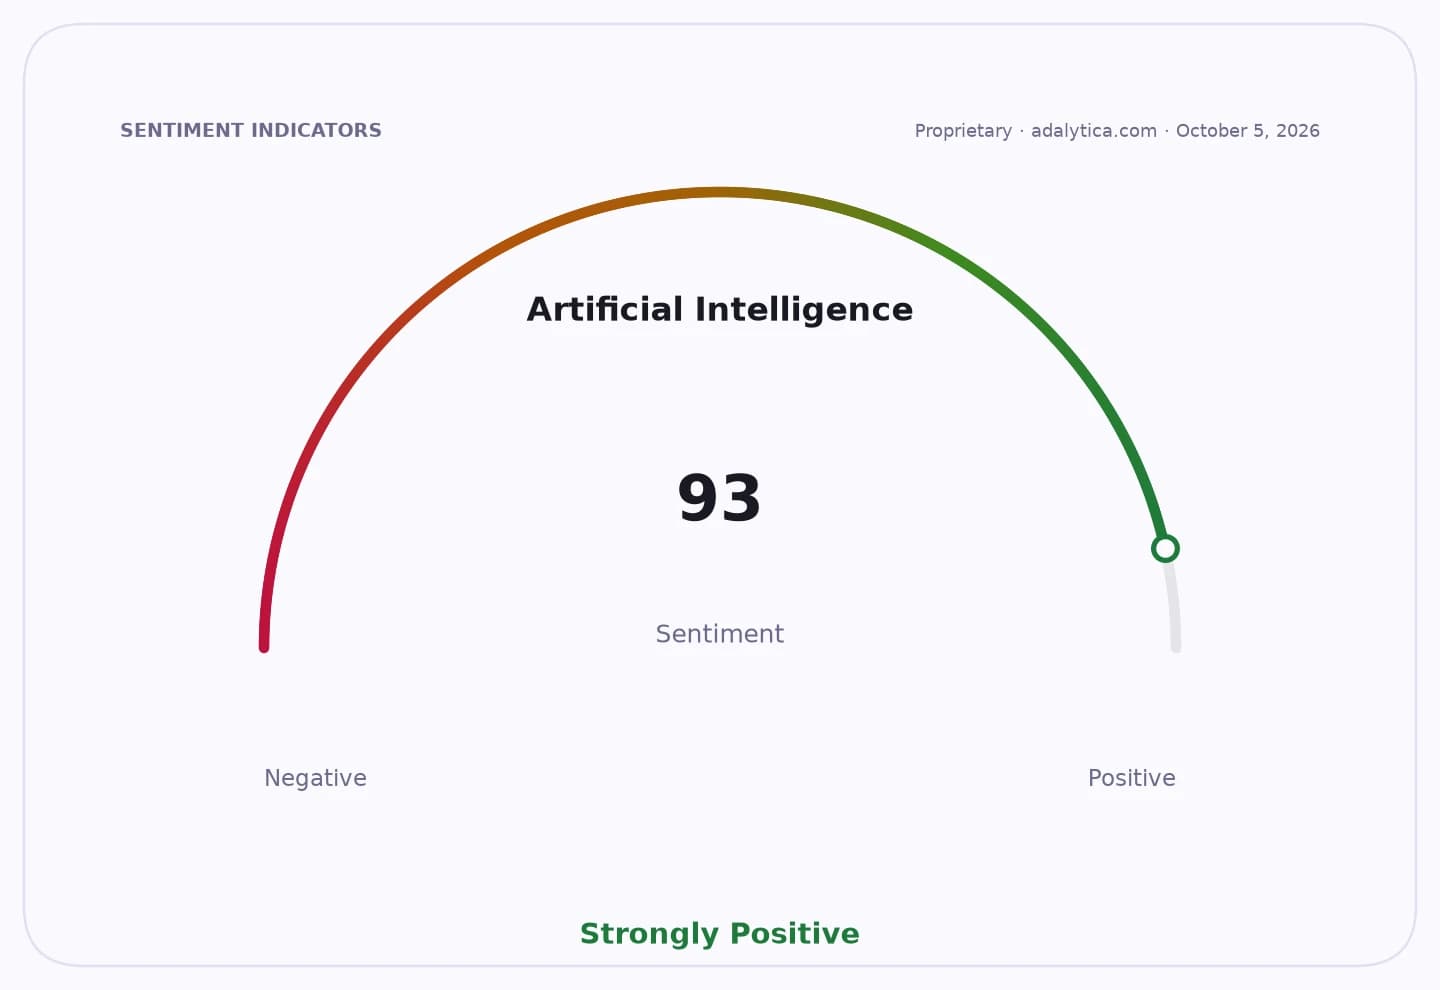
Sentiment IndicatorsⓘProprietary · adalytica.com · October 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Under the deal, Amazon will expand its use of Synopsys semiconductor IP, electronic design automation, simulation and analysis tools, and agentic AI systems. The companies said they will co-develop custom agentic AI capabilities and optimize Synopsys’ multiphysics software to run faster on Amazon’s Trainium and Graviton processors. Synopsys will also use Amazon EC2, cloud storage and Amazon Bedrock in its own R&D and AI application work.
The structure is important for both companies. Instead of relying mainly on fixed licensing fees, the agreement adds a royalty component linked to chip shipments, aligning Synopsys’ revenue more closely with Amazon’s scale-up of custom silicon. That gives Synopsys a longer-duration growth lever if Amazon’s in-house chips gain adoption across AWS, while Amazon gets a tighter integration between design software and its own hardware stack.
For Amazon, the deal extends a strategy that has become central to AWS economics: build more of the compute stack internally to reduce dependency on third-party suppliers and control performance, cost and product differentiation. Custom processors such as Graviton and Trainium have already become strategic tools in AWS, and the Synopsys partnership suggests Amazon is willing to spend heavily to accelerate that roadmap. The company has already been ramping capital spending across technology infrastructure, and this latest commitment reinforces that AI and cloud capacity remain its dominant investment priorities.
For Synopsys, the agreement deepens exposure to one of the largest buyers of semiconductor design tools and custom silicon in the world. The company has spent years positioning itself as indispensable to chipmakers and system designers, but the market is increasingly rewarding firms that can show AI-inflected growth and tighter customer integration. The new royalty-linked model could be especially attractive if Amazon’s chip volumes rise, though it also ties more of Synopsys’ upside to execution at a single customer.
Investors have already been treating both names as key beneficiaries of the AI buildout, but the market reaction also underscores the difference between them. Amazon’s shares have been volatile as investors weigh heavy spending against future operating leverage, with the stock recently trading just above its 50-day moving average and below prior highs. Synopsys shares have been far more unsettled, reflecting concerns over growth durability and the impact of customer caution on software spending. The partnership offers both companies a potential counterweight: Amazon gets a path to better unit economics in AI infrastructure, while Synopsys gets a more embedded role in the chip-design value chain.
The broader message is that the AI hardware race is moving upstream. It is no longer just about who supplies the accelerators; it is also about who controls the tools, simulation environments and engineering workflows that determine how quickly those chips can be designed, validated and scaled. Amazon’s move suggests the cloud wars are entering a phase where custom silicon and design software are as strategically important as data centers and model access.
The key question now is execution. If Amazon can translate this investment into faster Trainium iteration and wider internal adoption, it could improve AWS economics over time and narrow the gap with Nvidia-dependent competitors. If not, the spending will look like another costly arms race in a sector already under pressure to prove returns. For Synopsys, the upside depends on whether this becomes a template for more customer-specific, usage-linked deals across the industry.
| Entity | Gains | Losses |
|---|---|---|
| Amazon | ▲Faster chip development; better AWS economics | ▼Higher upfront spending |
| Synopsys | ▲Royalty-linked revenue growth; deeper Amazon tie-in | ▼Greater customer concentration |
| AWS custom silicon | ▲Faster optimization and deployment | ▼Dependence on execution |
| Nvidia | ▲No direct gain | ▼Potentially more cloud-side substitution |