Apple shares slide into earnings with the stock under pressure from profit-taking, a rich valuation and renewed doubts about how much room is left for upside after a 28% rebound from June lows.
Apple slides into earnings on valuation worries
The shares fell 2.2% to $337 on Monday, pulling back after last week’s run toward a record high of $351.73 and leaving Apple again just behind Nvidia in the race to be the world’s most valuable company. Both groups are now hovering just below the $5 trillion mark, a reminder that mega-cap leadership is being decided as much by sentiment and positioning as by fundamentals.
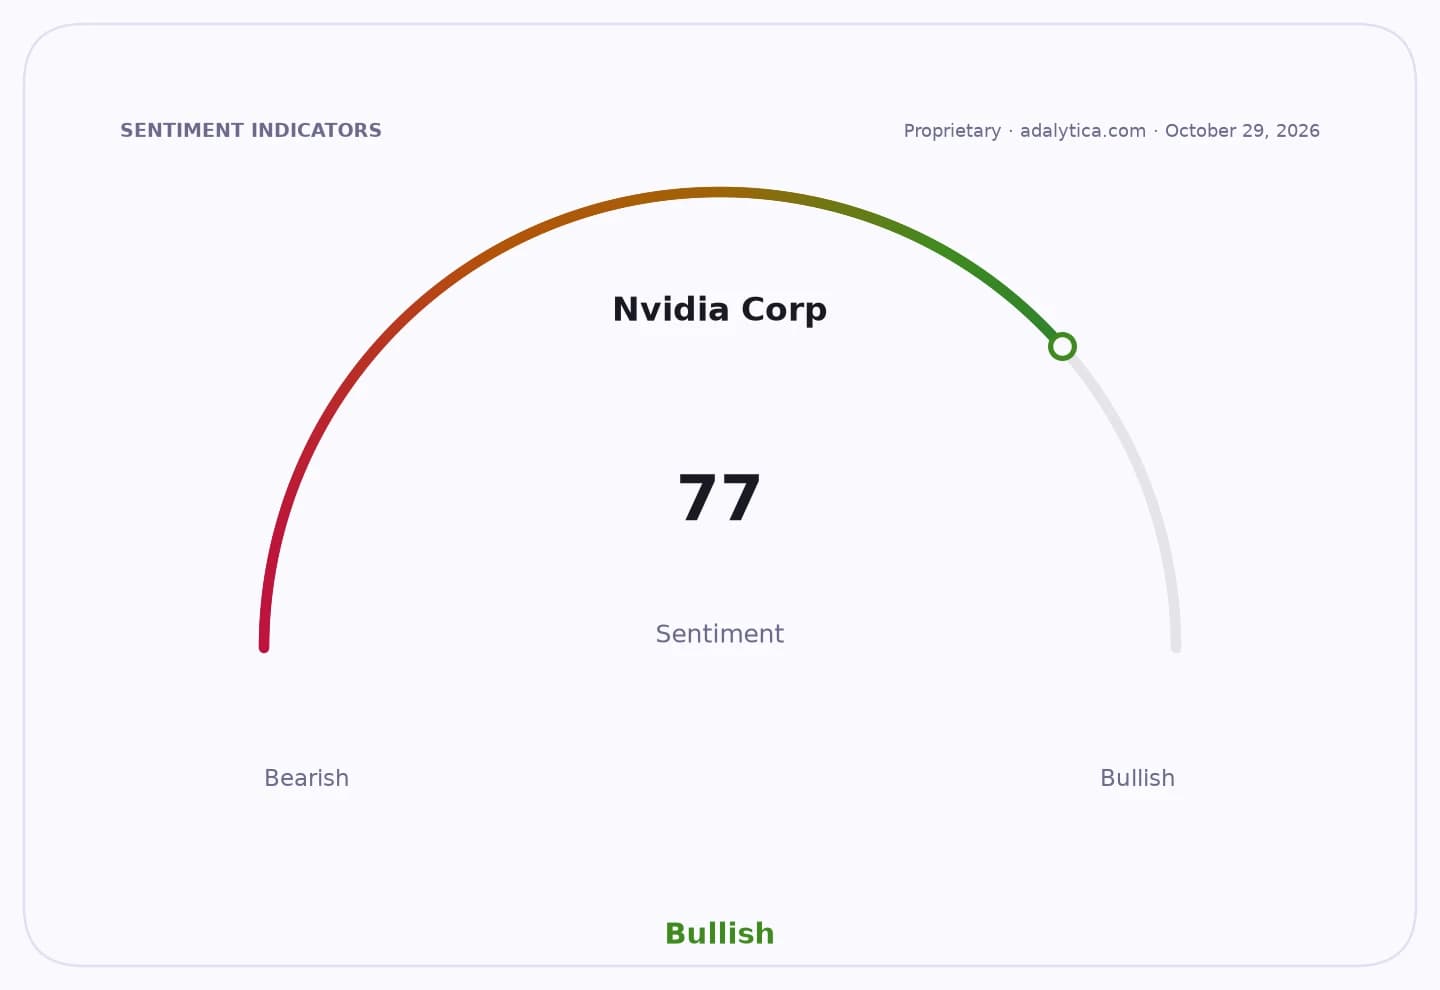
Sentiment Indicators
For investors, the problem is timing. Apple has added more than $1 trillion in market value since late June on steady revenue growth and rising free cash flow, reinforcing the view that it is a defensive way to own Big Tech. That appeal has also helped the stock trade at its richest level since 2008, with a forward price-to-earnings ratio of 36, nearly twice the S&P 500’s valuation.
At that level, the bar for Tuesday’s after-hours results is high. Any miss on iPhone demand, margins or the outlook could trigger a sharp reset, especially with expectations built around the debut of the new foldable iPhone Duo. Apple has said demand has been “extraordinary,” but analysts say tight supply may be doing as much work as strong demand, and early reports of display cracks could limit appeal beyond first-wave buyers.
The new model matters because it is Apple’s biggest design shift in years and carries a starting price of $1,999. JPMorgan’s Samik Chatterjee said lead times for the Duo were unchanged in week eight of the product cycle, while wait times for Pro models are normalizing, suggesting overall demand may be softer than last year unless the premium device can sustain momentum.
Apple’s latest filing also underscored the margin issue hanging over the company, warning of supply constraints and rising component costs, including advanced semiconductors, memory and storage. That is important not just for Apple’s earnings power but for the broader market debate over whether the biggest consumer tech names can keep expanding profits while AI-related input costs climb.
The next catalyst is the earnings call and management’s guidance on demand, pricing and margins. With the stock priced for near-perfect execution, even solid results may not be enough to keep Apple ahead of Nvidia for long.
| Entity | Gains | Losses |
|---|---|---|
| Apple bulls | ▲Strong earnings, iPhone Duo traction | ▼Multiple compression risk |
| Apple bears | ▲Valuation reset, margin concerns | ▼Misses if demand holds |
| Nvidia shareholders | ▲Valuation leadership, AI strength | ▼Lose top-market-cap crown if Apple rallies |
| S&P 500 buyers | ▲Defensive mega-cap exposure | ▼Concentration risk from rich valuations |