Applied Optoelectronics is benefiting from one of the biggest themes in the market — exploding demand for AI networking gear — but investors still can’t ignore a very old problem: supply constraints.
Applied Optoelectronics cites slower 2027 capacity ramp
Shares of the optical networking company edged higher after its third-quarter update, even as management warned that manufacturing capacity will ramp more slowly than previously expected in 2027. For long-term investors, that tension is the whole story. Demand for the components that connect artificial intelligence data centers remains strong, but a company can only turn that demand into durable profit if it can build enough product on time.
Sentiment Indicators
That matters because optical networking is becoming a critical pick-and-shovel business in the AI buildout. Every new cluster of GPUs needs the high-speed connections that move data between servers and across data centers. When AI spending is expanding this quickly, the winners are often not just the headline chip makers, but also the suppliers that can reliably scale alongside them.
Applied Optoelectronics is trying to do exactly that, but its latest comments show how hard the execution can be. Construction delays are slowing the company’s ability to expand output, which could leave some demand unfulfilled in the near term. That makes AAOI a classic high-beta AI stock: huge upside if the ramp goes well, but sharp volatility if timing slips.
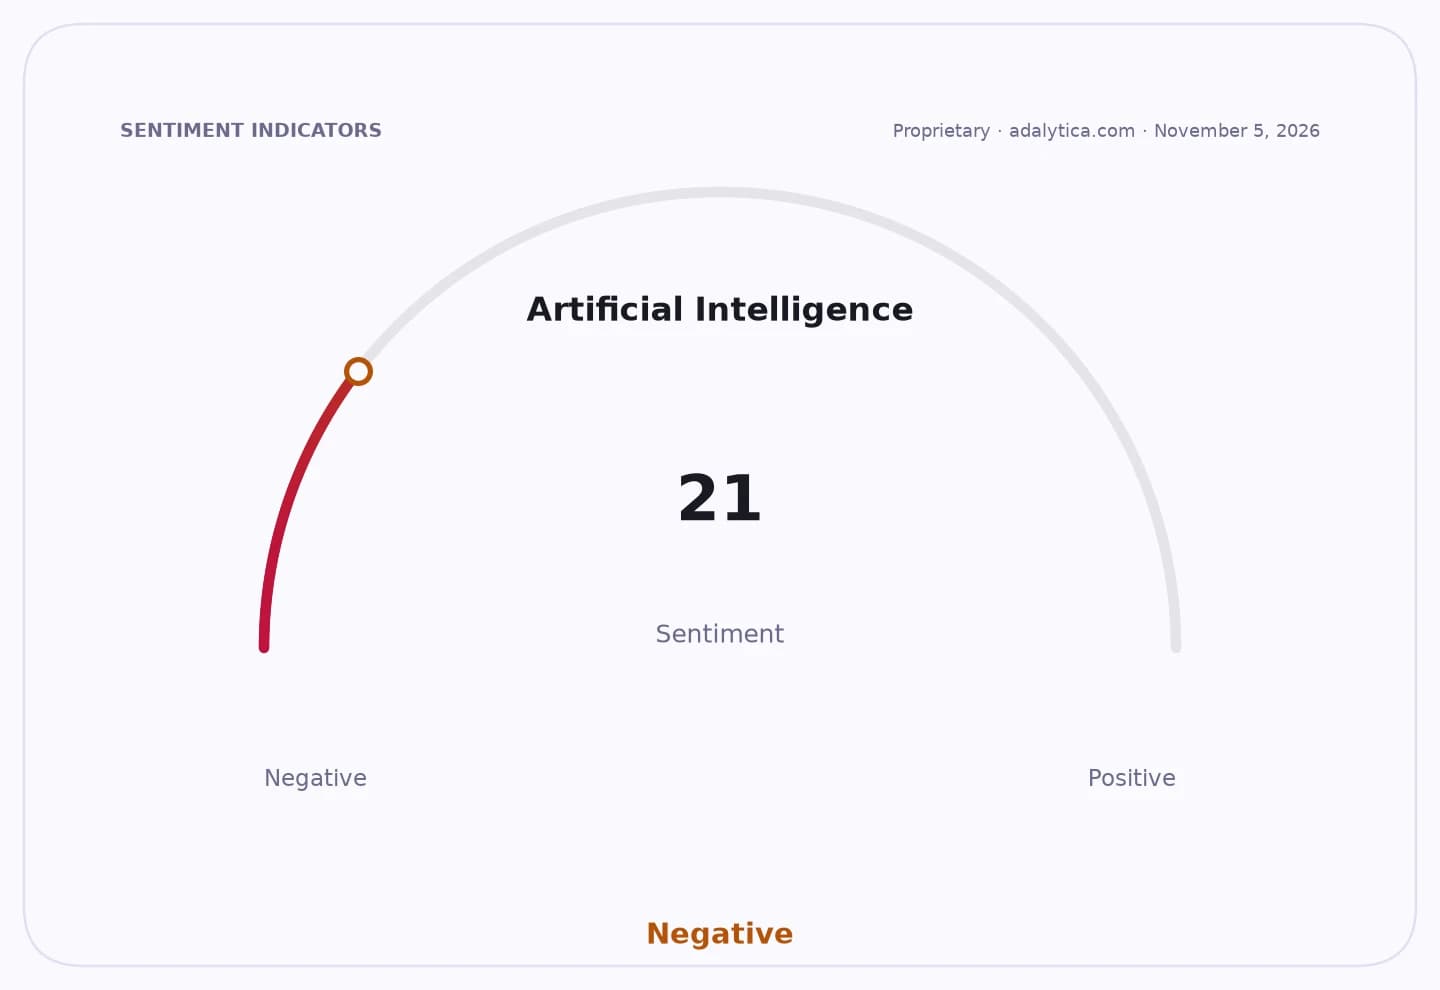
Artificial Intelligence
The stock’s recent trading underscores that point. AAOI has swung violently this year, with the share price ranging from roughly $223 in May to below $50 in early November before rebounding to about $55.86 in the latest session. On technical measures, the shares remain well below the 50-day and 200-day moving averages, a sign the market is still cautious even after the bounce.
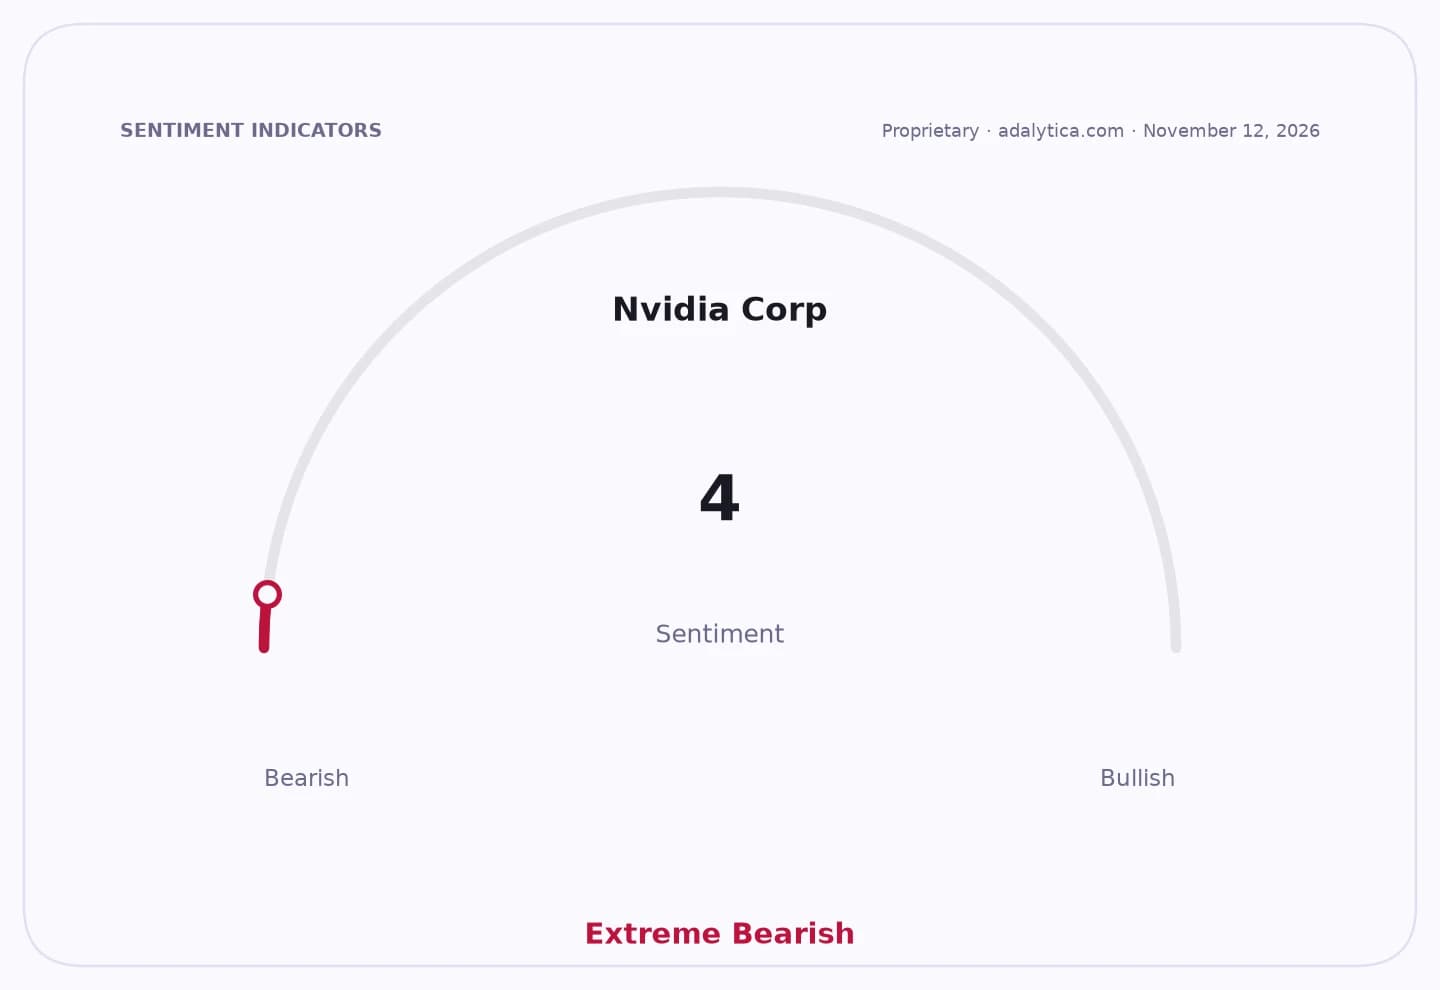
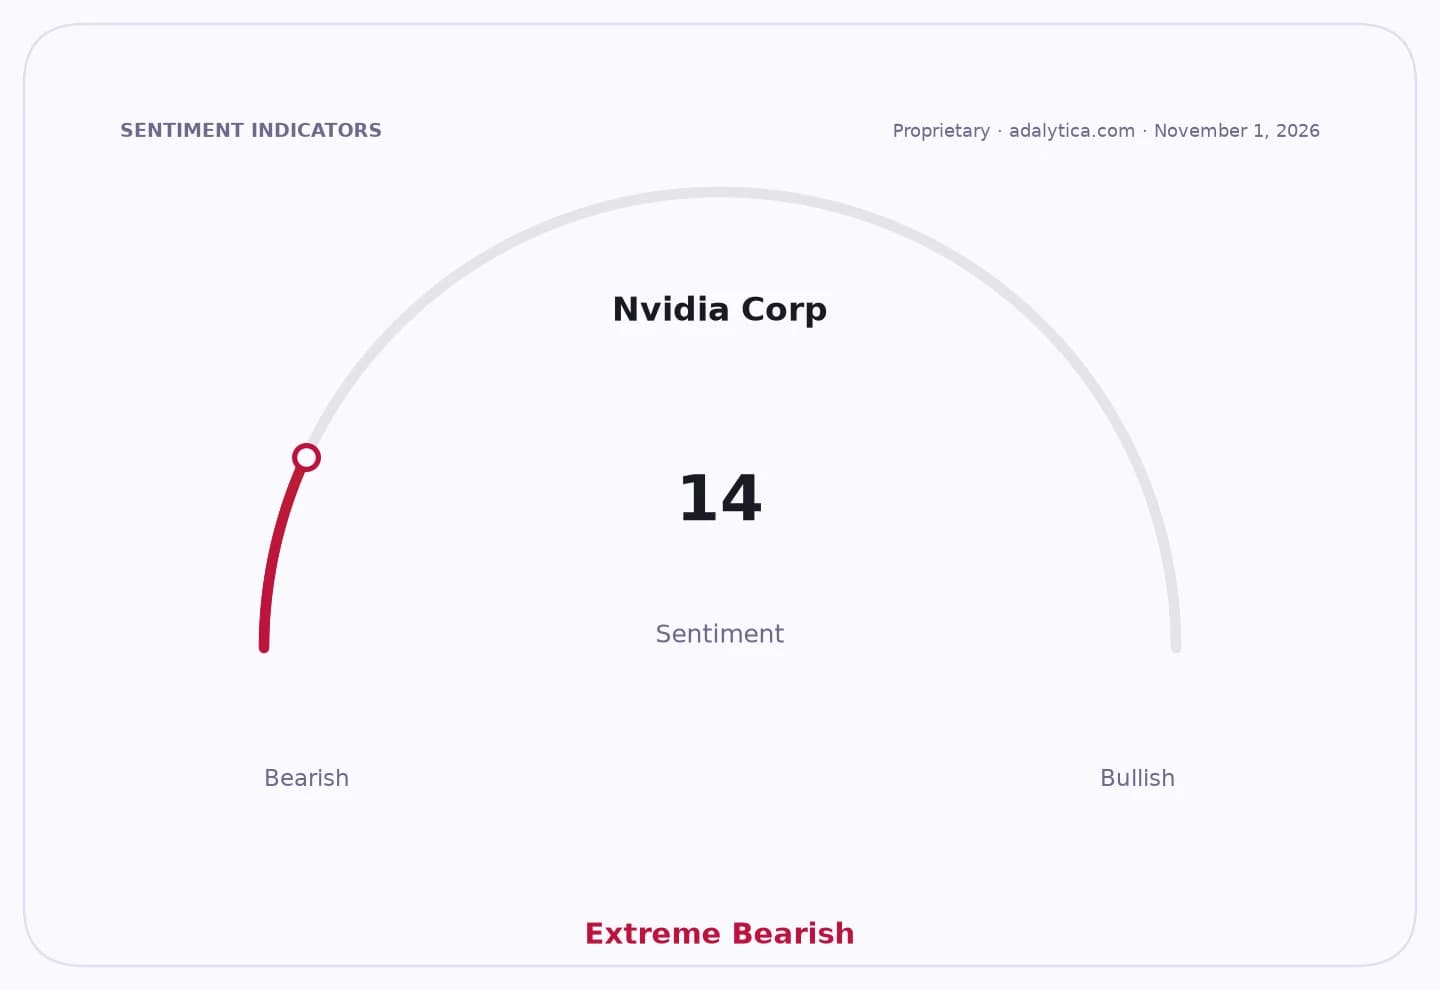
By contrast, Nvidia — the dominant AI infrastructure name — has also been hit by a pullback, but its longer-term position is far stronger thanks to its scale, customer concentration and pricing power. That contrast matters for investors: the AI trade is not just about demand anymore, but about which companies can convert demand into production, revenue and free cash flow without choking on their own growth.
For AAOI, the next few quarters will likely hinge on the same variables management highlighted in its filing: customer deployment schedules, capital spending, supply chain conditions and the broader macro backdrop. The long-term opportunity remains intact if AI data center spending stays elevated, but the path will probably stay bumpy.
Investors looking at AAOI should treat it as a speculative way to play AI infrastructure, not a smooth compounder. If you want exposure to the theme, diversification matters, and patience matters even more. The company could still be worth watching closely, but only for investors comfortable with volatility and execution risk.
| Entity | Gains | Losses |
|---|---|---|
| Applied Optoelectronics | ▲AI networking demand | ▼Slower capacity ramp |
| AI data center builders | ▲Faster optical component supply | ▼Project delays |
| Nvidia and peers | ▲Broader AI spending growth | ▼Near-term investor caution |
| Long-term AI investors | ▲Potential infrastructure upside | ▼Volatility and timing risk |