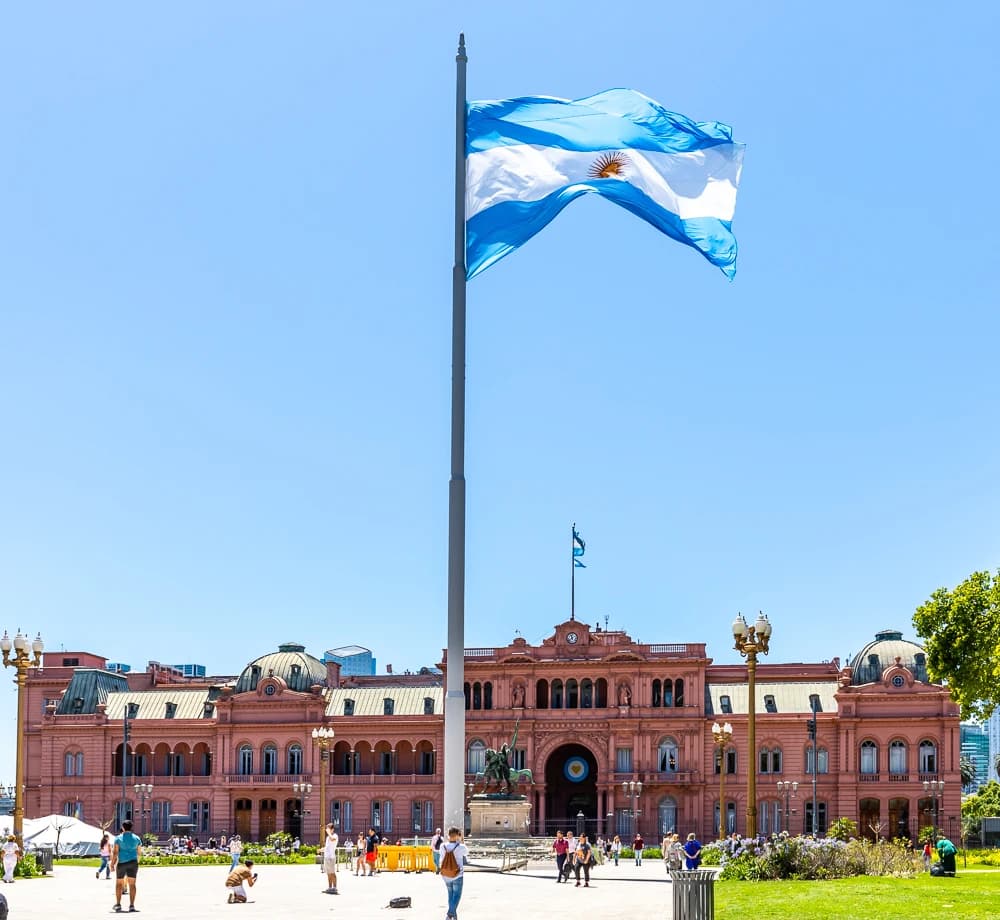
Argentina is facing renewed IMF pressure to keep cutting energy subsidies just as the Fund has sharply worsened its outlook for growth, inflation and unemployment, underscoring the fiscal and social strain behind Buenos Aires’ adjustment program.
Argentina IMF Pressure to Cut Energy Subsidies
The request matters because energy subsidies remain one of the fastest ways for Argentina to support household incomes and contain inflation, but they also absorb scarce fiscal resources in an economy still struggling to stabilize after years of monetary and external stress. The IMF is essentially telling policymakers that broad-based price relief is too costly and too distortive, and that any support should be narrowed to the poorest households if the government wants to protect its budget and preserve market confidence.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 19, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
In its October 2026 Regional Economic Outlook for the Americas, the Fund said general subsidies and other untargeted interventions suppress price signals and can encourage excess energy demand. It urged governments to redesign assistance around direct transfers to vulnerable families while preserving the subsidy reductions already achieved in countries such as Argentina, Bolivia and Ecuador. The message fits a broader IMF push across Latin America to reduce deficits and debt, with fiscal space limited in much of the region heading into 2027.
For Argentina, the timing is uncomfortable. IMF Managing Director Kristalina Georgieva said separately that the country could repay its IMF debt ahead of schedule, comparing it with Greece, in a remark that sounded supportive but came alongside a darker macro assessment. Argentina still owes about $60 billion to the Fund, making it its largest debtor, so any discussion of early repayment sits alongside the reality that the country remains dependent on continued policy compliance and external financing credibility.
The Fund lowered its 2026 growth forecast for Argentina to 2.1% from 3.5% and its 2027 estimate to 3.5% from 4%. It also lifted its inflation projections to 29.5% for this year from 25% and to 18% for next year from 12.5%, while unemployment is now seen at 7.6% in 2026 and 7.1% in 2027. Taken together, those revisions suggest the adjustment path is proving more inflationary and less growth-supportive than previously expected.
That combination is what investors care about most. If Argentina cuts subsidies too slowly, fiscal repair and IMF relations could weaken; if it cuts too quickly, inflation and social pressure could intensify, complicating President Javier Milei’s stabilization effort and raising political risk. The Argentine exchange-traded fund ARGT has already traded below its 50-day and 200-day moving averages, while emerging-market broad funds have also been under pressure, reflecting caution toward risk assets as U.S. rates stay elevated and global risk appetite remains fragile.
The IMF’s stance leaves Buenos Aires trying to square an increasingly difficult circle: keep trimming the state’s energy bill, protect the most vulnerable, and still deliver disinflation and growth. For investors, the next catalyst will be whether the government can maintain fiscal discipline without triggering a backlash that forces it to slow reforms or revisit subsidy cuts.
| Entity | Gains | Losses |
|---|---|---|
| IMF | ▲Fiscal credibility | ▼Short-term political goodwill |
| Argentine government | ▲Debt-relief prospects | ▼Subsidy spending flexibility |
| Low-income households | ▲Targeted cash support | ▼Broad price relief |
| Argentine consumers and utilities | ▲Clearer pricing signals | ▼Near-term cost pressure |