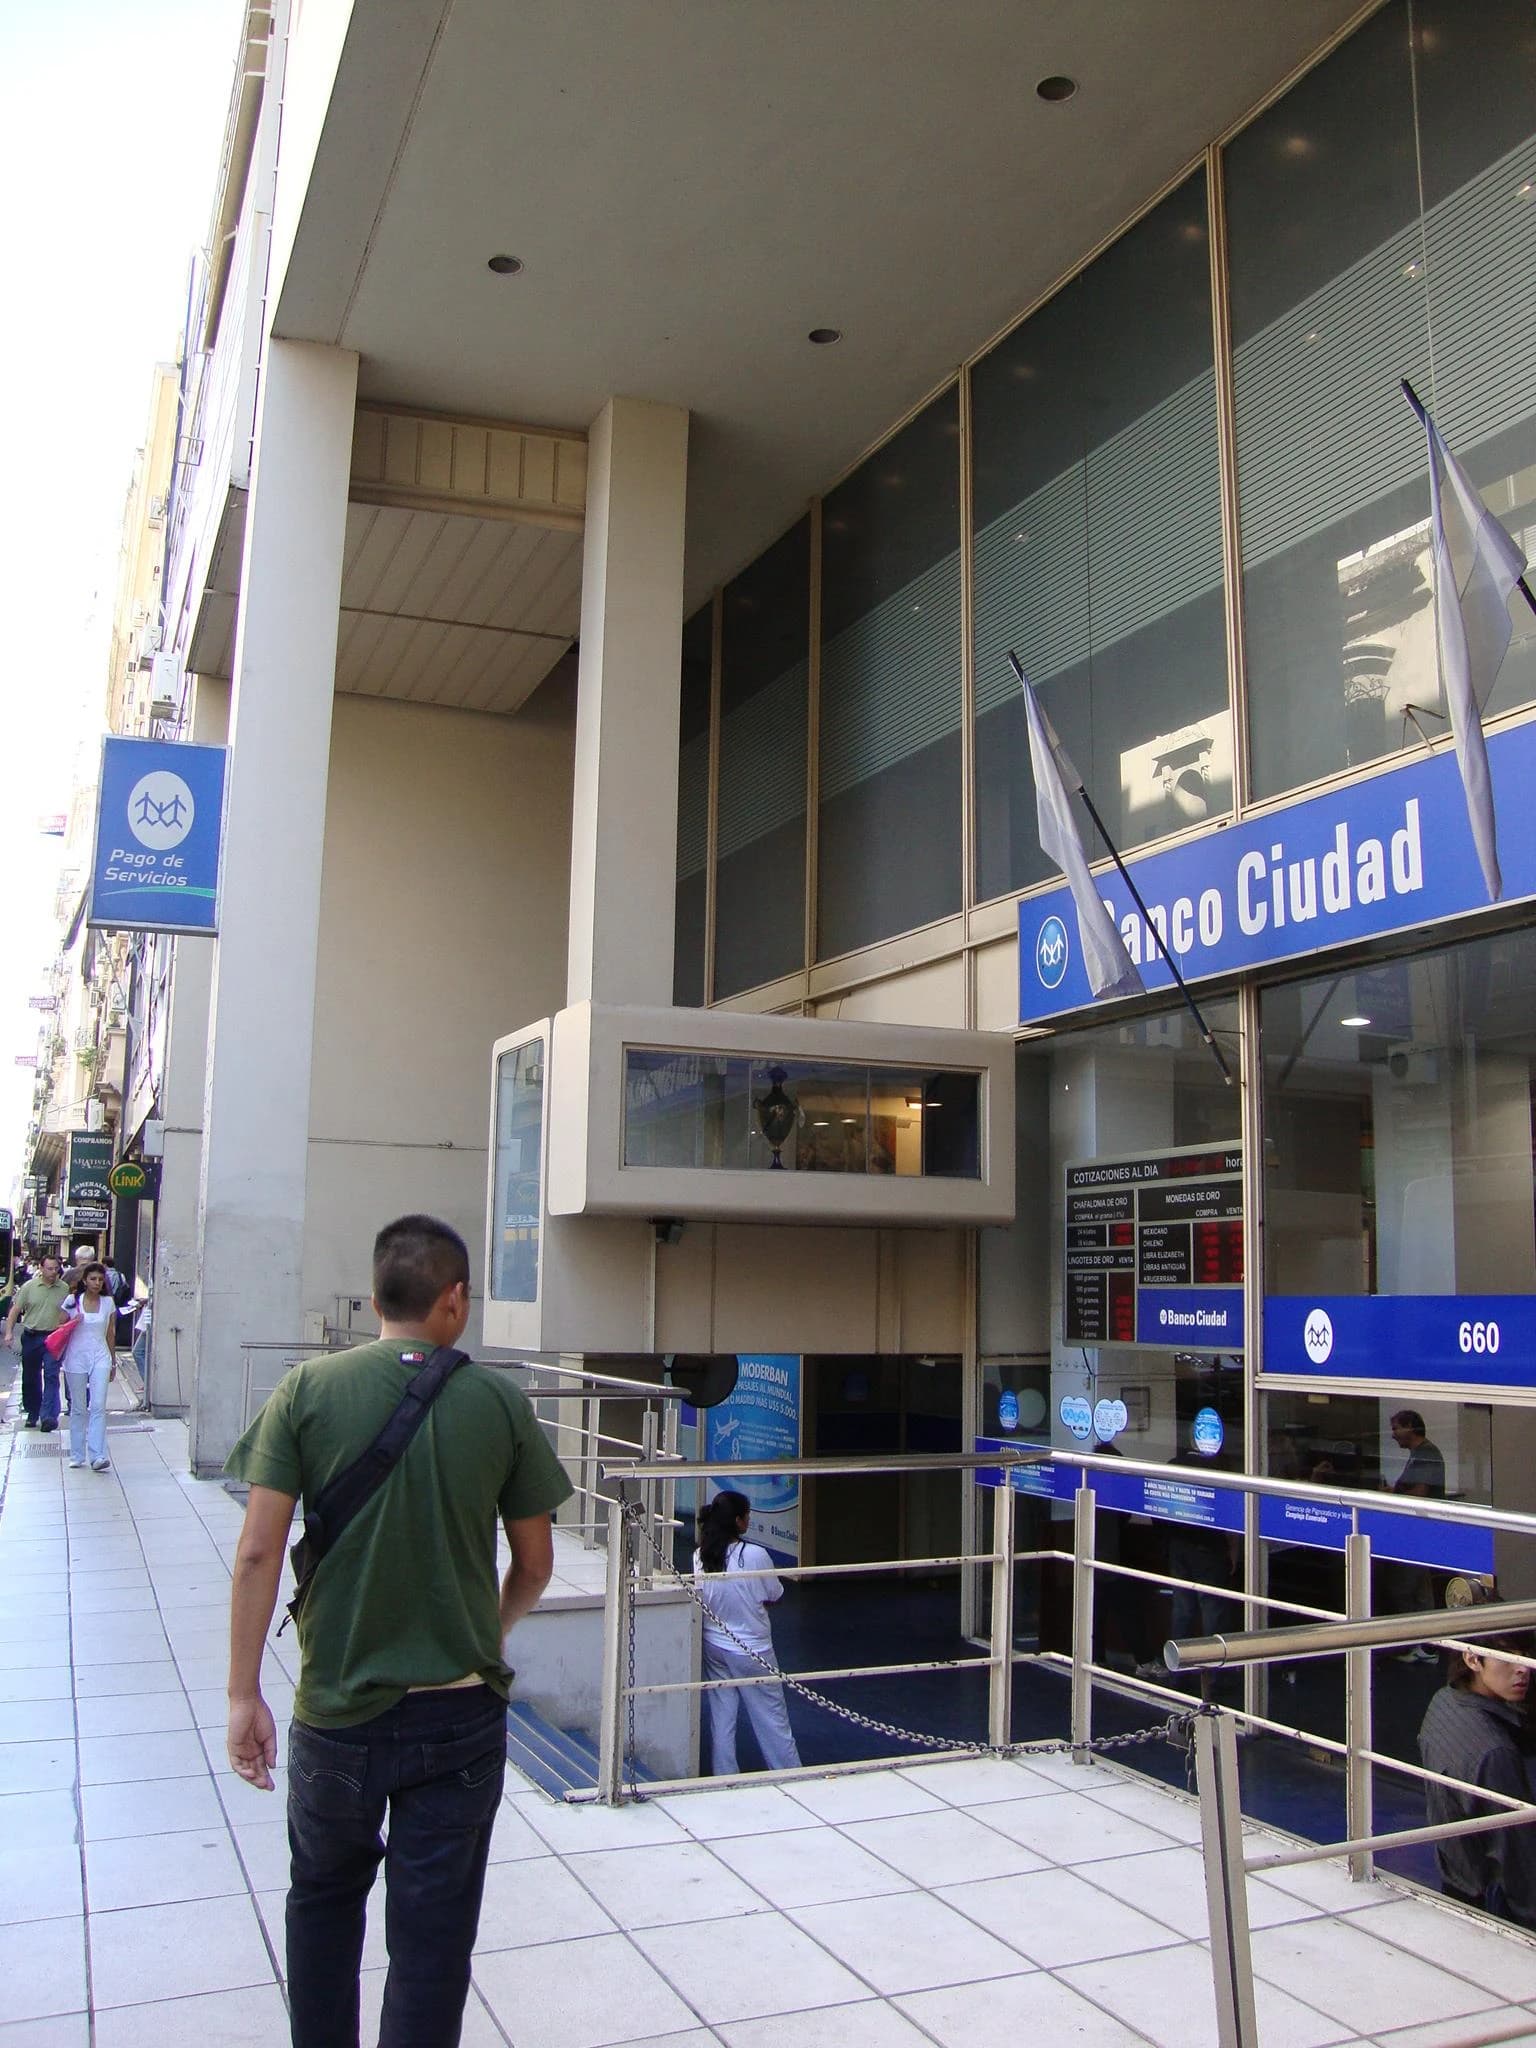
Argentina’s personal loan rates have eased since the start of the year, but borrowing still costs households more than three times the expected inflation rate, underscoring how weak credit demand and elevated delinquencies are keeping family finance under strain.
Argentina personal loan rates fall, borrowing stays high
The average nominal annual rate on personal loans fell to 64.38% from 73.71% at the beginning of the year, according to the central bank’s daily survey. Yet once principal, interest and taxes are included, the effective cost climbs to about 120%, Econométrica said — far above economists’ projection for consumer prices of 21% over the next 12 months. In real terms, that leaves borrowing expensive even after the recent decline in rates.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 9, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That gap matters because household credit is one of the clearest gauges of consumer demand and financial stress in Argentina. Central bank Vice President Vladimir Werning said banks that try to offset bad loans by charging families even higher rates are making it harder to restore a healthy repayment cycle. His comments reflect a broader policy concern: once rates are high enough to compensate for elevated default risk, they can become self-defeating by pushing more borrowers into delinquency.
The strain is showing up in loan volumes. The personal-loan book reached 21.9 trillion pesos last month, but that was down 7.6% in real annual terms, suggesting that demand for new borrowing remains weak despite the drop in quoted rates. Guillermo Barbero of First Capital Group said delinquent clients have forced banks to shift away from aggressive sales plans and toward recovering troubled borrowers, while rates still sit well above inflation and wage growth.
Credit quality explains much of the caution. Direct personal loans to individuals had a delinquency rate of 15.9% through May, above the 11.7% rate on credit cards, while mortgage arrears were just 2.1% and secured consumer loans 5.8%, Quantum Finanzas said. LCG said lenders face a choice between broadening lending and pricing for losses, or restricting credit through tighter underwriting. In Argentina’s current environment, it said, even lower rates and better repayment trends are unlikely to trigger a strong rebound in household lending.
For investors, the story is about balance-sheet risk and earnings quality rather than loan growth alone. Banks can protect margins by keeping consumer lending expensive, but that strategy risks suppressing origination and locking in high charge-off expectations. If delinquencies fail to ease, lenders may have to remain conservative on provisioning and underwriting, limiting any near-term recovery in consumer credit and keeping pressure on banks exposed to retail borrowers.
The broader narrative is that Argentina is still trying to move from crisis pricing toward normal credit conditions, but the household side of the market remains far from there. Rates have come down, inflation expectations are lower, and policymakers want a virtuous cycle of repayment and lending. For now, high defaults, expensive effective borrowing costs and cautious banks suggest that cycle has yet to begin.
| Entity | Gains | Losses |
|---|---|---|
| Banks | ▲higher lending margins | ▼weaker loan growth |
| Household borrowers | ▲slightly lower quoted rates | ▼120% effective borrowing cost |
| Central bank | ▲supports credit normalization narrative | ▼faces pressure from delinquency |
| Retail lenders | ▲select borrower repricing power | ▼higher default risk |