Asbis posted a record August as demand tied to artificial intelligence infrastructure kept powering the Warsaw-listed distributor’s sales and pushing its shares to fresh highs.
Asbis August revenue rises 91% on AI demand
The company said preliminary August consolidated revenue rose 91% year on year to $604 million, the strongest August in its history and nearly double the $316 million it generated a year earlier. The update matters because Asbis sits inside the supply chain that is benefiting from the global build-out of AI data centers, and its numbers suggest that spending on servers, components and related infrastructure remains resilient even as some investors worry the cycle may be cooling.
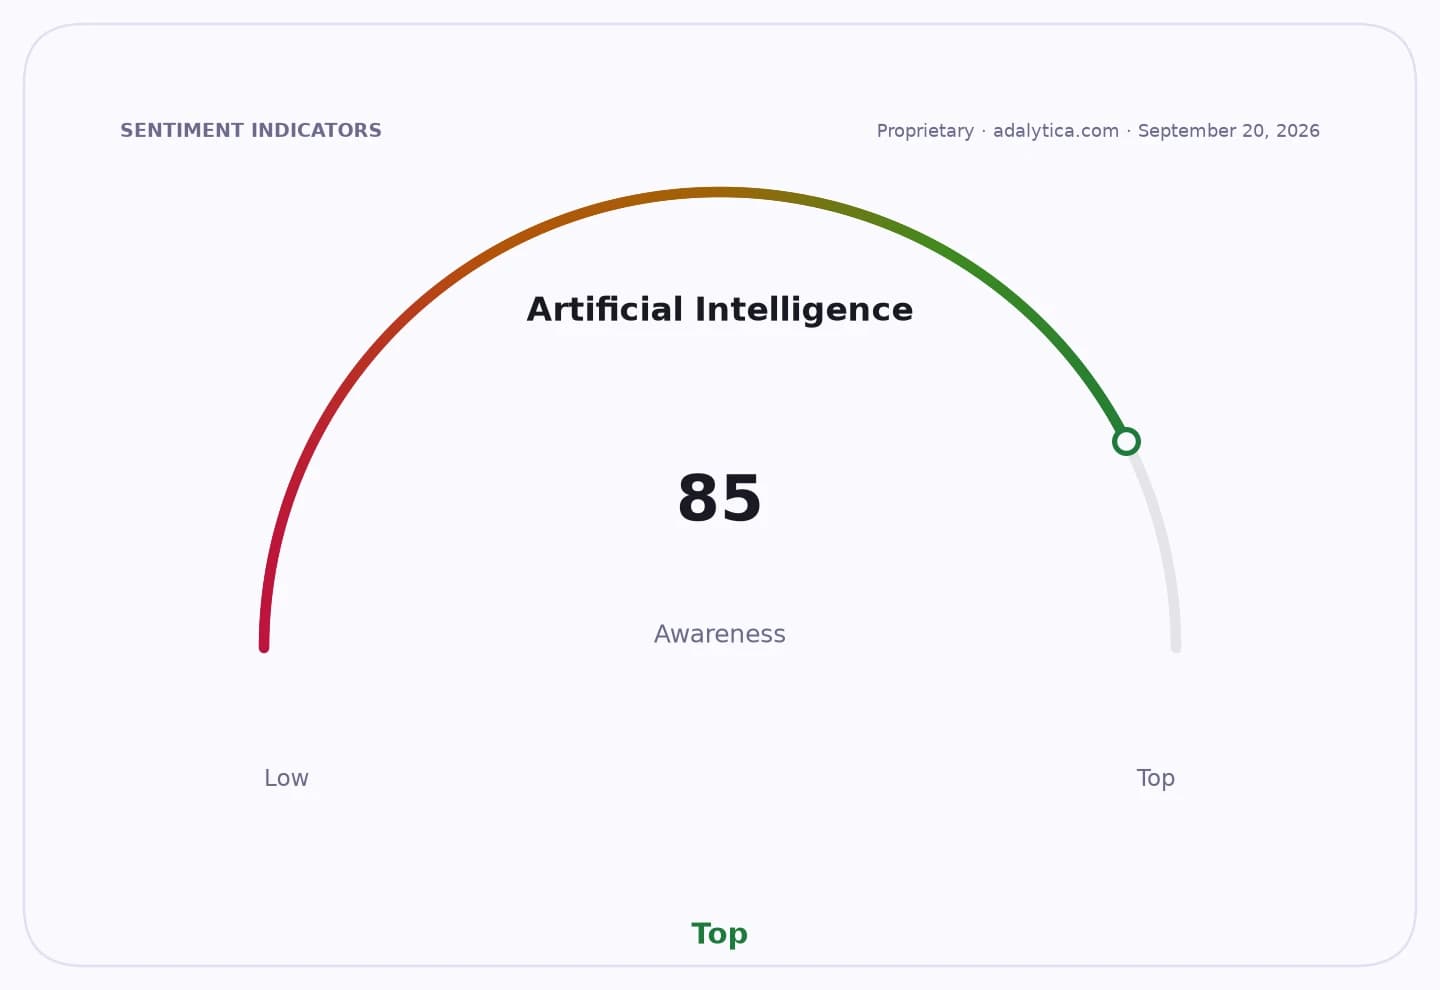
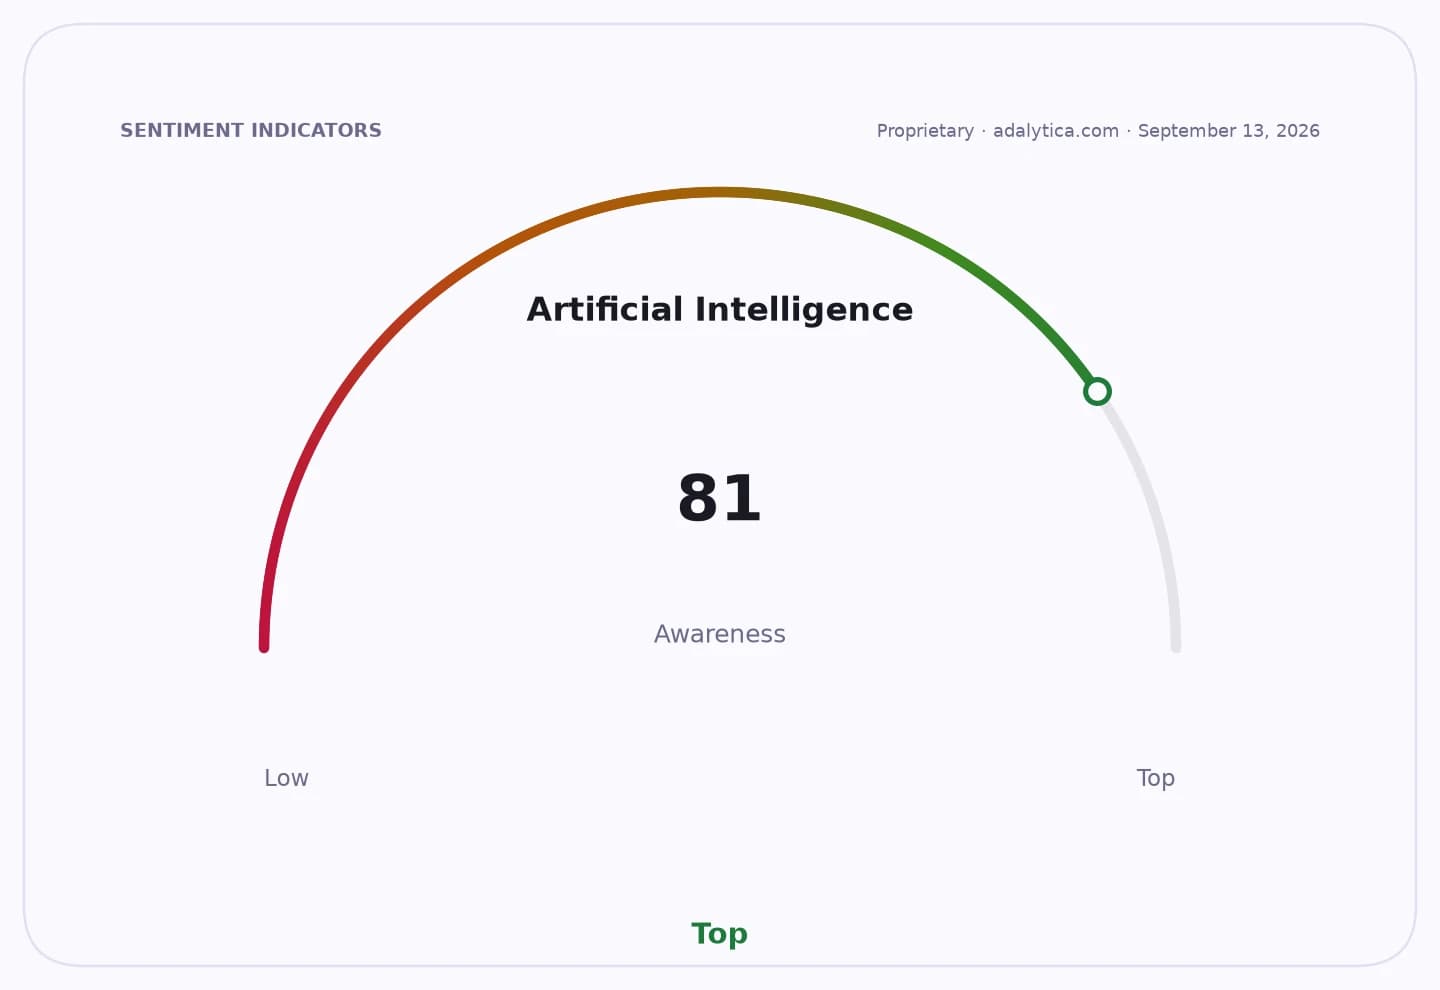
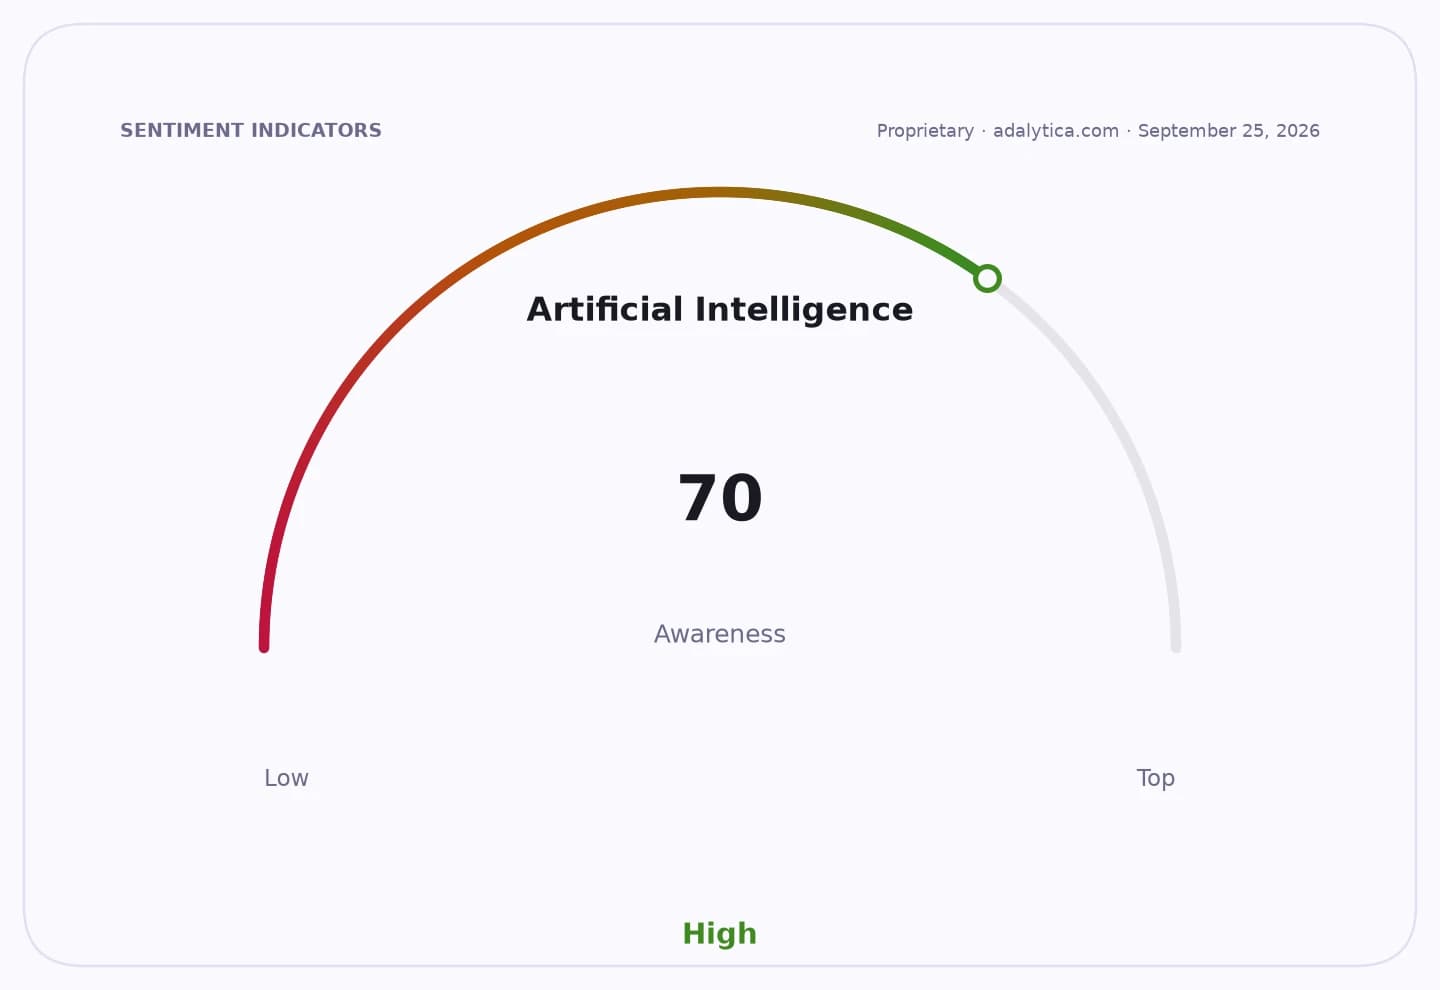
Sentiment IndicatorsⓘProprietary · adalytica.com · September 25, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the immediate message is that one of the market’s most explosive technology names on the Warsaw Stock Exchange still has momentum behind it. Asbis shares have surged more than 440% this year and hit a record 179 zlotys on Monday after the earnings update, lifting the company’s market value to almost 10 billion zlotys. That kind of move implies not just optimism about revenue growth, but a willingness to pay for continued exposure to AI-linked hardware demand.
Chief Executive Sergiej Kostewycz said August’s growth reflected both “very good” AI infrastructure demand and strong consumer sales, including smartphones, the second-best-selling product category in the month. He also pointed to Ukraine, Kazakhstan and the United Arab Emirates as the company’s top monthly markets, underscoring how Asbis’ growth engine is spread across regions and not solely dependent on Western cloud giants.
That mix matters economically because it suggests Asbis is not just a one-theme beneficiary of the AI trade. The company is simultaneously riding server and data-center investment while maintaining its legacy consumer distribution business. That diversification can help cushion margins and demand if one segment softens, though it also means the stock is now pricing in a very strong continuation of current trends.
The broader backdrop remains supportive. Asbis has said its biggest growth driver over the coming years is the expansion of AI data-center infrastructure, which it expects to remain strong for at least the next five years. It also benefits from being the exclusive Apple distributor in 25 EMEA countries, giving it an additional consumer revenue stream at a time when investors are rewarding companies that can show both scale and recurring demand.
The risk for shareholders is that a stock already up more than fourfold this year leaves little room for disappointment. If AI-related capital spending slows, or if consumer electronics demand weakens, the share price could become more vulnerable to any hint that the current pace is unsustainable. For now, though, the August print reinforces the same narrative: AI hardware demand is still translating into real sales, and Asbis remains one of the clearest listed beneficiaries in the region.
| Entity | Gains | Losses |
|---|---|---|
| Asbis | ▲Record revenue growth | ▼Higher expectations |
| Shareholders | ▲AI-driven rerating | ▼Valuation risk |
| AI infrastructure buyers | ▲Supply-chain access | ▼Rising component demand |
| Short sellers | ▲— | ▼Momentum trade keeps squeezing |