Australian shares are set to open little changed as strong earnings from Meta Platforms and Tesla reinforce confidence that the artificial intelligence rally still has room to run, even as investors weigh a hack at Fisher & Paykel and a sharp rise in French bond yields.
ASX set flat as Meta and Tesla lift AI stocks
S&P/ASX 200 futures were up 5 points, or 0.1%, pointing to a flat start after Wall Street’s Nasdaq-led advance, with AI-linked stocks again driving sentiment. The setup matters because the Australian market has become increasingly sensitive to the global technology cycle, even though its index is dominated by banks, miners and resource stocks rather than megacap US software names.
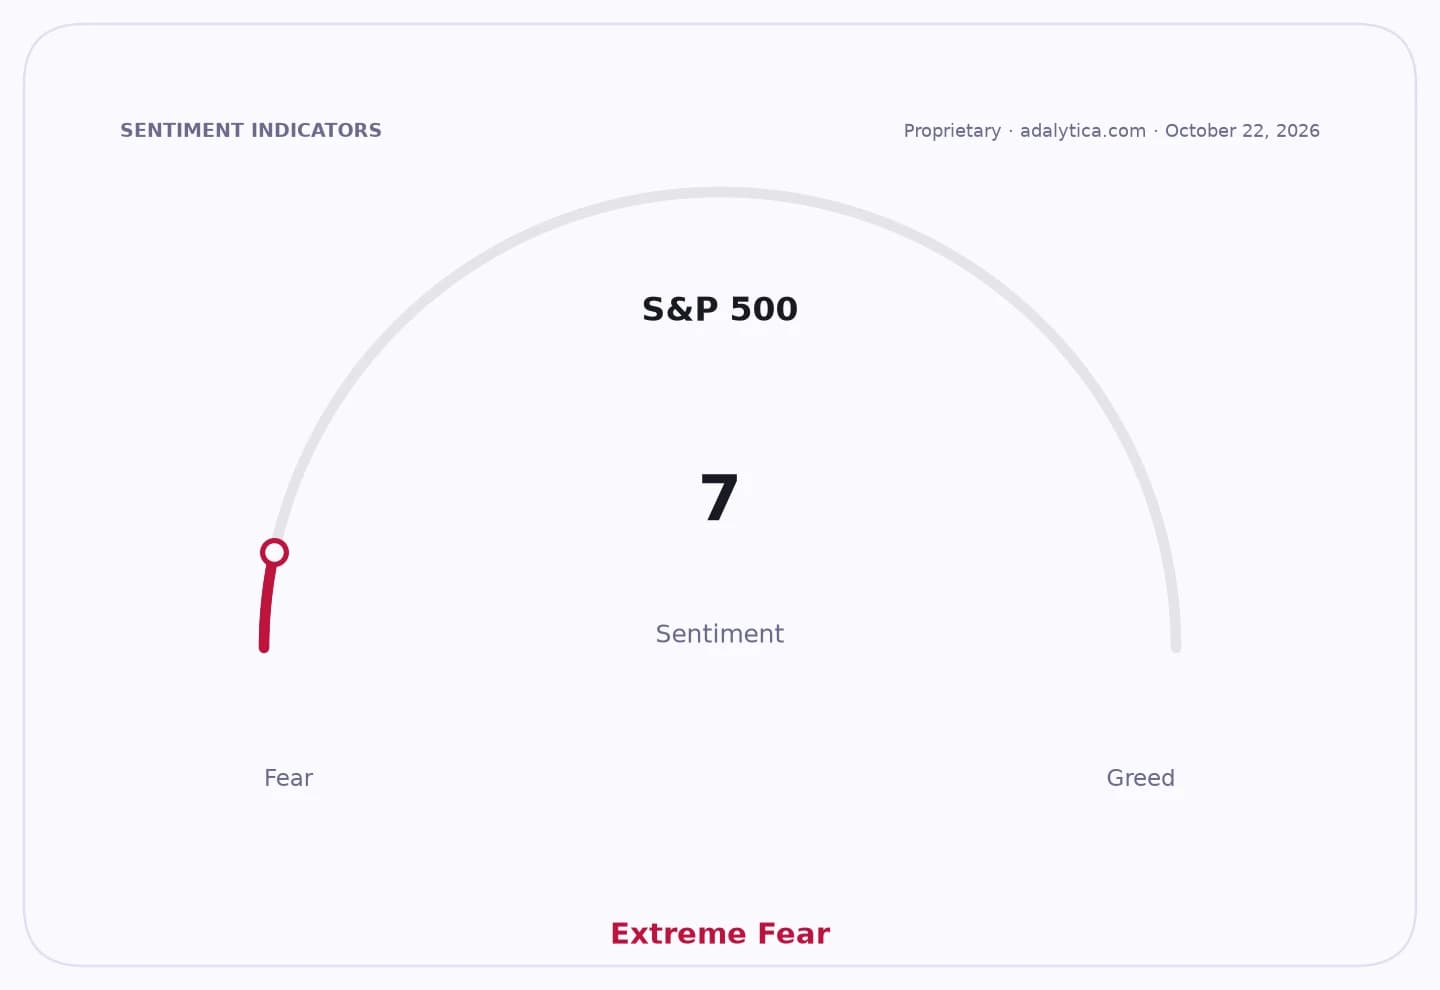
Sentiment IndicatorsⓘProprietary · adalytica.com · October 27, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Meta’s better-than-expected results and Tesla’s beat helped extend a rebound in names tied to AI infrastructure and deployment, including semiconductor, cloud and data-centre suppliers. Shares of Elon Musk’s SpaceX rose almost 10% after he said a merger with Tesla would be “a good idea”, while Tesla gained 3.5% ahead of earnings. For investors, the message is that capital spending on AI has not yet met the market’s ceiling: if the biggest spenders and beneficiaries keep delivering, the trade can justify higher valuations across the supply chain.
That is particularly important after recent weakness in some of the so-called neocloud names, where lenders have grown uneasy that expected data-centre revenue may not materialise. A strong read-through from Meta would ease those concerns by suggesting demand for compute, storage and networking remains robust enough to support the build-out. A disappointment, by contrast, would quickly revive the market’s worry that the AI boom is running ahead of monetisation.
The Australian market’s direct exposure is more limited, but the ripple effects matter. Local tech shares tend to trade with global growth sentiment, and broader risk appetite can also influence miners and other cyclicals through the US dollar, bond yields and equity multiples. Adalytica’s S&P 500 trade signals show extreme fear in sentiment even as awareness of the theme remains at the highest level, a combination that often precedes outsized moves when earnings confirm or challenge the prevailing narrative.
Outside equities, French 10-year yields hitting their highest level since 2002 underscore how quickly sovereign-bond stress can bleed into global markets, especially when investors are already balancing inflation risks against expectations for easier policy. Higher European yields can tighten financial conditions globally, strengthen the dollar and weigh on rate-sensitive assets, adding another cross-current for Australian stocks.
Fisher & Paykel’s reported hack is a separate but relevant reminder that corporate risk has not disappeared even as markets chase AI upside. Cyber incidents can hit operations, margins and customer confidence, and they remain a valuation risk for companies whose earnings depend on smooth supply chains and dependable data systems.
For the ASX, the immediate focus will be whether the overseas lead holds through local trading and whether the market can keep looking through short-term noise. Fortescue’s upcoming report will matter for a different reason: it will help determine whether the resource sector can offset any tech-driven volatility in global risk assets. If AI-heavy earnings continue to surprise on the upside and bond stress remains contained, the path of least resistance for the ASX is a steady-to-firmer open. If either falters, the market’s recent rotation into caution could quickly reassert itself.
| Entity | Gains | Losses |
|---|---|---|
| Meta, Tesla | ▲Stronger AI trade sentiment | ▼Short sellers, valuation skeptics |
| AI suppliers and neoclouds | ▲Better demand backdrop | ▼Lenders, cautious credit investors |
| ASX bulls | ▲Stable offshore lead | ▼Volatility traders |
| French bond buyers | ▲Higher yields | ▼Sovereign borrowers, rate-sensitive assets |