Australia is facing a more expensive and less predictable trading world, and Treasurer Jim Chalmers is trying to steer the country toward deeper capital and supply-chain ties with Japan before that pressure filters further into household prices, business margins and investment flows.
Australia Japan trade ties and miners
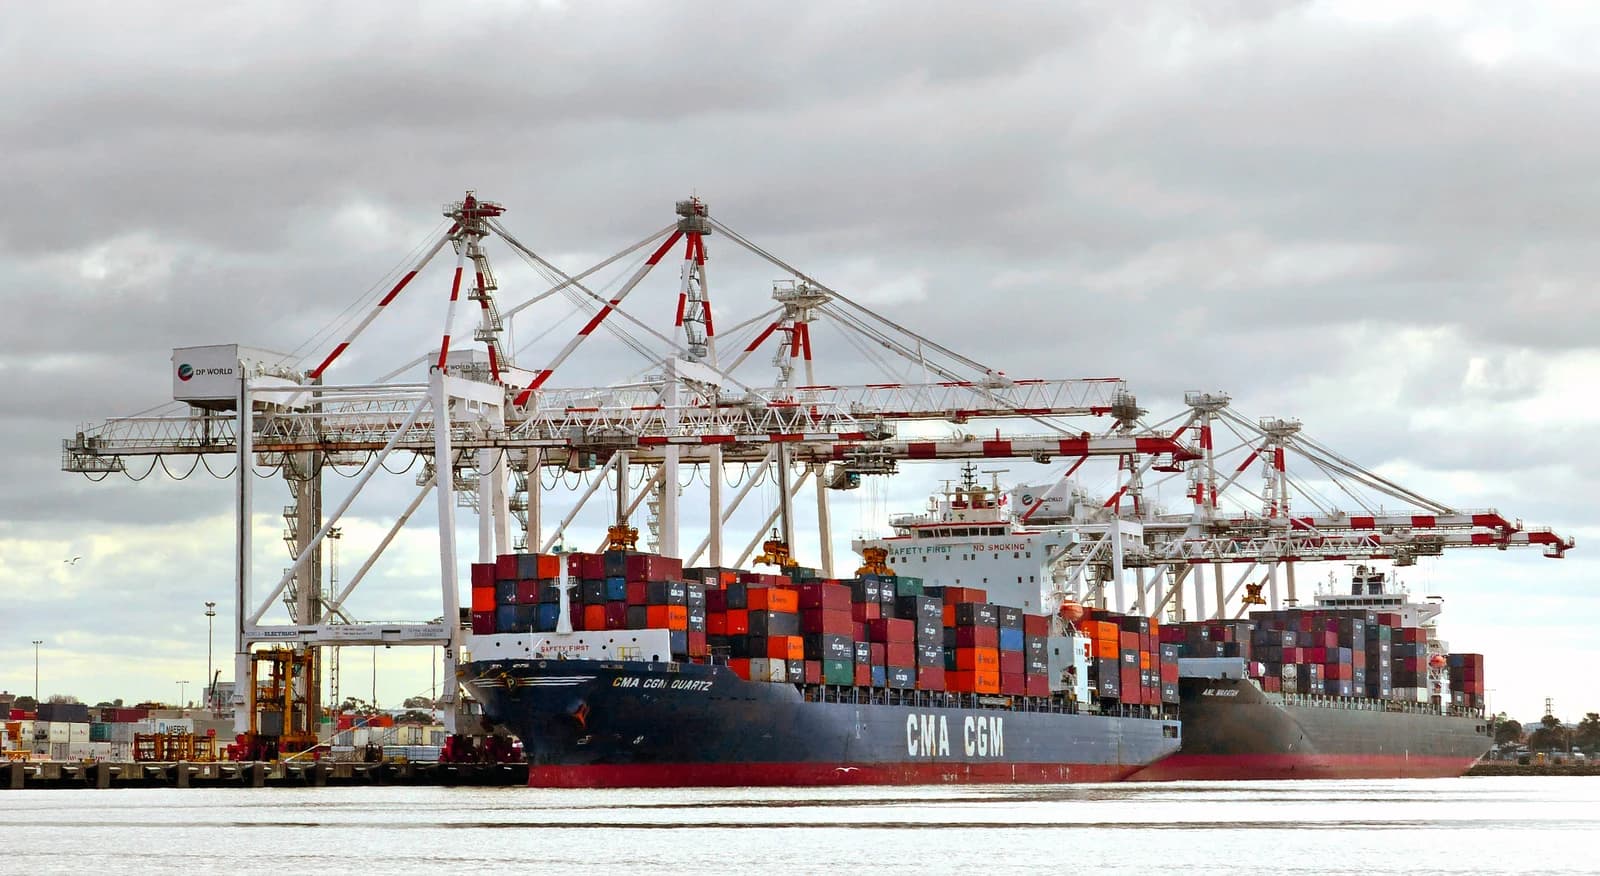
That is the economic meaning of his warning that “fracturing” trade is driving up Australians’ costs. The US has now pushed tariffs to their highest level since the 1940s, a shift that matters far beyond Washington because tariff walls lift input costs, disrupt sourcing and encourage companies to hold more inventory, duplicate suppliers and pass through price increases. For an open economy like Australia, those frictions show up first in imported goods, then in construction, manufacturing and energy-intensive industries, and eventually in broader inflation.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The market backdrop reinforces the message. The Australian dollar has slipped to around 0.70 against the US dollar, with conventional technical indicators showing it below its 50-day moving average and its 200-day moving average, while RSI readings have weakened sharply. A softer currency can cushion exporters, but it also makes imports more expensive at exactly the moment global trade is becoming less reliable. That is a bad combination for consumer purchasing power and a mixed one for policy makers trying to keep inflation under control without choking growth.
For investors, the opportunity is not in pretending trade fragmentation will reverse quickly. It is in positioning for the second-order winners of a world where governments want resilience more than efficiency. Australia’s push to deepen investment ties with Japan points to more cross-border capital in critical minerals, LNG, infrastructure, clean energy supply chains and industrial capacity. That is constructive for companies that own hard assets, logistics networks and strategic resources, and it is especially supportive for miners with export optionality and pricing power.
BHP and Rio Tinto are the clearest liquid proxies for that theme. Both stocks have recently cooled from prior highs, but they remain well above longer-term averages, suggesting the market is still pricing in durable demand for iron ore, copper and other industrial metals even as growth worries and tariff headlines create volatility. BHP’s copper exposure is especially relevant if Australia and Japan move toward deeper industrial cooperation, while Rio’s scale makes it a direct beneficiary of any renewed push to secure non-US, non-China supply chains.
The broader investment case is that fragmentation is not just a macro headline; it is a capital-allocation regime. When trade is more expensive, countries pay up for reliability, allies and domestic capacity. That creates a long runway for Australian miners, energy exporters and infrastructure owners that can sit inside trusted trade networks rather than outside them. The market may still treat tariffs as a temporary negotiation tactic. I believe the bigger shift is structural.
If Chalmers is right, this is the beginning of a multi-year re-pricing of supply chains, currency dynamics and regional investment flows. Investors should lean into the beneficiaries of deglobalisation, not the victims of it, and watch for Japan-linked Australian projects, resource exporters and infrastructure names to capture the next wave of defensive capital.
| Entity | Gains | Losses |
|---|---|---|
| BHP | ▲copper and iron ore demand | ▼global trade efficiency |
| Rio Tinto | ▲resource export leverage | ▼tariff-driven disruption |
| Japan | ▲deeper Australia investment access | ▼reliance on unstable supply chains |
| Australian consumers | ▲none | ▼higher import costs |