The Bank of Nova Scotia is bracing for a one-time earnings hit from Chile’s lower corporate tax rate, a reminder that even as the country’s copper complex surges, policy changes can quickly reshape bank profits and capital allocation across Latin America.
Bank of Nova Scotia Faces Chile Tax Hit
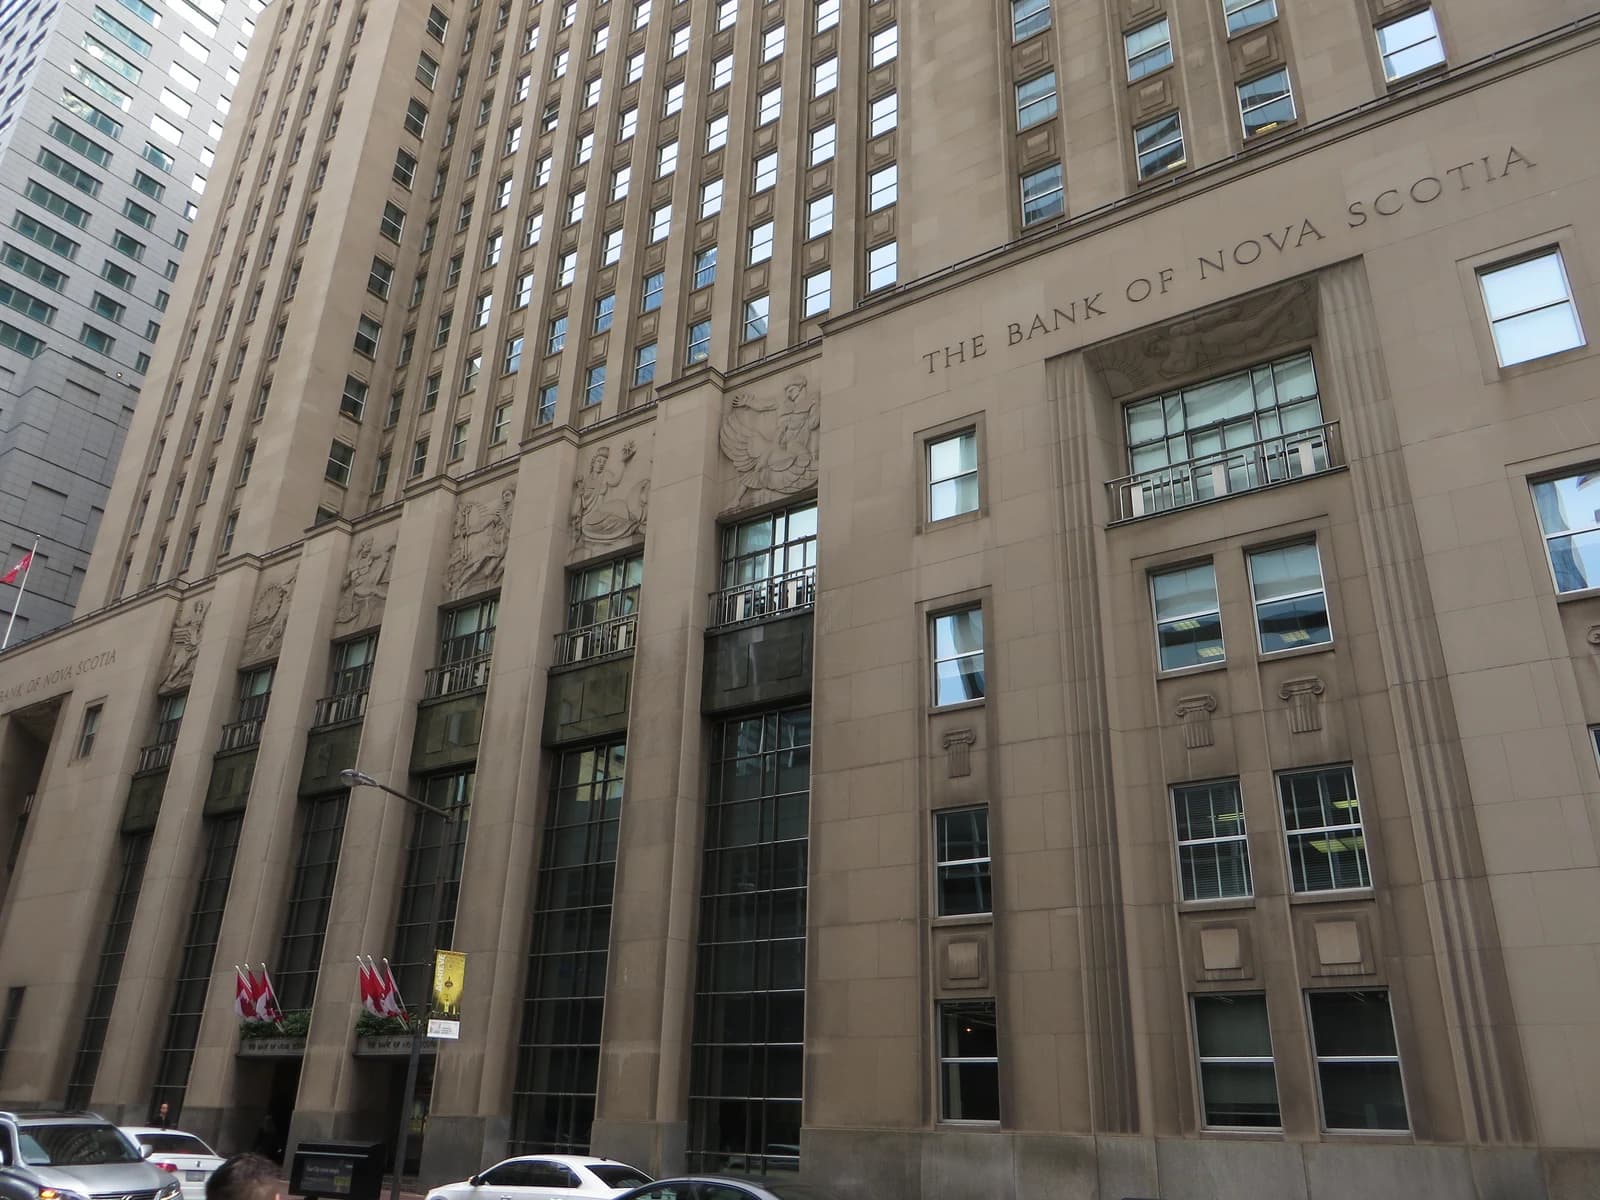
For investors, the immediate question is not the size of the accounting charge but what it says about earnings quality in Scotiabank’s international unit. Chile is one of the Canadian lender’s key offshore markets, and a tax-rate cut can compress reported profits in the near term even if underlying loan demand and deposit growth remain intact. That matters because BNS is trying to prove that its Latin American franchise can deliver steadier returns after years of uneven performance versus its domestic peers.
The timing is especially important. Chilean copper prices have climbed to a two-year high even after production disruptions at major miners, underscoring a stronger macro backdrop for the mining-heavy economy. Yet the Chilean central bank is keeping its benchmark rate at 4.5% for the next two years, signaling a cautious growth and inflation outlook rather than a broad acceleration. That mix leaves banks exposed to a push-pull dynamic: better commodity-linked activity can support credit demand, while tax and policy changes can still blunt reported earnings.
Scotiabank’s share price has already been moving well above its 50-day average, suggesting investors have been rewarding the broader earnings story. But the stock’s recent technical stretch also makes any foreign-tax-related hit more sensitive, because expectations are elevated. A one-time charge should not be confused with a structural problem, yet it can briefly interrupt the market’s willingness to pay up for the bank’s improving momentum.
The bigger investment narrative is that Chile remains an attractive operating market even when its policy regime shifts. Strong copper prices, potential lithium investment and a relatively open economy still support the long-term case for financial institutions with local scale. The near-term losers are shareholders looking for smooth earnings comparisons; the longer-term winners are banks that can absorb tax noise while continuing to compound in a commodity-linked market.
For now, the key takeaway is simple: the Chile tax cut may dent Scotiabank’s reported earnings once, but it does not change the strategic value of its Latin American franchise. Investors should watch for whether management treats the hit as a clean accounting event or whether it coincides with broader pressure on margins, asset quality or capital returns. That will determine whether the market buys the dip or keeps paying for the region’s growth story.
| Entity | Gains | Losses |
|---|---|---|
| Chilean government | ▲simpler tax regime | ▼near-term fiscal revenue |
| Bank of Nova Scotia | ▲long-term Chile franchise value | ▼one-time reported earnings |
| Copper-linked Chile economy | ▲stronger activity backdrop | ▼policy uncertainty |
| BNS shareholders | ▲potential long-run compounding | ▼near-term EPS hit |