Barrick Mining shares climbed in premarket trading after the gold producer beat earnings expectations for the quarter, giving investors another reminder that profits can outrun revenue even when top-line growth comes in a touch light.
Barrick Mining Beats Earnings, Revenue Misses
The company reported adjusted earnings of 82 cents a share, ahead of the 79-cent consensus, while revenue rose to $5.07 billion, slightly below the $5.13 billion analysts expected. The mixed print was enough to lift the stock 2.5% to $41.57 before the opening bell, a sign that the market is still willing to pay for operational discipline in a sector where cash flow matters more than headline sales.
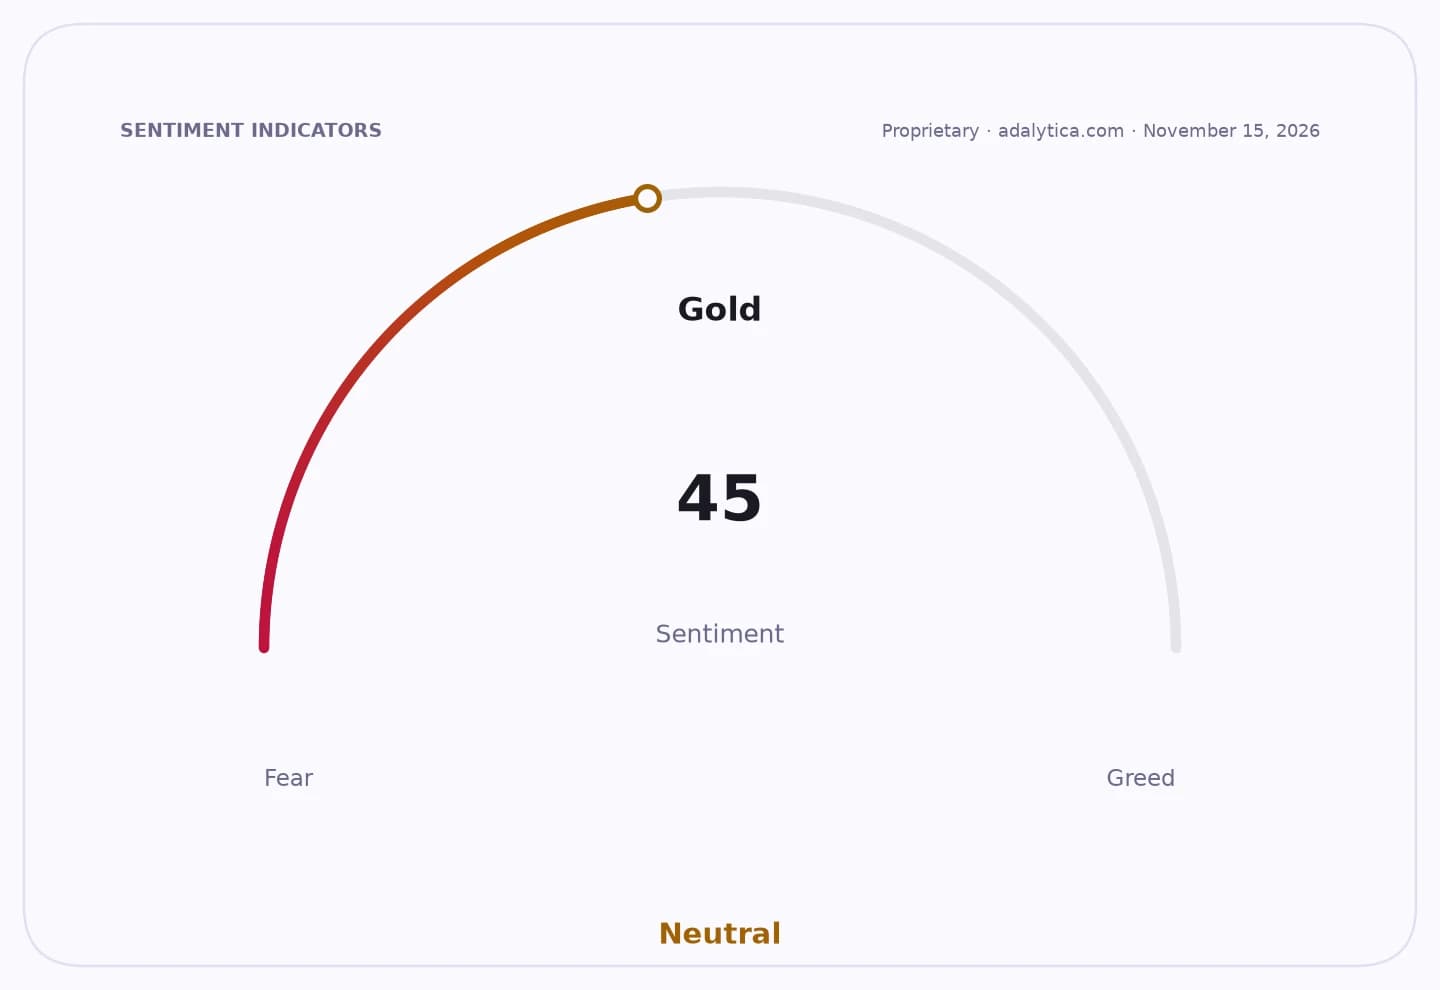
Sentiment Indicators
For gold investors, the bigger story is not the modest revenue shortfall. It is that Barrick continues to convert a supportive metals backdrop into better-than-expected bottom-line results. That is exactly the kind of operating leverage the market wants from senior miners: stable production, tighter cost control and enough pricing power to protect margins when gold prices fluctuate.
The reaction also matters because Barrick has spent much of the year trading like a leveraged bet on bullion rather than a quality cash generator. A profit beat helps reframe the stock as something more durable — a large-cap miner with enough scale to benefit from higher gold prices without needing a perfect quarter to deliver upside. With the shares still around $41.57 in premarket trade, the market is signaling that earnings resilience remains the more important driver than a minor sales miss.
That dynamic puts Barrick in a favorable position relative to peers and to the broader precious-metals trade. Gold miners have benefited from macro uncertainty, central-bank buying and ongoing demand for hard-asset exposure, but the winners are increasingly being sorted by execution. Investors are rewarding names that can turn metal prices into free cash flow rather than just production growth.
The next catalyst is whether Barrick can show that this quarter was not a one-off but part of a sustained margin story. If gold holds firm and costs stay contained, the stock has room to extend its move as investors rotate toward miners with balance-sheet strength and visible earnings power.
For now, the message is clear: in a volatile gold market, Barrick is being bought for profits, not for perfection.
| Entity | Gains | Losses |
|---|---|---|
| Barrick Mining | ▲Profit beat, stronger sentiment | ▼Revenue miss, higher scrutiny |
| Gold investors | ▲Better earnings leverage | ▼Less room for operational disappointment |
| Senior gold miners | ▲Sector validation | ▼Revenue-sensitive laggards |
| Short sellers | ▲Risk of squeeze | ▼Weak thesis if margins hold |