Belgium’s credit rating affirmation by Fitch keeps the country’s sovereign borrowing costs anchored for now, but the agency’s warning on high debt levels underscores a broader European risk: governments with limited fiscal room are entering a period of slower growth, sticky rates and heavier refinancing needs.
Belgium Rating Affirmed as Debt Risks Stay High
That matters because sovereign ratings feed directly into financing costs, investor demand and the pace at which governments can respond to an economic slowdown. For Belgium, the issue is not an imminent downgrade so much as a reminder that elevated debt ratios can become more expensive to carry when benchmark yields stay near multi-year highs.
Sentiment Indicators
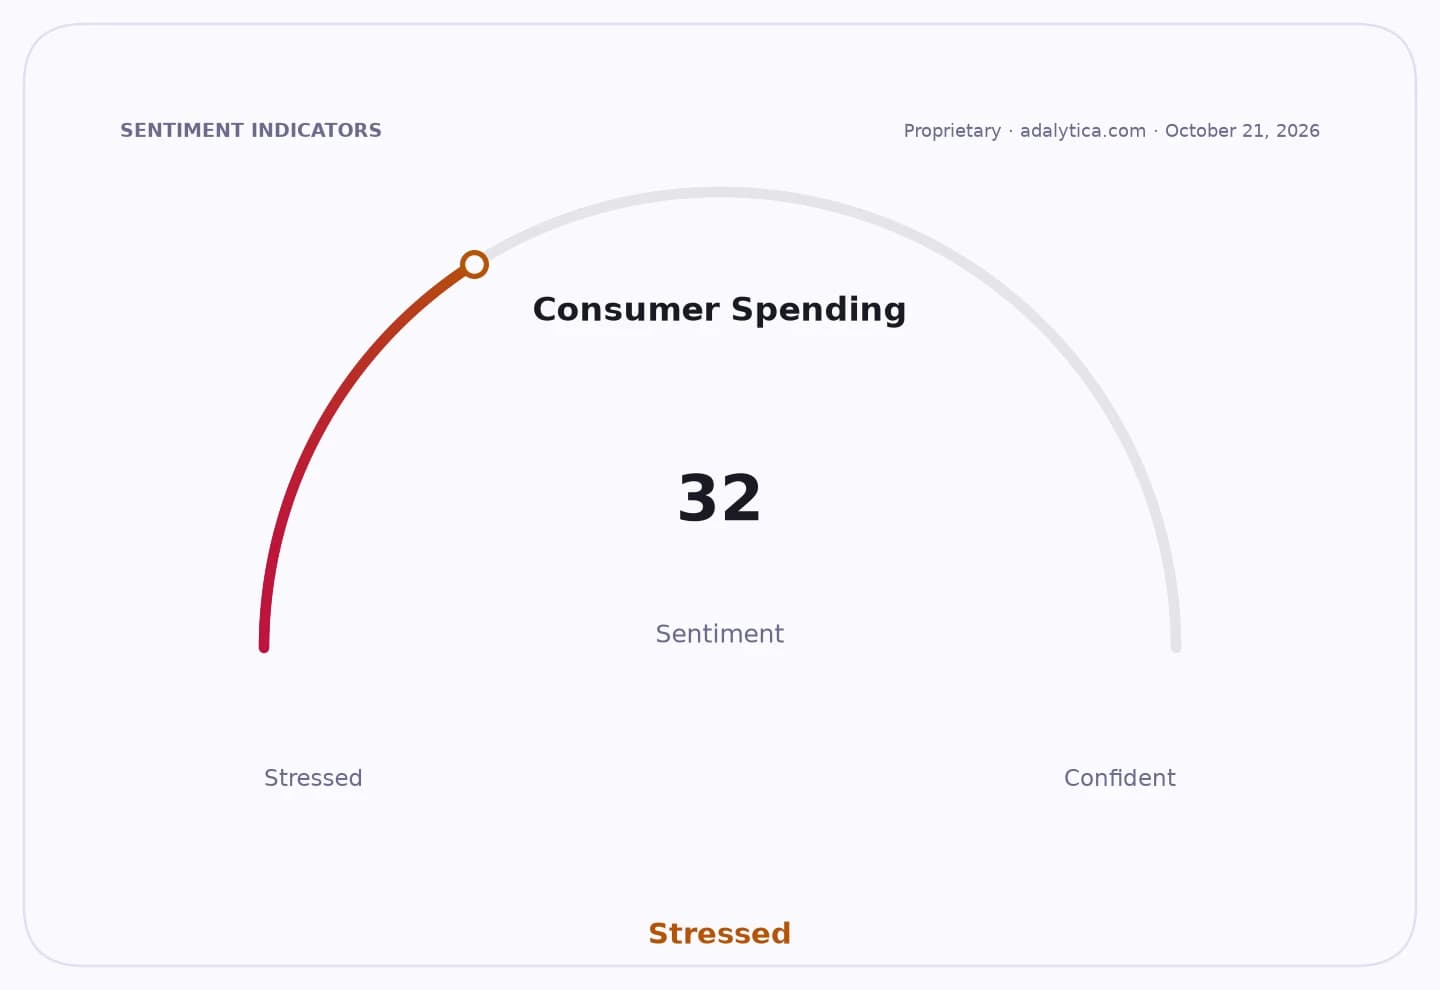
The backdrop is not helping. The US 10-year Treasury yield is hovering around 5.015%, while the two-year is at 4.733%, levels that keep global borrowing costs elevated and leave little room for complacency in bond markets. Belgium’s warning lands alongside wider European anxiety over public debt, with Germany and France also under pressure to show credible fiscal discipline. Adalytica’s EU Fiscal Debt Rules Sentiment gauge shows “Extreme Greed,” a sign of heightened attention to the policy and market implications of sovereign debt management rather than calm confidence.
For investors, the message is twofold. On one hand, the affirmation reduces the immediate risk of forced selling or a rapid repricing in Belgian debt. On the other, the warning suggests ratings agencies are prepared to react if deficit reduction stalls, growth disappoints or funding costs stay elevated. That keeps attention on Belgium’s budget path, euro-zone fiscal rules and the European Central Bank’s ability to prevent sovereign stress from widening across the bloc.
Market signals remain mixed. The euro has been under pressure, with Adalytica’s Euro Trade Signals gauge in “Fear,” and the FXB fund, which rises when the euro weakens against the dollar, has slipped to 125.89 from 129.11 earlier in the month. EUO, which benefits when the euro falls, has strengthened to 33.87, reflecting a market still willing to hedge against further euro-area fiscal and growth risks.
The bull case for Belgium is that a ratings affirmation preserves market access and buys time to narrow deficits without a sudden credibility shock. The bear case is that high debt, slower growth and still-firm global yields leave the country vulnerable if investors become less tolerant of fiscal slippage. The broader narrative is that Belgium’s rating review is not an isolated event but part of a widening test for Europe’s sovereign borrowers: whether they can stabilize debt loads before bond markets do it for them.
| Entity | Gains | Losses |
|---|---|---|
| Belgium government | ▲Keeps rating for now | ▼Faces debt scrutiny |
| Bond investors | ▲Short-term clarity | ▼Risk of future repricing |
| Euro bears | ▲Euro-area debt worries | ▼Stronger fiscal discipline |
| EU fiscal hawks | ▲Pressure for deficit cuts | ▼Governments seeking flexibility |