Berkshire Hathaway is adding to Lennar even after the homebuilder’s shares fell more than 32% over the past year, a fresh sign that Warren Buffett’s conglomerate — now led by Greg Abel — is willing to back a battered housing name on the view that today’s weak demand and higher mortgage rates are already reflected in the price.
Berkshire Adds to Lennar Stake After Selloff
The purchase matters because it goes beyond a simple dip buy. Berkshire has lifted its Lennar stake to almost 10%, or about 23.7 million Class A shares plus roughly 528,000 Class B shares, valuing the position at about $1.8 billion. Buying a cyclical housing stock at a time when the industry is under pressure tells investors Berkshire sees a margin of safety in the valuation and a longer-run recovery in U.S. housing, even if the near-term data remain soft.
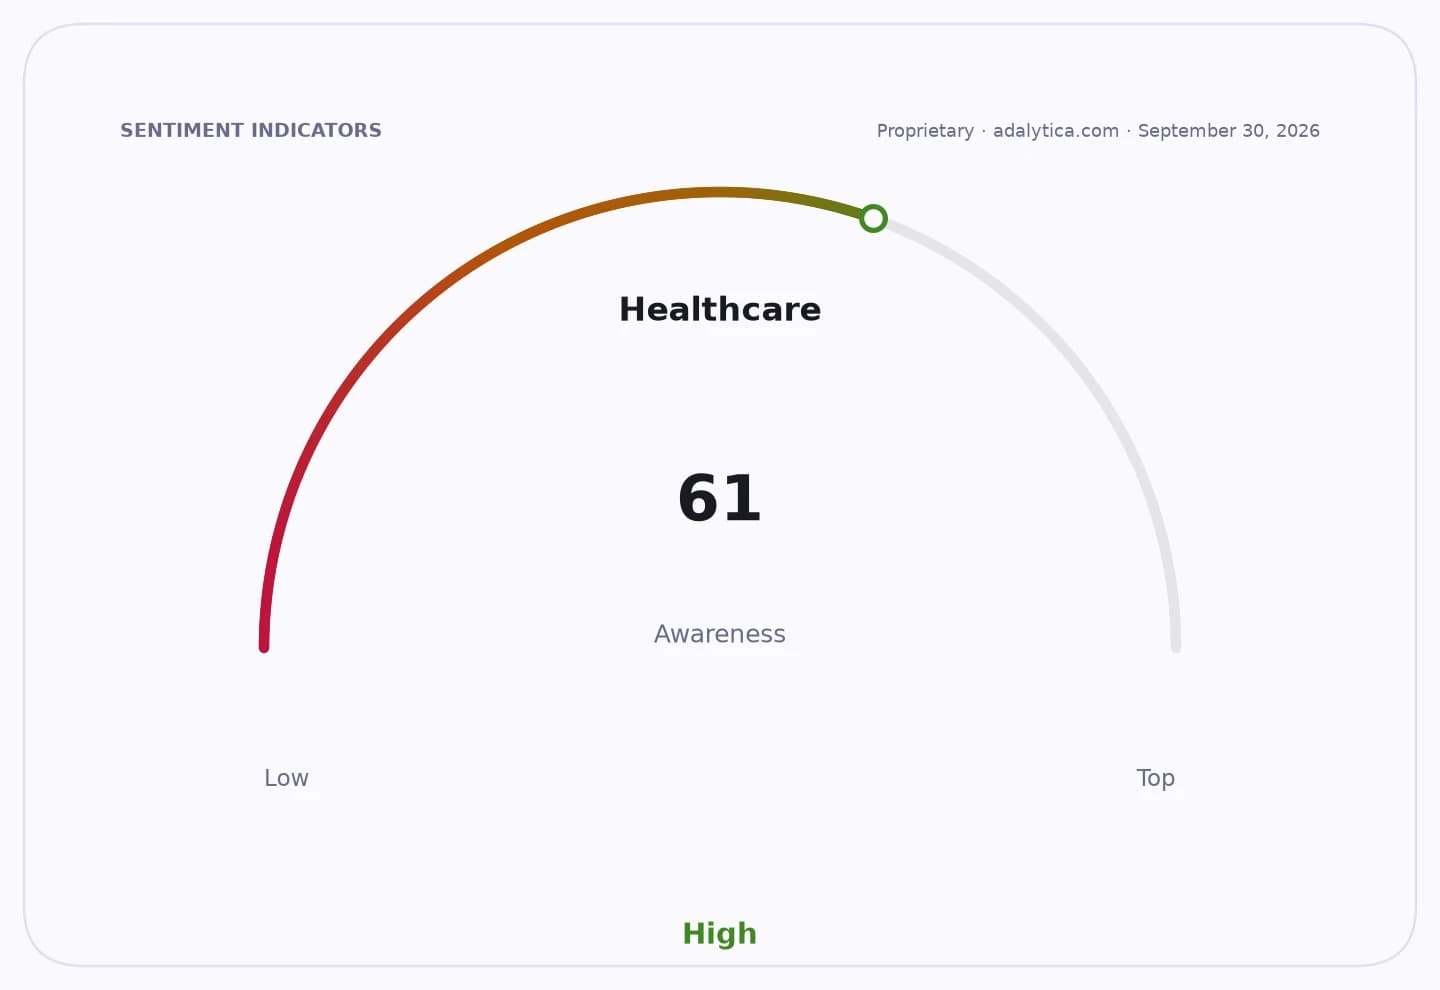
Sentiment IndicatorsⓘProprietary · adalytica.com · September 29, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Lennar’s fundamentals explain why the market had punished the stock. The average 30-year mortgage rate, at 6.95%, remains high enough to delay purchases and keep affordability stretched, and Lennar has already felt the impact in its latest results. Revenue in the fiscal third quarter fell to $8.05 billion from $8.81 billion a year earlier, adjusted earnings per share missed forecasts at $1.23 versus $1.29 expected, and the company cut its full-year home delivery outlook to 80,000-81,000 from 82,000-83,000.
That deterioration makes Berkshire’s move more than a vote of confidence; it is a bet that the cycle eventually turns before the market fully prices it in. CFRA analyst Catherine Seifert framed it as a classic value-style purchase of a name that has become more attractive after the selloff. The immediate market response supported that view, with Lennar shares jumping 6.6% on Tuesday to $83.24.
The trade also fits Berkshire’s broader exposure to U.S. housing and building-related businesses. The conglomerate already owns Clayton Homes, Benjamin Moore and Johns Manville, and has deepened its footprint in the sector through Taylor Morrison. Lennar therefore looks less like an isolated bargain and more like a strategic extension of a long-running theme: owning assets tied to the housing cycle and the materials, financing and renovation chain around it.
For investors, the key question is whether Berkshire is early or simply patient. Bulls will argue that mortgage rates eventually ease and that Lennar’s lower valuation already discounts the slowdown. Bears will point to persistent affordability pressures, weaker orders and the risk that higher-for-longer borrowing costs keep new-home demand subdued. The next catalyst will be whether mortgage rates retreat enough to stabilize traffic and margins, or whether the housing downturn lasts long enough to challenge even Berkshire’s long-term conviction.
| Entity | Gains | Losses |
|---|---|---|
| Berkshire Hathaway | ▲Lower entry price | ▼Near-term housing risk |
| Lennar | ▲Validation from Buffett-era capital | ▼Pressure from weak demand |
| Homebuyers | ▲Potentially lower prices later | ▼High mortgage costs now |
| Housing rivals | ▲Sector rerating if cycle turns | ▼More competition for capital |