Welltower jumped on Thursday after JPMorgan upgraded the healthcare REIT to overweight, a call that reinforces one of the market’s clearest secular trades: aging demographics and senior-housing demand are still outrunning the broader REIT market.
Welltower Rises on JPMorgan Upgrade to Overweight
The stock rose 1.6%, beating a flat S&P 500, after JPMorgan’s Michael Mueller lifted his rating from neutral and set a $260 price target, about 11% above where the shares closed. That matters because Welltower is no longer being valued like a sleepy income vehicle; it is increasingly being treated as a growth asset inside a rate-sensitive sector that has struggled to win back investor confidence.
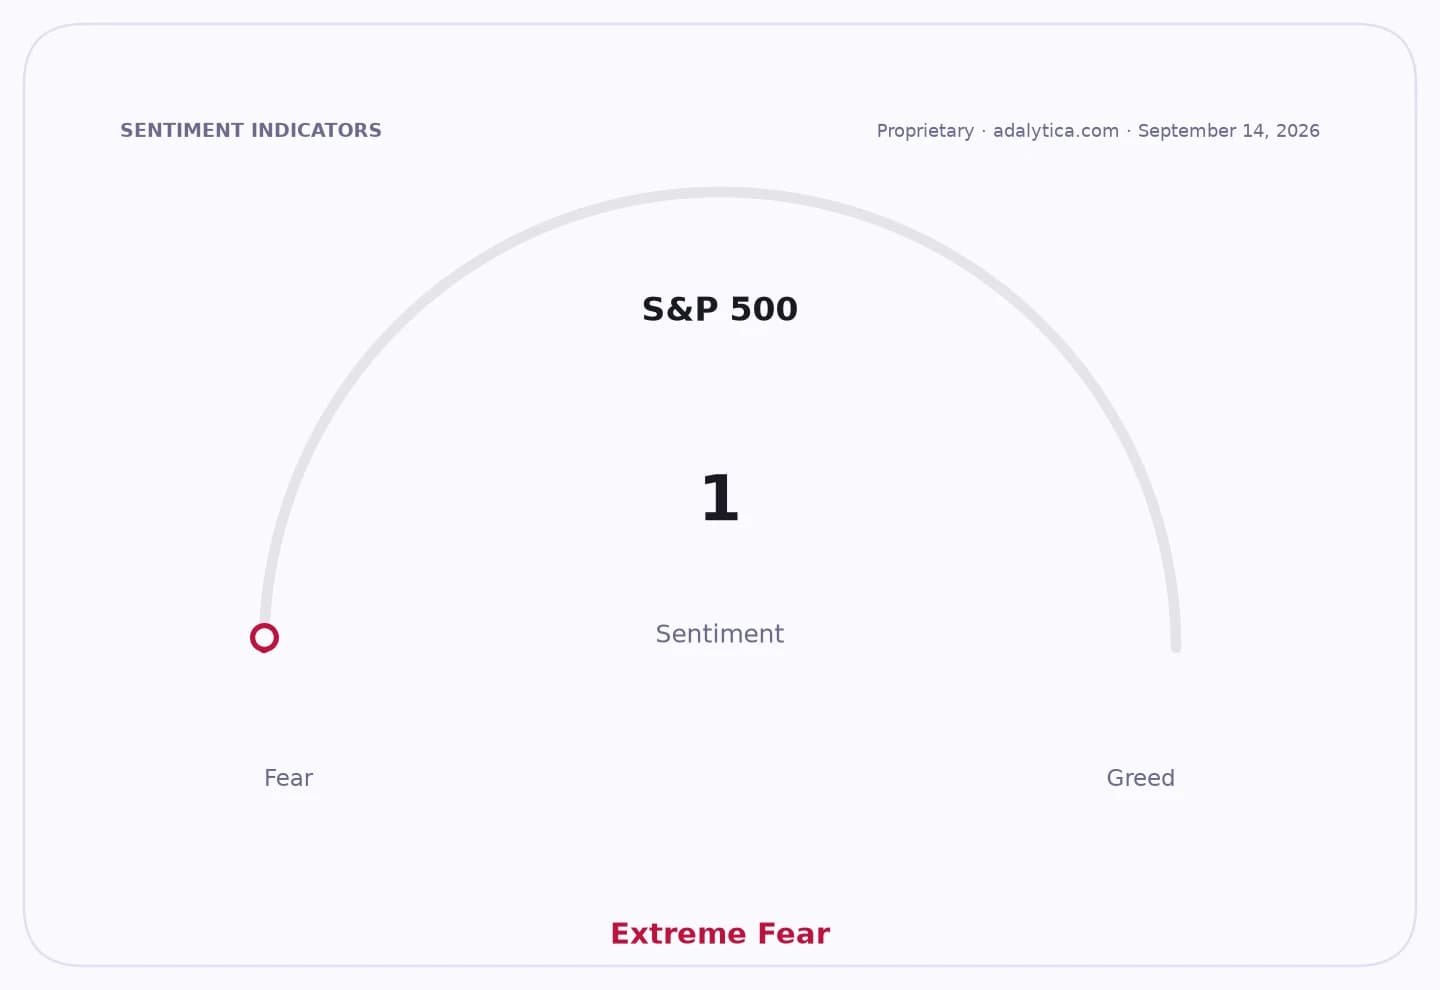
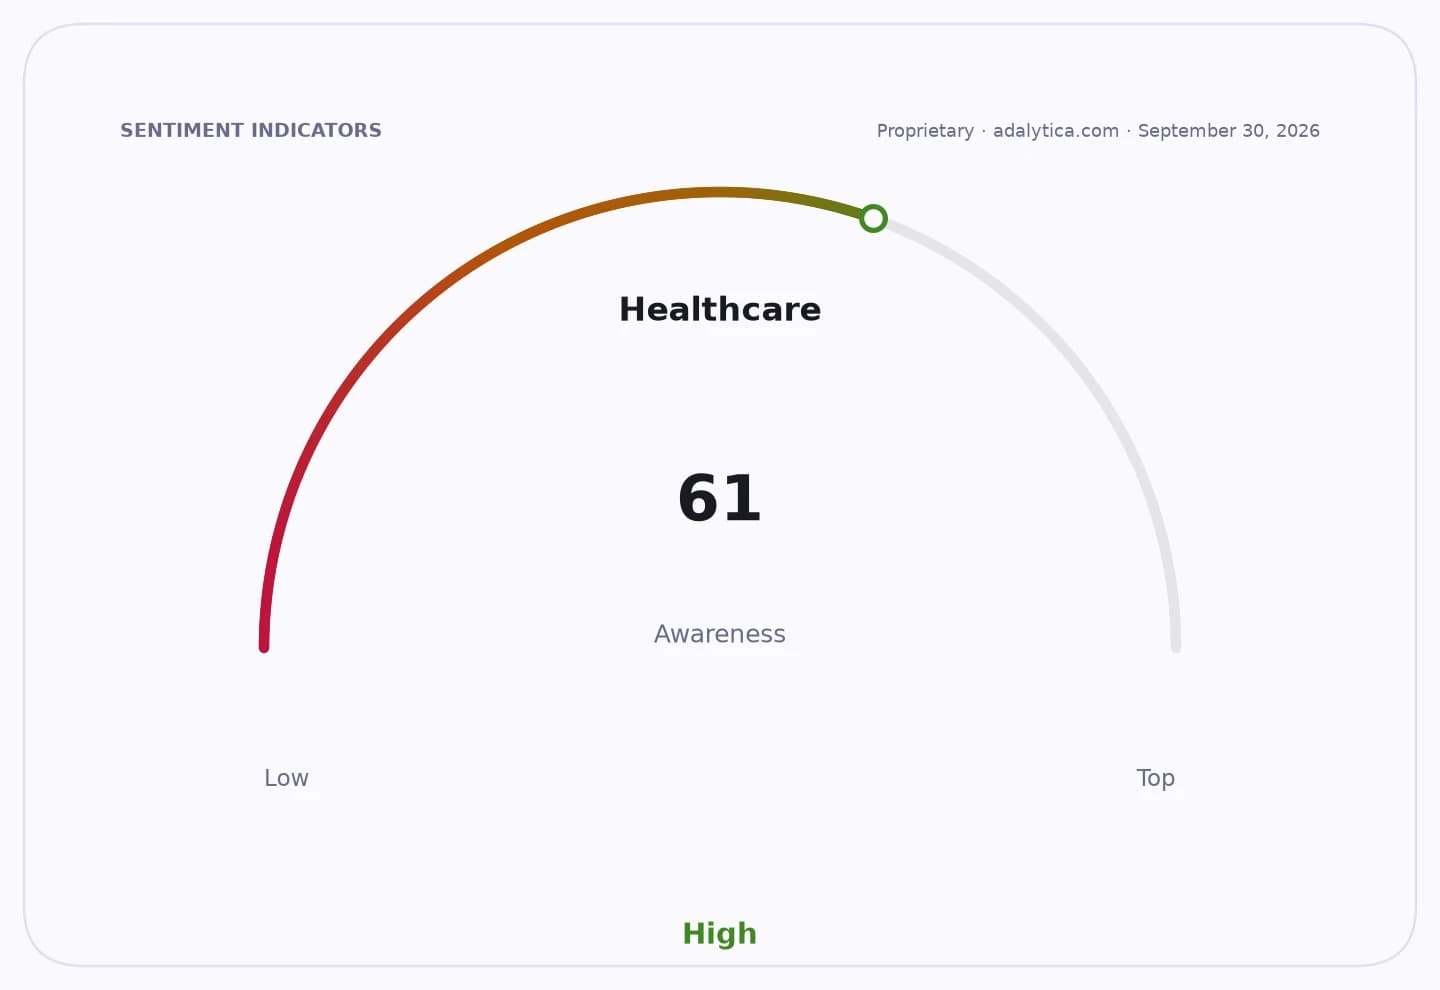
Sentiment IndicatorsⓘProprietary · adalytica.com · September 30, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The upgrade also lands at a useful moment for REIT investors. Higher rates have pressured property valuations across the sector, pushing capital toward operators that can still deliver real internal growth rather than rely on leverage or asset sales. Welltower stands out because it has been posting strong net operating income growth, and JPMorgan argued that the company can sustain above-average gains for years.
That growth story is rooted in senior housing, where Welltower has built an effective operating niche. The investment case is straightforward: the U.S. population is aging, occupancy and pricing power can improve with demand, and healthcare real estate tied to that trend has more durable tailwinds than conventional office or retail property. In other words, this is not just a rate call — it is a demographic call with cash-flow implications.
The catch is valuation. Welltower’s rising popularity has compressed its dividend yield to about 1.5%, far below the richer payouts investors can still find in much of the REIT universe. That helps explain why the stock can keep outperforming while still not appealing to every income buyer. The market is paying up for quality, growth and resilience, not for yield.
For investors, that creates a clear split. If you want maximum current income, Welltower is not the best fit. But if you want exposure to one of the most durable secular themes in real estate — healthcare demand tied to aging America — JPMorgan’s upgrade underscores why the stock can keep compounding even if the broader REIT sector remains under pressure.
The setup favors continued outperformance as long as operating results stay strong and rates do not move sharply higher from here. In a market still hunting for durable growth outside Big Tech, Welltower remains one of the cleaner ways to own the senior-housing inflection point.
| Entity | Gains | Losses |
|---|---|---|
| Welltower | ▲Higher valuation multiple | ▼Income-focused buyers |
| JPMorgan upgrade call | ▲Credibility from stock pickers | ▼Neutral-rated peers |
| Senior housing sector | ▲More investor attention | ▼Traditional REITs with weak growth |
| S&P 500 / broader market | ▲Little direct impact | ▼None meaningful |