Besi shares fell after a report said ASML is working on a competing hybrid bonding product, raising the prospect that one of the semiconductor equipment industry’s most important chip-assembly niches could become more crowded just as advanced packaging demand accelerates.
Besi Falls on ASML Hybrid Bonding Rival Report
The move matters because hybrid bonding sits at the heart of next-generation logic and memory integration, especially for artificial intelligence chips that need more bandwidth, denser interconnects and lower power consumption. If ASML, already the dominant supplier of lithography tools, brings a credible rival into the market, it could pressure pricing, elongate Besi’s path to share gains and reshape who captures the economics of advanced packaging.
Besi is especially exposed because hybrid bonding is one of the company’s strategic growth areas. The stock reaction suggests investors are reassessing not only the size of the addressable market but also how durable Besi’s technology edge may be if ASML leverages its scale, customer relationships and balance-sheet strength to push deeper into packaging equipment.
The broader backdrop is constructive for the sector. ASML’s own recent results show the cycle is not under strain: it reported €11.7 billion in third-quarter sales and €5.0 billion in net income, while guiding full-year 2026 sales to €44 billion-€45 billion with gross margin around 56%. That gives it both the resources and the strategic flexibility to expand beyond lithography into adjacent process steps if it sees a large enough opportunity.
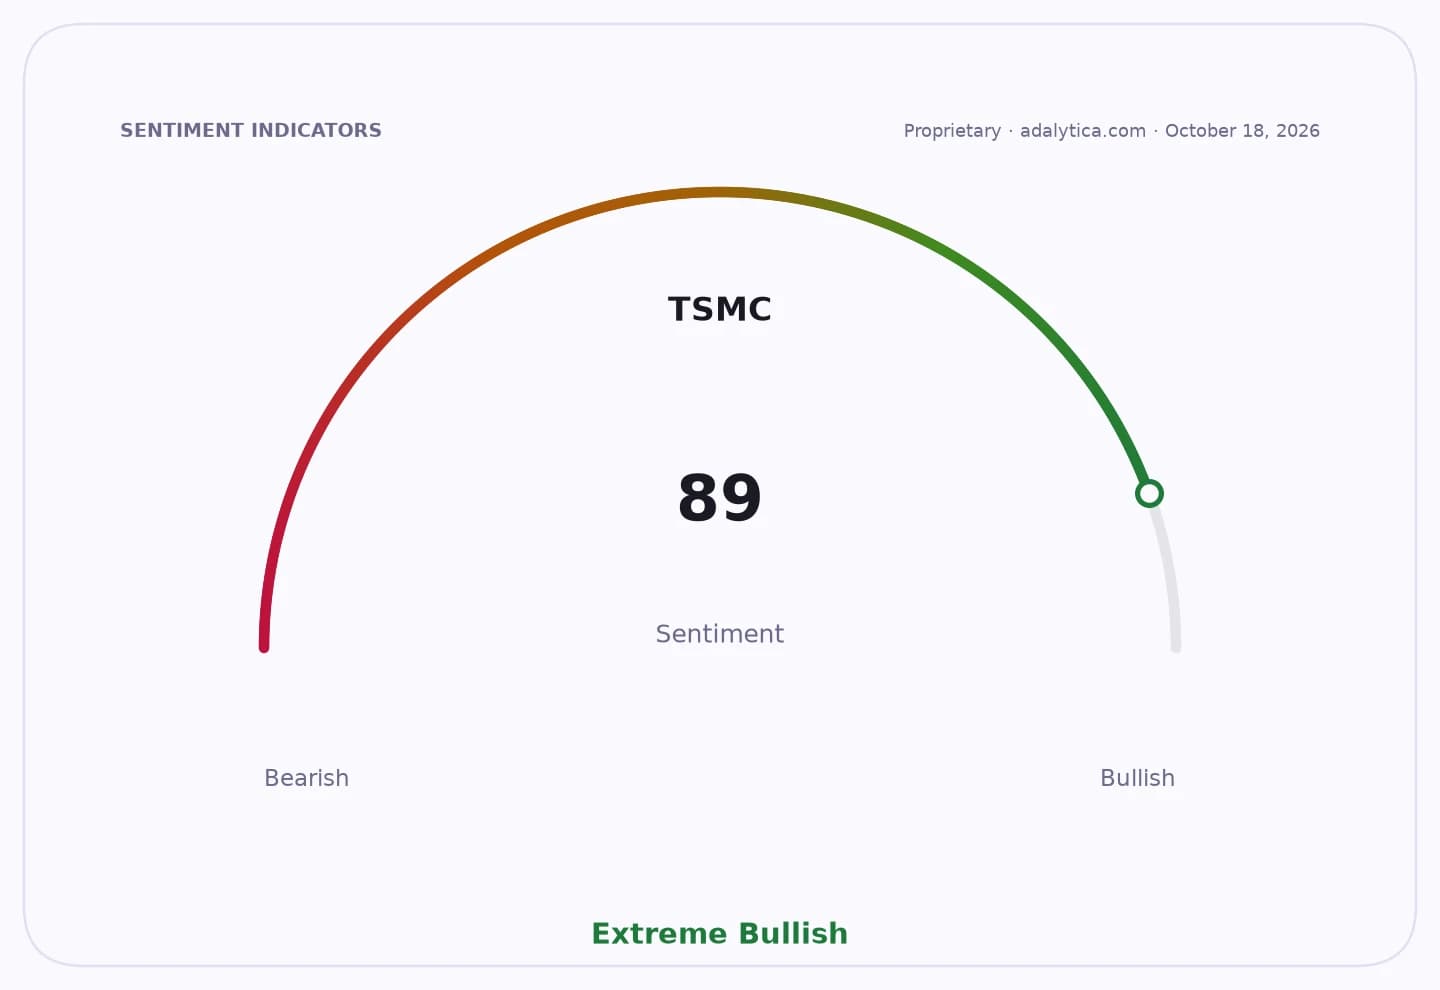
For investors, the issue is less whether hybrid bonding demand exists than who monetises it. A second strong supplier could be positive for chipmakers if it improves tool availability and prevents bottlenecks, but it is a clear negative for Besi if customers start to view the technology as less proprietary and more price competitive. The stock’s drop also comes against a technically weaker backdrop for ASML itself, with the shares recently trading below the 50-day moving average and momentum indicators softening, a sign the market is already more cautious on semiconductor capital equipment.
What to watch next is whether ASML’s product effort remains exploratory or turns into a commercial push, and whether Besi responds with customer commitments, product differentiation or pricing discipline. If the report proves accurate, the key investment question will be whether hybrid bonding becomes a two-player market or the start of a wider fight for control of advanced packaging.
| Entity | Gains | Losses |
|---|---|---|
| ASML | ▲Adjacent growth option | ▼Near-term execution risk |
| Besi | ▲Existing installed base | ▼Pricing power |
| Chipmakers | ▲More tool supply | ▼Less supplier scarcity |
| Investors in packaging peers | ▲Sector validation | ▼Narrower margins |