Brazil’s fiscal rule is already running into the political reality it was meant to restrain, and that is the most important development for investors watching the country’s budget path, the real and Brazilian assets.
Brazil fiscal rule faces budget pressure
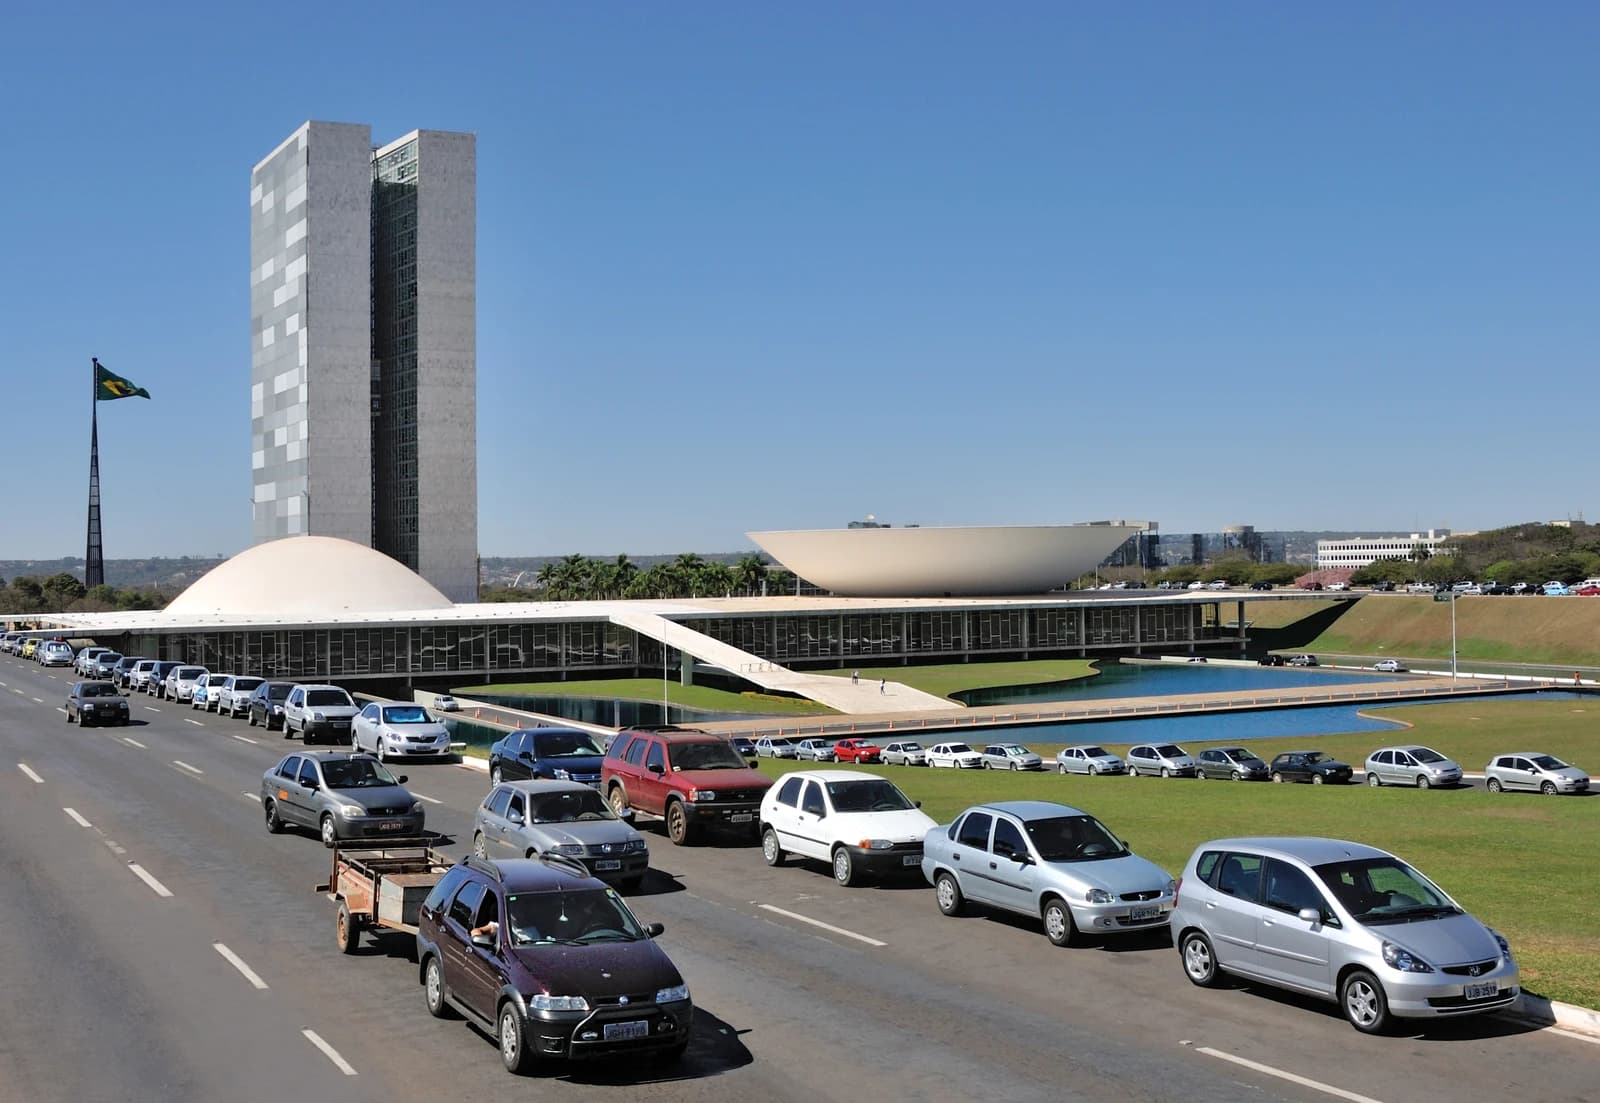
Congress is poised to approve a second supplemental budget for 2026 that would suspend the law’s cap on spending growth through year-end, after the government argued that higher global fuel prices force it to spend more on subsidies to shield consumers. The message is clear: when inflationary pressure meets political pressure, the rule bends. That matters because the Fiscal Responsibility Law was designed to keep primary spending growth to three percentage points above expected inflation and bring general government debt below 40% of GDP by 2035. If Brasília is already reaching for exemptions, the market has to reprice the odds that the debt target will be pushed back, or abandoned in practice.
Economically, the issue is not one temporary subsidy bill. It is the credibility of the spending framework itself. The law was supposed to protect long-term growth by forcing discipline on current expenditure. Instead, as critics warned from the start, the adjustment risk is shifting to public investment, the very line item that supports productivity, logistics and future tax revenue. That is a bad trade for an emerging market trying to keep borrowing costs contained and growth durable. If the government keeps protecting politically sensitive outlays while leaving the rule intact on paper, it will eventually choose between delaying infrastructure projects and breaking the cap again.
For investors, that is a direct macro signal. A weaker fiscal anchor usually means more pressure on local rates, a less stable currency and a higher risk premium on Brazilian equities and sovereign debt. The latest market action is consistent with that caution: EWZ has been violently repriced, falling to $29.51 on Nov. 19 from $42.59 on Oct. 23, while the dollar has strengthened to 5.91 reais, a move that reflects rising concern over policy credibility. Technical indicators on EWZ underscore how stressed the tape has become, with the ETF trading far below its 50-day and 200-day moving averages and RSI readings in deeply oversold territory. That kind of selloff can create opportunities, but only if the policy backdrop stabilizes. Right now, it is moving the other way.
The investment implication is straightforward: Brazil remains a market where the upside is real, but the fiscal regime is the gatekeeper. If lawmakers choose to amend the rule credibly, protecting investment spending while resetting the debt path to something realistic, the country could regain some lost confidence. If they do not, the law becomes a political fiction and the premium on Brazilian risk stays elevated. That leaves investors favoring exporters, dollar earners and firms with natural hedges over domestic names exposed to higher rates and a weaker currency. The next catalyst is not just the Senate vote — it is whether Brasília finally admits the rule needs repair.
| Entity | Gains | Losses |
|---|---|---|
| Exporters | ▲Weaker real boosts revenues | ▼Imported-input costs rise |
| Domestic borrowers | ▲Short-term subsidy relief | ▼Higher risk premium |
| Brazilian equities holders | ▲Tactical oversold bounce potential | ▼Fiscal credibility risk |
| Public investment projects | ▲Possible protection in a rewrite | ▼Funding delays if rule stays rigid |