Camping World Holdings is back under pressure as investors weigh customer-service complaints against a tougher consumer backdrop and a fresh warning that full-year profit will come in below the low end of its prior outlook.
Camping World Shares Slip on Profit Warning
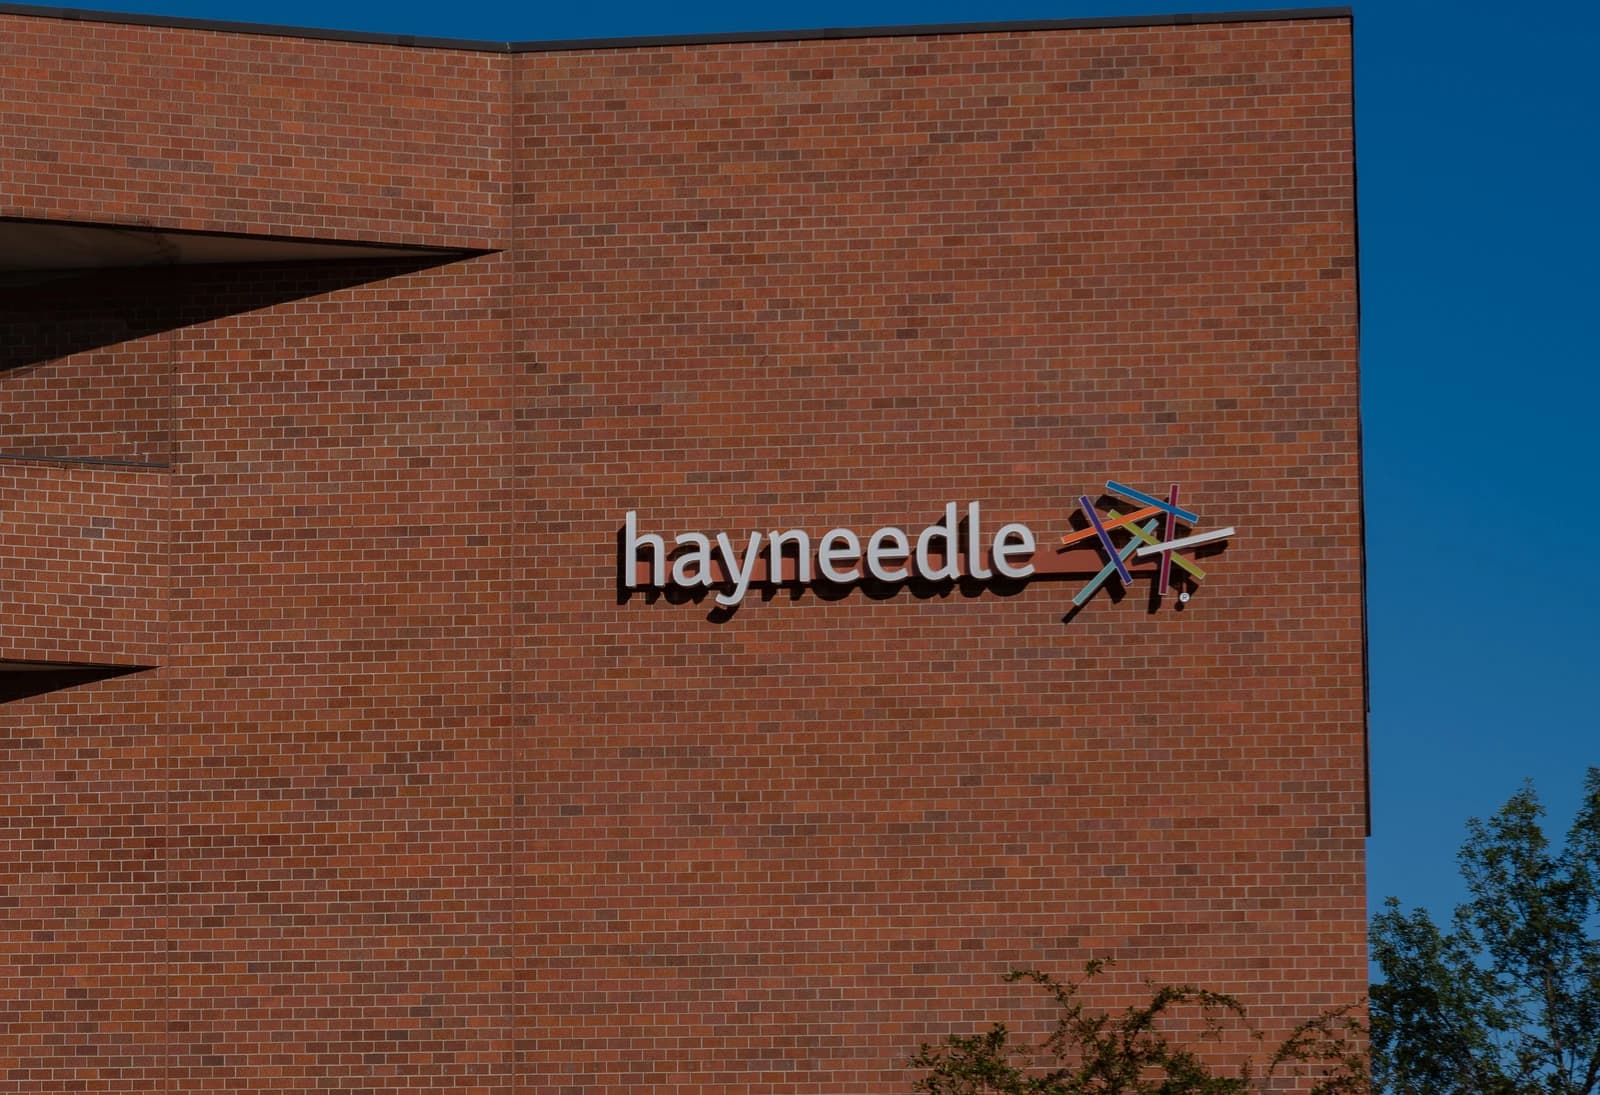
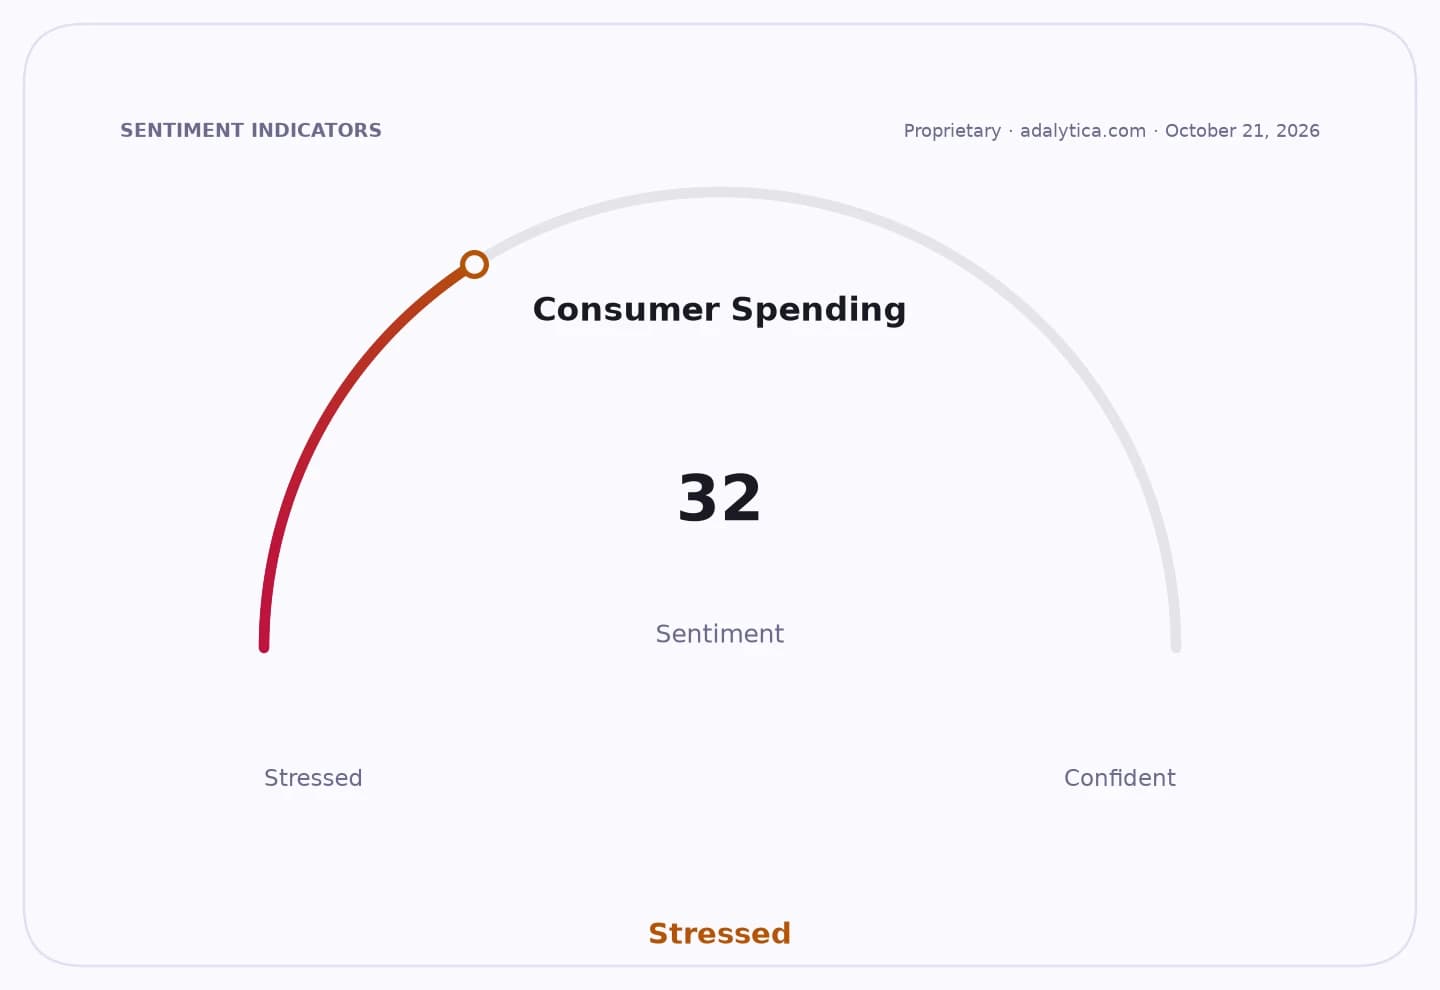
The biggest issue for the RV and outdoor retailer is not just reputational. It is whether already soft discretionary spending can absorb another hit at a time when consumer confidence is at an extreme fear reading and broader spending sentiment remains fragile, even as retail-goods sentiment has surged. For a business tied to big-ticket purchases and financing, any erosion in trust can quickly turn into slower sales, weaker margins and more volatile cash flow.
Sentiment Indicators
The stock has been exceptionally volatile. Shares closed at $5.10 on Nov. 5, after touching $4.70 in the session and rising as high as $5.53, leaving the company far below its 200-day moving average of $7.21. The 50-day average sits near $5.27, while the 14-day RSI of 58.4 and a flat MACD suggest a stock that has stabilized after sharp swings, but has not rebuilt a durable trend.
The complaint-filled backdrop matters because Camping World sells discretionary, often high-dollar products to households already sensitive to rates, credit conditions and broader economic anxiety. A weak consumer environment can delay RV purchases, hurt used-vehicle pricing and pressure service and accessory sales, all while the company faces the challenge of restoring confidence with customers who may already be reluctant to commit.
Consumer Spending vs CWHadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.
Camping World also told investors in its Oct. 5 update that it expected 2026 adjusted EBITDA to land below the low end of its prior guidance, underscoring that operational strain predates the latest customer concerns. The company’s Nov. 5 10-Q also highlighted the difficulty of forecasting sales amid U.S. economic fluctuations and local market weakness, and pointed to tariff-related exposure from inventory sourced from China, Mexico and Canada.
For investors, the key question now is whether the company can defend margins and traffic into year-end without further damage to its brand. Any signs of prolonged customer fallout, slower RV demand or another earnings reset would likely keep the shares under pressure, even after the recent bounce from October lows.
| Entity | Gains | Losses |
|---|---|---|
| Camping World | ▲Potential turnaround if trust is restored | ▼Brand damage, weaker sales, margin pressure |
| Customers | ▲Potential service improvements | ▼Delays, frustration, lost confidence |
| Investors | ▲Upside if guidance stabilizes | ▼Volatility and earnings risk |
| Competitors | ▲Share gains if customers switch | ▼None directly |