When the cost of keeping a car tops $700 a month for a commute of just 6.4 km a day, the real story is not about one North Carolina man selling his vehicle — it is about how fixed ownership costs are reshaping everyday mobility choices.
Car ownership costs push commuters to motorcycles
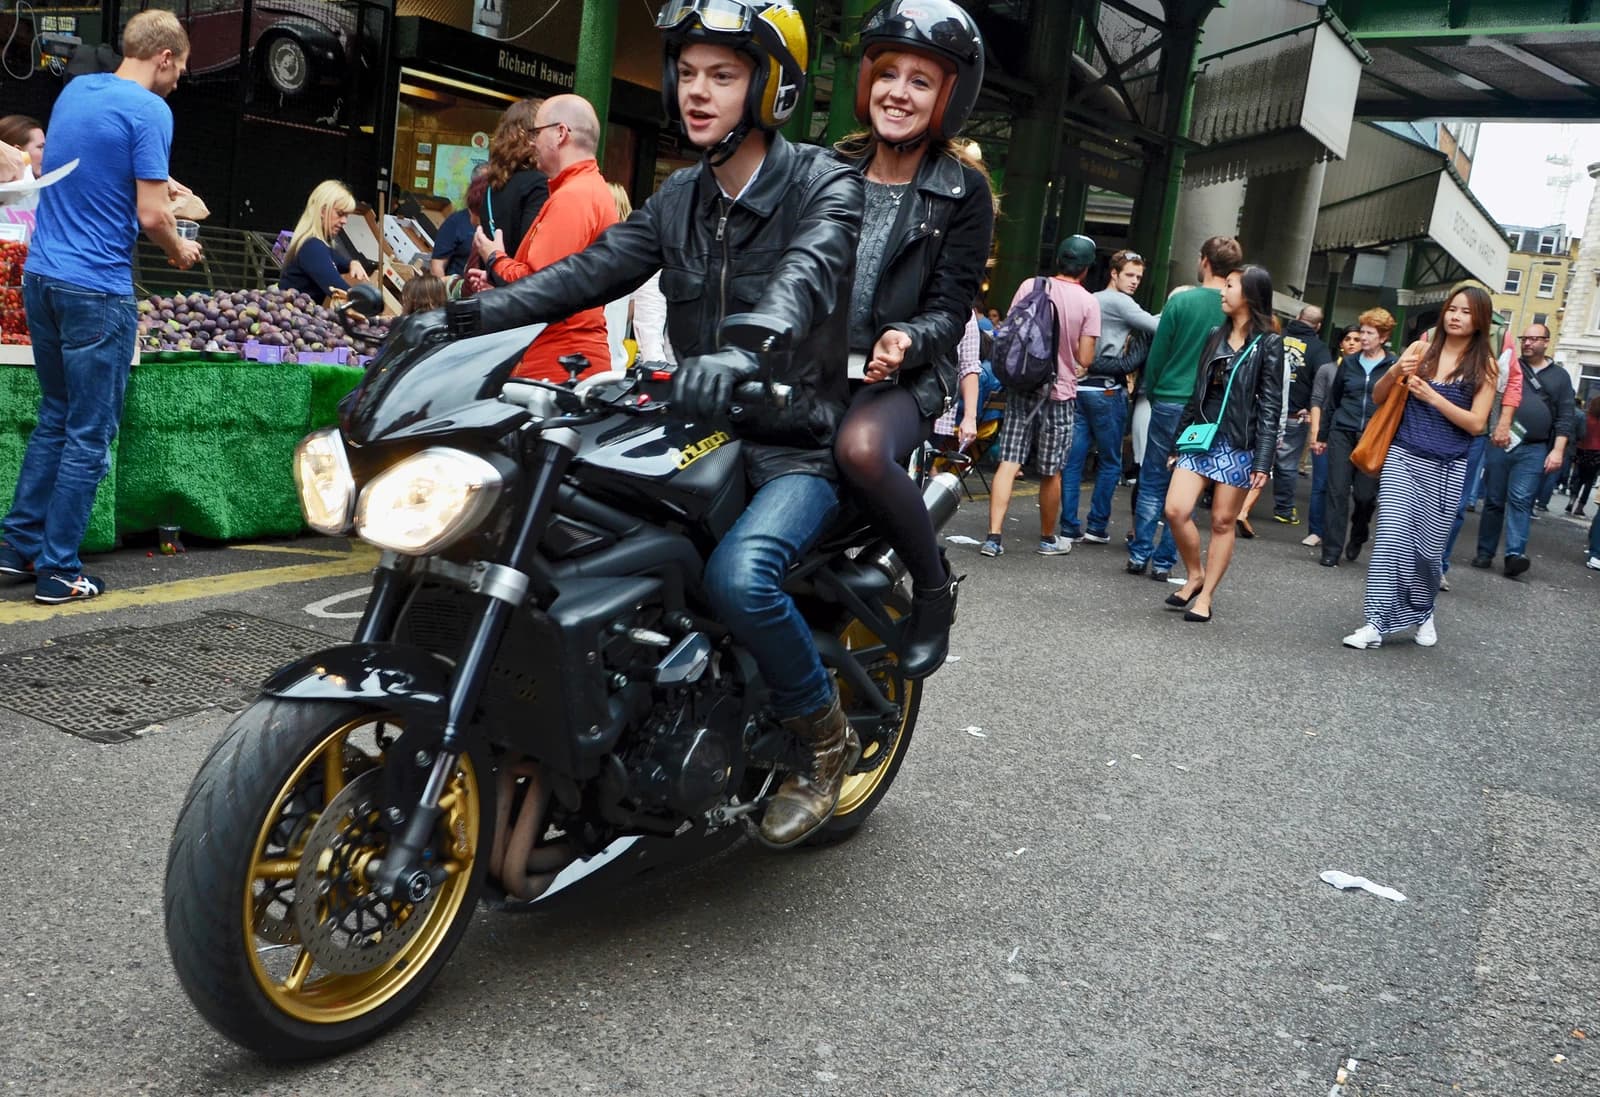
Gary Brown’s switch from a car to a motorbike captures a broader economic truth investors should not ignore: for millions of households, the expensive part of car ownership is no longer gasoline. It is the stack of unavoidable charges that arrive whether the vehicle moves or not — loan payments, insurance, parking, registration, taxes, repairs and, above all, depreciation.
That matters because it helps explain why consumers may keep looking for cheaper ways to get around even if they are not ready to abandon cars entirely. Brown’s calculation was simple. He was spending about $700 a month, or roughly 18.2 million dong, to drive a car only about 6.4 km each day. After buying a $3,500 motorcycle and spending another $1,000 on a helmet, he cut his insurance to about $35 a month and fuel to about $15 a month. Parking, one of the most brutal hidden costs in urban America, became a non-issue because he could park the bike for free in a downtown garage.
The bigger economic backdrop is even more striking. A separate report on U.S. driving costs puts the average annual cost of operating a new car at $12,863, or about $1,072 a month, up from $11,577 the year before. Depreciation alone accounted for $4,422 a year, the single largest expense. In other words, many drivers are paying thousands each year for an asset that is losing value even while it sits still.
For investors, that is a reminder that consumer behavior can shift not only because of income growth or fuel prices, but because ownership economics become hard to justify. If more commuters decide they do not need a full-size vehicle for short, predictable trips, demand could tilt toward motorcycles, used vehicles, ride-hailing, public transit and subscription-style mobility options. The winners are likely to be companies and services that help consumers spend less to move more efficiently. The losers are manufacturers and sellers of high-cost vehicles that depend on easy financing and strong replacement demand.
That does not mean the car is disappearing from American life. Brown himself said he does not expect people to give up cars and switch en masse to Uber or other alternatives. But it does show how households are becoming more ruthless about value. If a vehicle is mostly a convenience asset rather than a daily necessity, many buyers will start asking whether the monthly carrying cost is worth it.
For long-term investors, the lesson is straightforward: the mobility market is not just about selling more cars, it is about selling the cheapest practical way to move people from A to B. That makes affordability, not just horsepower or brand appeal, a durable competitive advantage. Keep this trend on your watchlist — it could matter far more over the next decade than a single monthly payment ever will.
| Entity | Gains | Losses |
|---|---|---|
| Motorbike makers | ▲Lower-cost mobility demand | ▼Carmakers in short-trip commuting |
| Ride-hailing apps | ▲Backup transport demand | ▼Car owners with fixed costs |
| Consumers with short commutes | ▲Lower monthly expenses | ▼Owners facing depreciation and parking fees |
| Auto lenders/insurers/parking operators | ▲Higher fees on existing car stock | ▼Budget-conscious drivers |