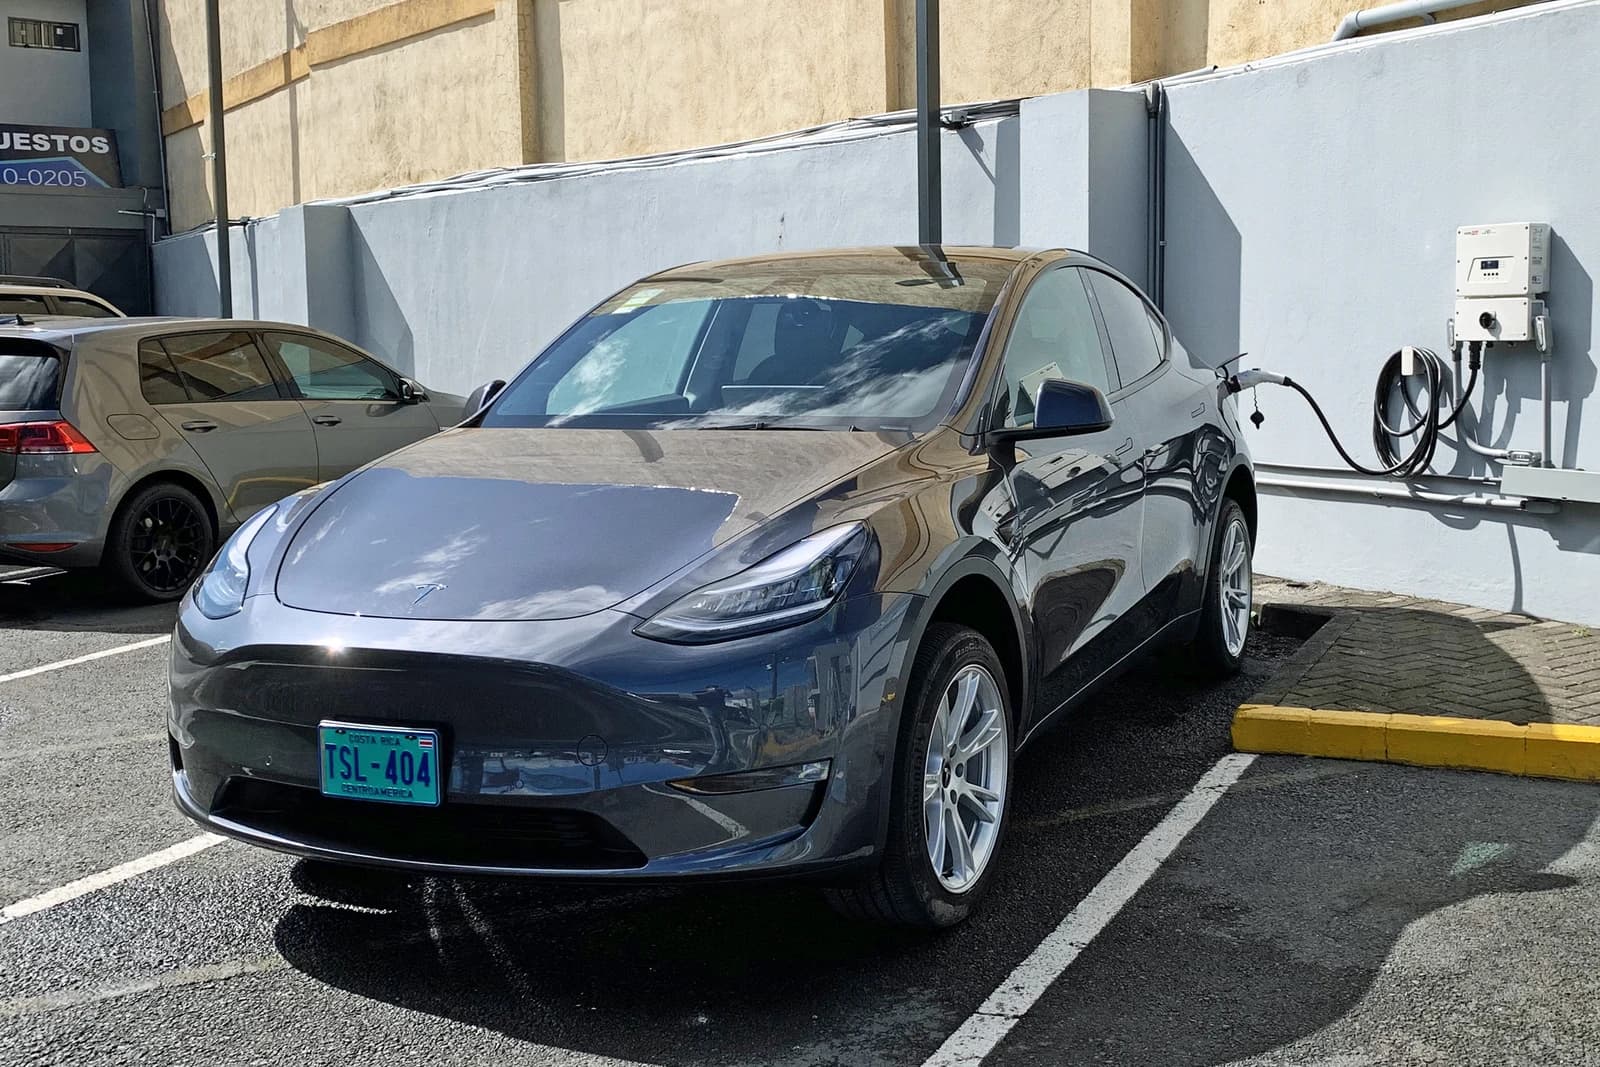
Tesla’s Cybercab is now giving paid rides in Austin, and that matters because the company is trying to turn autonomy from a demo into a scalable business before rivals lock up the market. The first public rides suggest Tesla has made real progress on comfort and product design, but the rollout also shows why the stock still trades on execution risk, not just hype.
Tesla Cybercab Paid Rides Start in Austin
That is the central investment question hanging over Tesla’s robotaxi push. Purpose-built autonomous vehicles are the prize in this industry: lower operating costs, higher utilization and eventually a service model that could be far more profitable than selling cars. If Tesla can prove the Cybercab works without a steering wheel or pedals, it gains a credible path to a network business that could eventually stretch well beyond ride-hailing and into local mobility, logistics and software revenue.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 19, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
But the Austin launch also reveals the gap between a compelling prototype and a product investors can underwrite at scale. The rides were described as smooth and surprisingly comfortable, with fares roughly in line with Uber’s base pricing at $15 to $21. That is the good news. The bad news is the service is already showing the kind of awkward behavior that can slow consumer adoption and draw regulators closer: long wait times, odd drop-off spots, and moments when the vehicle appeared indecisive on the road. In a vehicle with no manual controls, even small mistakes matter.
The timing is especially sensitive. Tesla is pushing ahead without the formal exemption route others have used for vehicles that lack conventional controls, and the National Highway Traffic Safety Administration has already opened an audit query into how the Cybercab complies with federal safety standards. That raises the odds of delays, restrictions or at minimum a more cumbersome expansion path. For Tesla, every incremental month matters because autonomy is no longer a moonshot story — it is a race against Waymo, Zoox and the rest of the industry to turn geofenced novelty into repeatable economics.
Investors should not miss the second-order effect. If Tesla can solve the software and regulatory friction, the upside is not just in robotaxi rides, but in a premium multiple for a company increasingly valued on AI, compute and autonomy rather than on EV units alone. If it cannot, the market will keep treating Cybercab as another expensive proof-of-concept. With Tesla shares already trading near the upper end of their recent range and technical momentum still elevated, the Austin rollout is likely to be a catalyst for volatility before it becomes a catalyst for conviction.
My view: this is still an asymmetric bet, but the asymmetry cuts both ways. Tesla has shown enough to keep autonomy investors interested, yet not enough to prove the rollout can scale cleanly under real-world scrutiny. The next few weeks in Austin will tell the market whether Cybercab is the beginning of Tesla’s next profit engine — or another reminder that autonomous mobility is harder than the narrative suggests.
| Entity | Gains | Losses |
|---|---|---|
| Tesla | ▲Autonomy credibility | ▼Regulatory patience |
| Tesla bulls | ▲Robotaxi upside | ▼Near-term certainty |
| Uber | ▲Proof autonomy demand exists | ▼Potential long-term share loss |
| Waymo/Zoox | ▲Validation of market category | ▼Tesla catching up fast |