US companies are showing renewed interest in China’s export machine, but the bigger message for investors is that trade between the world’s two largest economies is still being managed, not unwound. The latest Canton Fair drew 22.2% more American buyers than the April edition, according to organizers, a sharp rebound that followed the Xi-Trump meeting and points to cautious thawing in commercial ties.
China Canton Fair Draws More U.S. Buyers
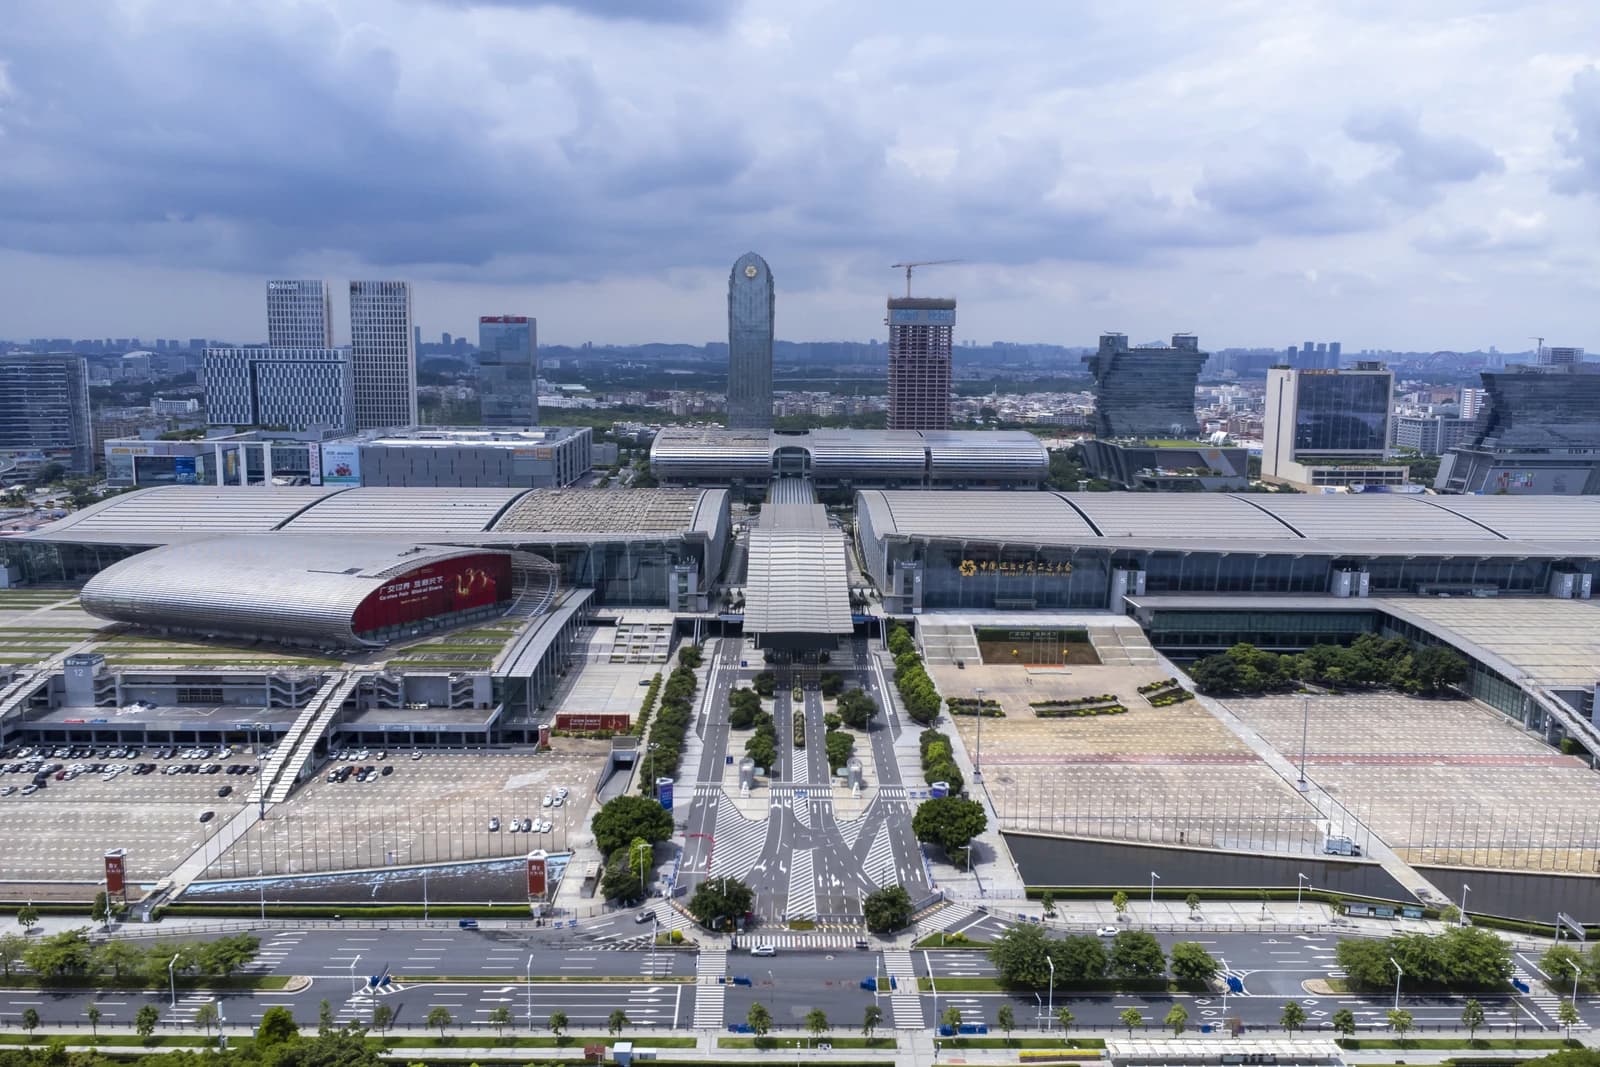
That matters because the fair is one of the clearest real-time gauges of demand for Chinese goods from abroad. A pickup in US attendance suggests buyers are still looking for China’s scale, supply chain depth and pricing power even after years of tariff pressure and geopolitical friction. European attendance also rose 38.2%, reinforcing the idea that global sourcing remains resilient even as companies try to diversify.
Sentiment Indicators
For investors, the implications stretch beyond one trade show. A steadier US-China relationship can help ease pressure on importers, retailers and logistics companies that have been dealing with a volatile tariff backdrop and sticky inflation. Walmart has said less than a third of what it sells in the US is imported, much of it from China and other Asian suppliers, while Nike has already shown how sensitive sales in Greater China can be to trade and demand swings. Any sign of better commercial visibility is welcome for companies that rely on cross-border sourcing and consumer demand.
But the fair also exposed the limits of the rebound. Exporters said high inflation in the West continued to weigh on deal making, which means more foot traffic does not automatically translate into stronger orders. In other words, diplomacy may be opening the door, but macroeconomic strain is still deciding how much business actually gets done.
That leaves the current trade truce looking more like a floor than a breakthrough. China and the US have an incentive to keep the channels open, and that should support sentiment in Chinese equities and broader emerging-markets trade plays. Chinese stocks tracked by the iShares China Large-Cap ETF, or FXI, have been holding just above their 50-day moving average, while the iShares MSCI China ETF, MCHI, remains below its 200-day average, a reminder that investors are still waiting for a durable earnings-led recovery.
For long-term investors, the takeaway is straightforward: less confrontation is good for global commerce, but the real prize will be sustained demand, not just improved optics. Until higher Western inflation fades and tariff risk becomes more predictable, this is a story of incremental improvement rather than a full reset. Still, if you own multinational retailers, industrials or China-linked ETFs, this is worth watching closely and keeping on a long-term watchlist.
| Entity | Gains | Losses |
|---|---|---|
| US buyers | ▲More sourcing options | ▼Less bargaining leverage |
| Chinese exporters | ▲More foot traffic | ▼Still face weak pricing power |
| Global retailers | ▲Better supply visibility | ▼Inflation-related margin pressure |
| China/US trade truce | ▲Lower escalation risk | ▼No full trade breakthrough |