China’s copper import premium has surged to a record as traders weigh whether a potential shift in large US inventories could loosen global supply later, even as physical availability in China stays painfully tight.
China Copper Import Premium Hits Record High
The premium for imported copper cathode in China hit $220 a metric ton over the London Metal Exchange cash price on Nov. 6, up $100 a ton, or 83.3%, in a month, according to Platts. That was the highest level since the assessment began in 2014 and underscores how short prompt copper supply has become in the world’s biggest consumer.
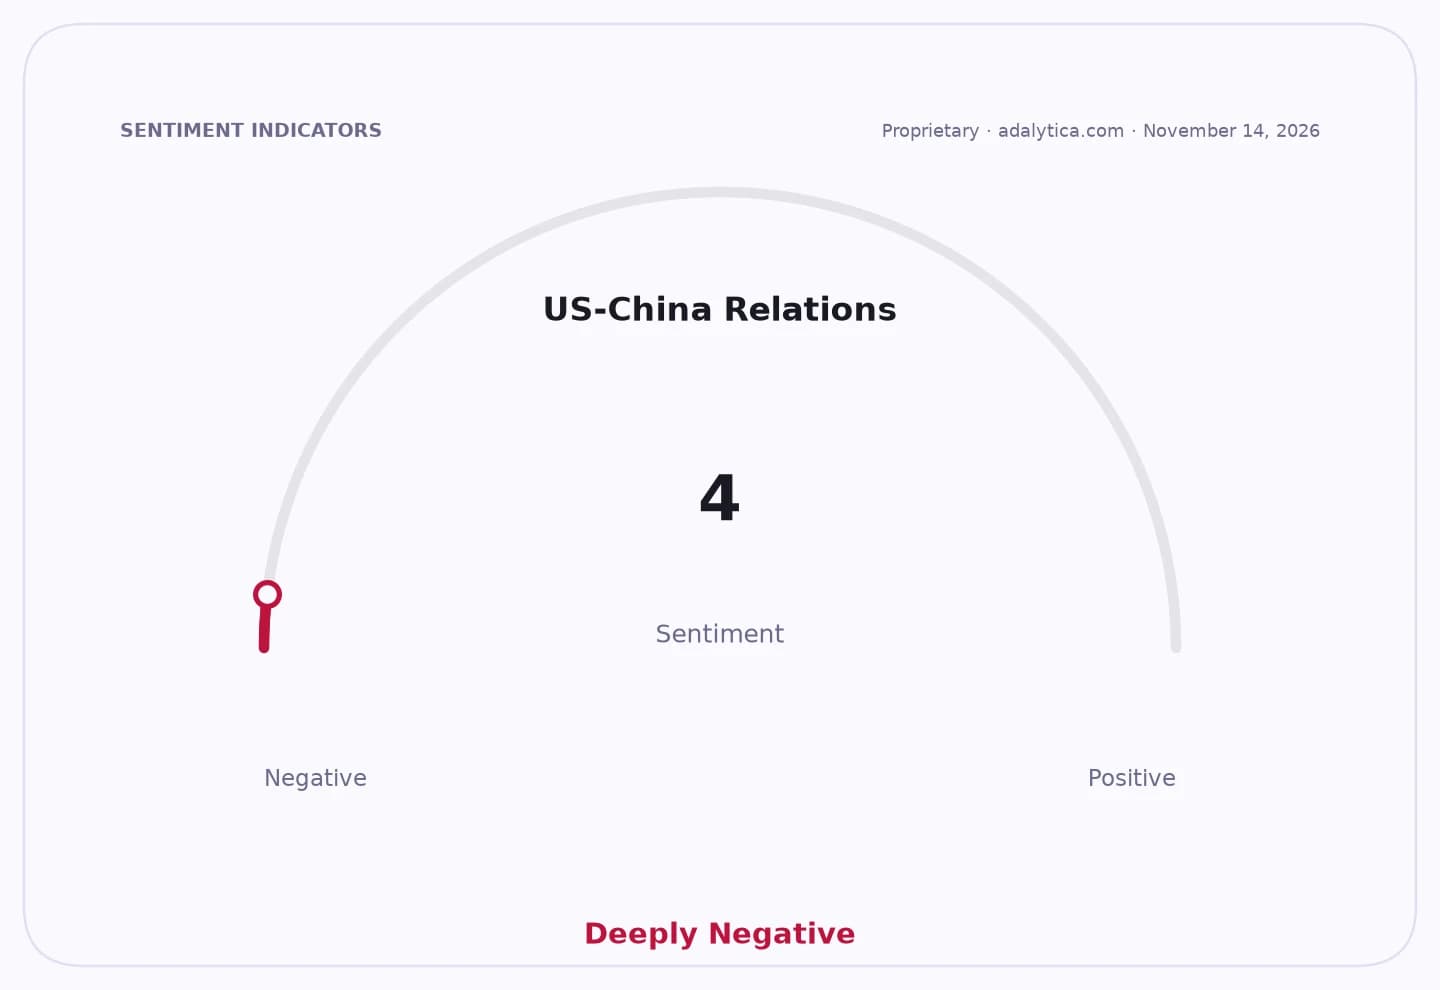
Sentiment Indicators
The move matters because copper premiums are a direct read on buying urgency in China’s spot market. When premiums rise, it usually means buyers are willing to pay more to secure metal from abroad, a sign domestic supply is not keeping pace with demand.
At the same time, market participants are rethinking the flow of metal into the US after the midterm elections. China-based traders are increasingly betting that softer US tariff policy in 2027 could reduce the incentive to ship refined copper into America, potentially leaving more metal available for other markets.
That dynamic has already shown up in the pricing gap between the US and London. The COMEX-LME spread narrowed to about minus $85 a ton as of Nov. 4, compared with a COMEX premium of about $89 a ton a month earlier, reducing the arbitrage that had pulled copper into US warehouses.
Even so, any rerouting of inventories would likely be slow. Logistics, local US demand and contract structures mean metal would not be freed up overnight, leaving China’s near-term spot market exposed to ongoing tightness.
Domestic conditions remain stretched. Exchange inventories in China have been falling, smelter maintenance has constrained output and limited spot availability has forced consumers toward imported cathode. Spot premiums in the Chinese market were heard around 1,900 yuan a ton, or about $285, as of Nov. 5, while Shanghai Futures Exchange copper stocks dropped 17.9% week over week to 44,612 tons as of Oct. 30.
For investors, the record premium is a reminder that copper’s pricing is being driven by physical scarcity as much as macro expectations. The setup supports near-term strength for miners and producers with exposure to realized copper prices, while keeping pressure on fabricators and buyers that need prompt supply.
Shares of major copper producers have already been volatile as the market swings between supply-tightness and tariff-driven expectations. Freeport-McMoRan and Southern Copper were both lower in recent sessions, even as their longer-term earnings prospects remain tied to copper’s ability to hold at elevated levels.
The next catalyst is whether US trade policy and inventory flows actually loosen the global market into 2027, or whether China’s spot tightness keeps premiums elevated for longer.
| Entity | Gains | Losses |
|---|---|---|
| Chinese copper buyers | ▲More urgency to secure supply | ▼Higher import costs |
| Copper miners/producers | ▲Stronger realized prices | ▼Limited if premiums compress |
| US stockholders/traders | ▲Potentially higher arbitrage value | ▼Less if tariffs ease |
| Fabricators/industrial users | ▲None | ▼Tighter margins and cost pressure |