China’s service sector lost momentum in October, with the RatingDog services PMI slipping to 50.8 from 51.6 in September, the first drop since July and a sign that the country’s uneven recovery is cooling again.
China Services PMI Falls to 50.8 in October
The reading still sits above the 50-point line that separates expansion from contraction, but it came in well below the 51.7 economists had expected and followed a surprise weakening in the official services gauge, which fell to 49.7 over the weekend. Together, the two surveys point to softer demand across a key part of the economy that has been helping offset weakness in factories and property.
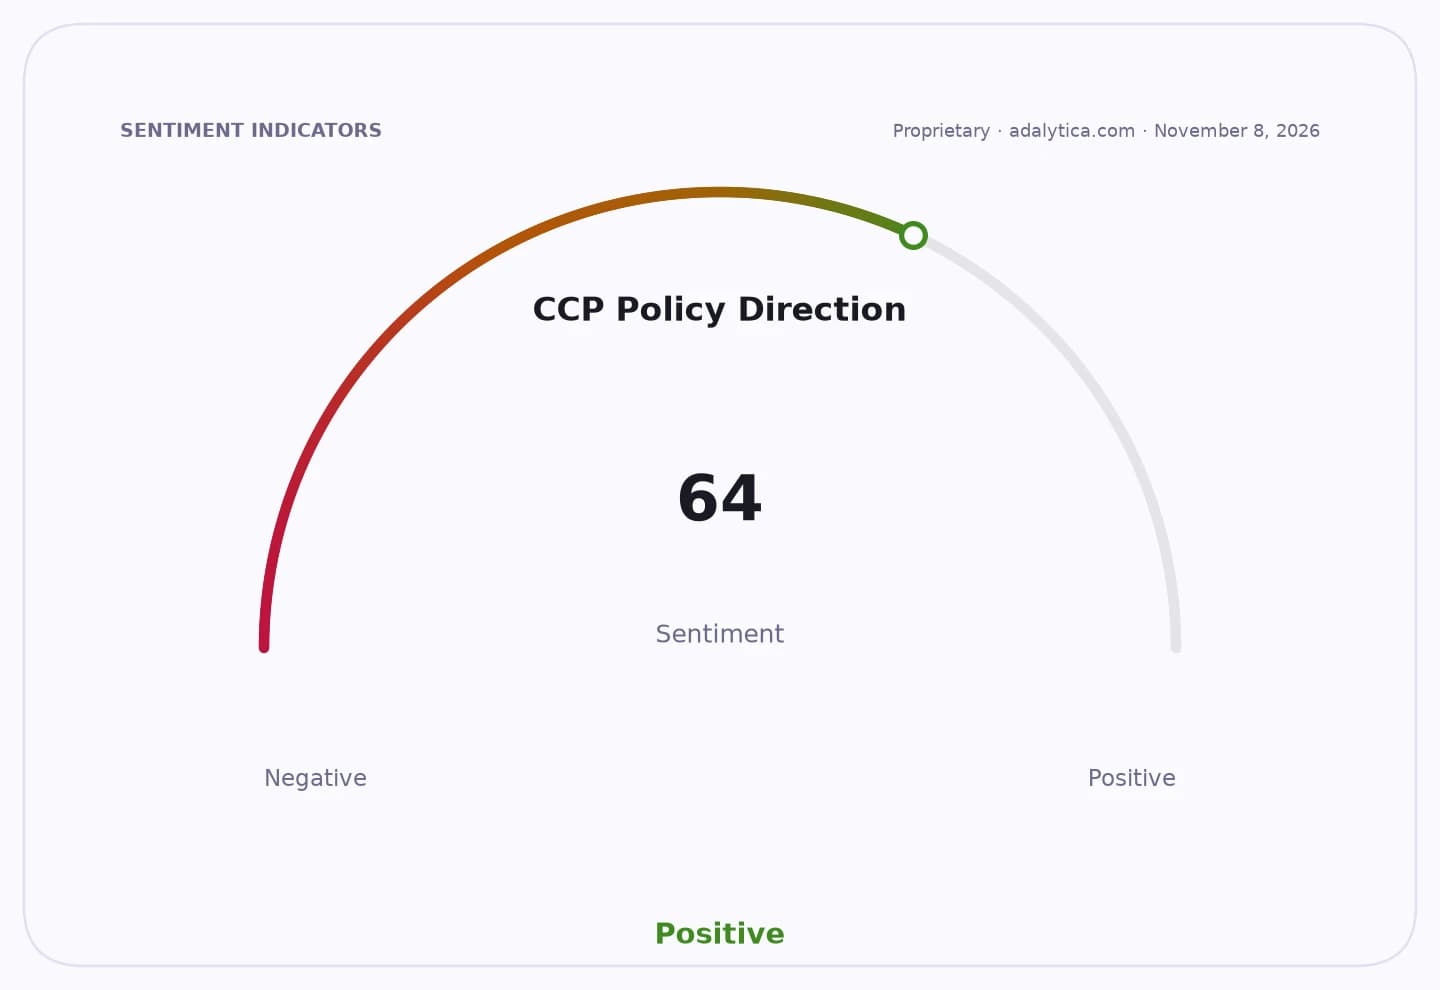
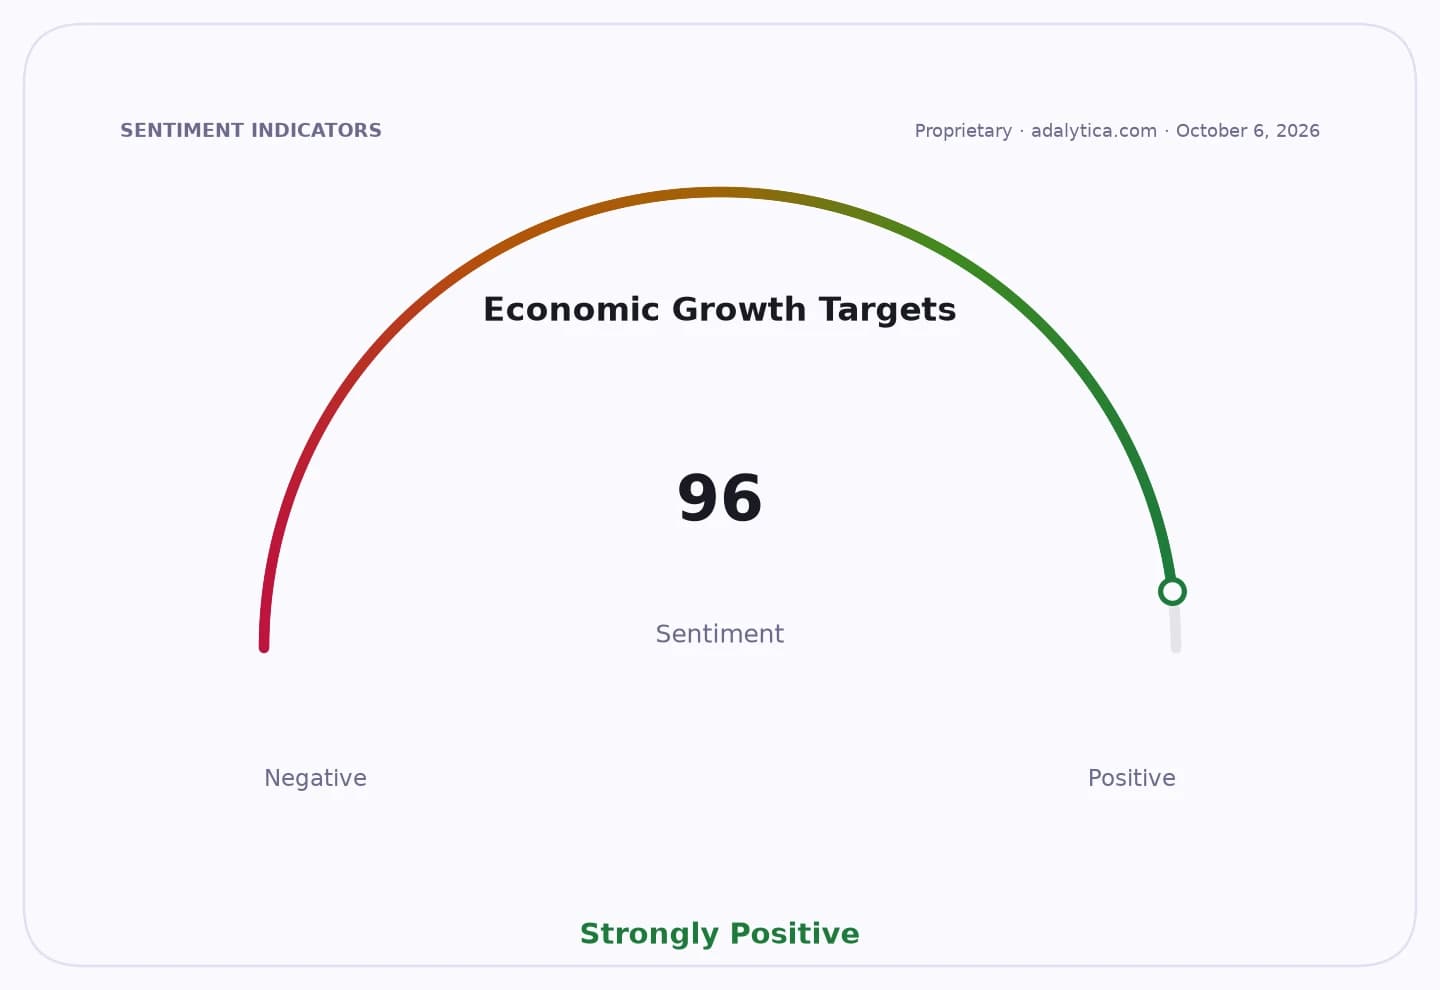
Sentiment Indicators
That matters because services account for a large share of China’s growth, employment and consumer spending. A slower pace in areas such as transport, leisure, retail and business services can quickly feed into weaker income growth and less resilient domestic consumption, making it harder for Beijing to stabilize activity without more policy support.
RatingDog said new orders were still rising at a “solid pace,” suggesting the slowdown is not yet a full reversal. But the direction of travel is clearly weaker at the start of the fourth quarter, especially as the official manufacturing PMI also pointed to contraction, underscoring broad pressure across both industrial and service activity.
For investors, the data strengthens the case for continued policy easing or targeted stimulus if growth keeps fading. China-linked equities and ETFs such as FXI and MCHI are likely to stay sensitive to signs that officials need to lean harder on fiscal or monetary support, while the leverage ETF YINN remains exposed to any shift in sentiment toward more aggressive Chinese stimulus bets.
The latest readings also fit a broader market narrative of fragile confidence in China rather than a clean rebound. Technical indicators on the China ETFs show mixed momentum, but the macro message is more important: if services cannot sustain growth above the expansion threshold, pressure will build on policymakers heading into year-end.
| Entity | Gains | Losses |
|---|---|---|
| Chinese policymakers | ▲More case for stimulus | ▼More pressure to support growth |
| Consumers | ▲Potential policy support later | ▼Softer income and spending momentum |
| China equities ETFs | ▲Stimulus hopes could lift flows | ▼Near-term growth worries weigh on sentiment |
| Service providers | ▲New orders still expanding | ▼Slower growth and weaker demand |