Copper is closing in on a historic price peak because the market is being squeezed from both sides: Washington’s tariff threat is pulling metal into U.S. warehouses, while mine disruptions and resilient electrification demand are limiting fresh supply.
Copper near record on tariffs and supply cuts
ANZ now expects the world price of copper to reach $14,500 a metric ton by the end of 2026 and $15,000 in early 2027, a level that would mark a new record. The bank’s forecast implies another leg higher after copper has already risen about 15% since the start of the year, underscoring how quickly a market once defined by cyclical softness has tightened.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The benchmark three-month copper contract on the London Metal Exchange was trading around $14,245 a ton on Sept. 3, 2026, near its previous all-time high set in late January. That proximity to record territory matters because copper is one of the clearest real-time gauges of industrial demand, global manufacturing momentum and the cost of building the electrified economy.
The latest rally is not being driven by demand alone. Fears of new U.S. duties on refined copper under the Trump administration have triggered large physical stock shifts into U.S. warehouses, effectively removing metal from the rest of the global system. That kind of inventory migration can exaggerate tightness far beyond underlying consumption trends and leaves exporters, fabricators and spot buyers competing for a smaller pool of available supply.
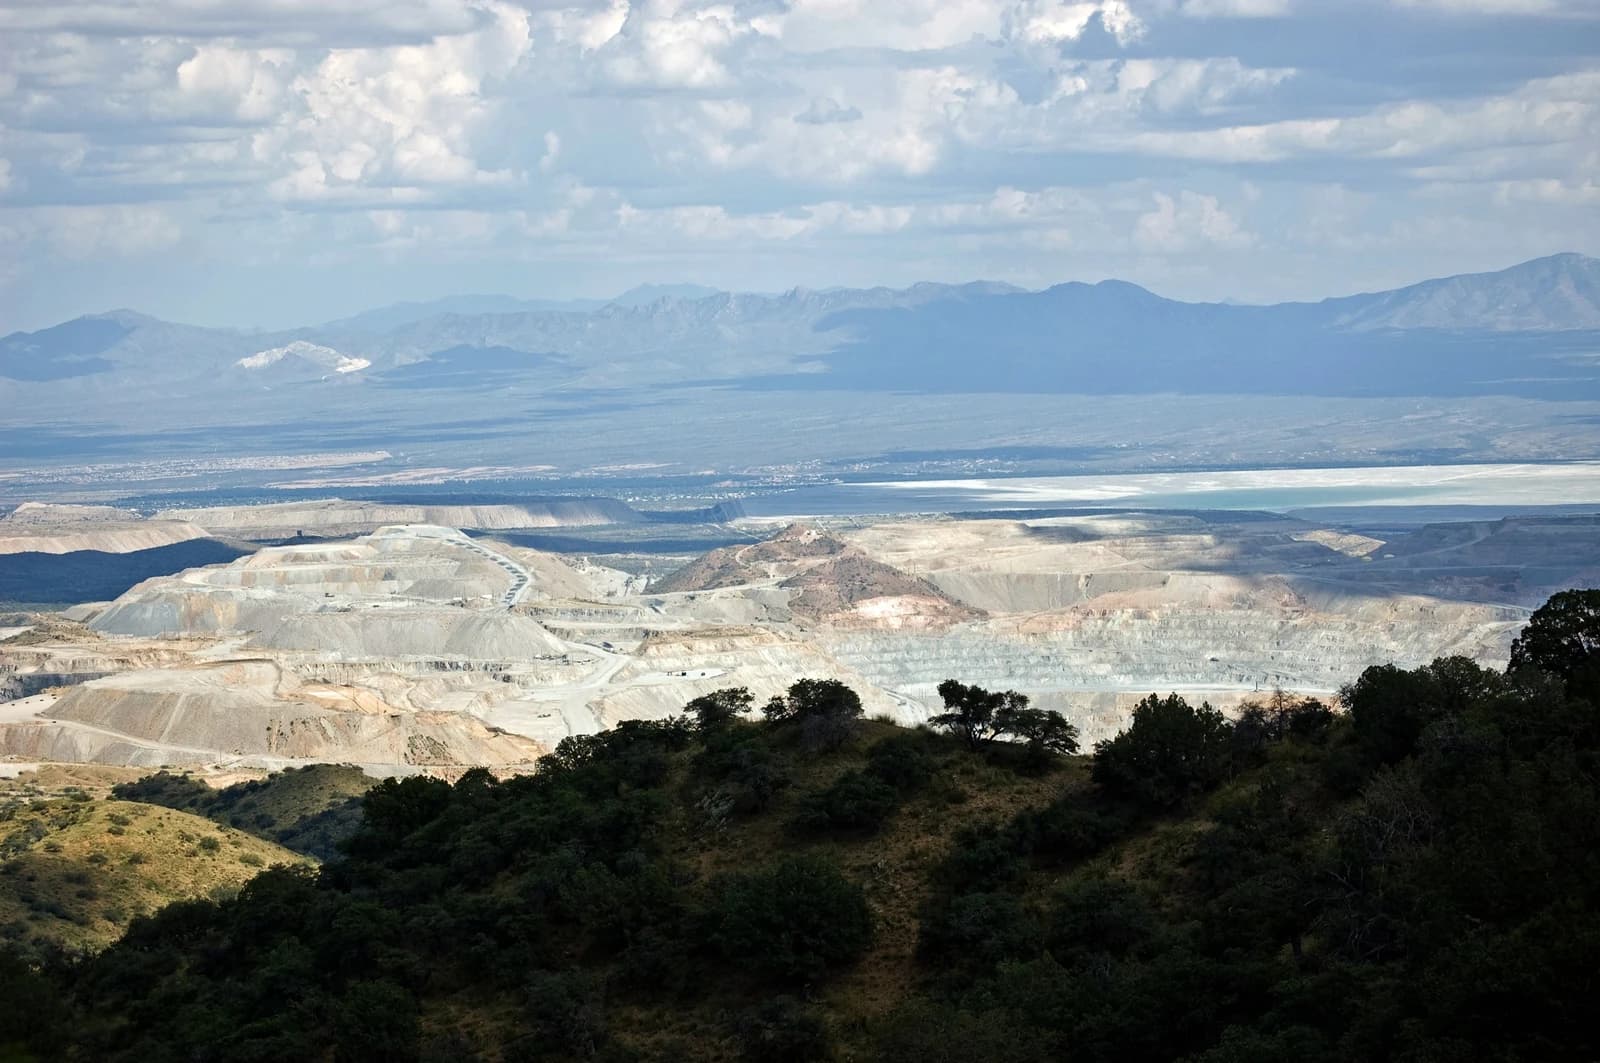
At the same time, mining disruptions in South America are constraining output just as demand from electric vehicles, power grids and other transition-energy infrastructure keeps rising. The result is a classic supply shock in a metal that is already structurally important to decarbonization, data centres and electrification more broadly. In equity markets, that backdrop has helped miners outperform, with BHP shares hitting a record high, while copper-linked producers such as Jintian and Harmony Gold have reported stronger profits and cash flow.
For investors, the key question is not whether copper is strong, but how long the tightness can persist. Bulls can point to the structural demand story and the risk that tariffs keep distorting inventories. Bears can argue that some of the move reflects temporary stockpiling and that a tariff-induced demand wobble or a broader industrial slowdown could cool prices. But with supply still constrained and futures already near prior highs, the market is pricing scarcity rather than comfort — and that keeps copper, miners and industrial users exposed to another round of volatility if trade policy or mine supply shifts again.
| Entity | Gains | Losses |
|---|---|---|
| Copper miners | ▲Higher realized prices | ▼Higher volatility risk |
| Industrial users | ▲— | ▼Higher input costs |
| BHP and peers | ▲Record cash flow potential | ▼Policy and execution risk |
| U.S. stockpilers | ▲Supply security | ▼Tighter global availability |