Doha Bank is back in the dollar market with a benchmark-sized five-year senior unsecured bond, tapping investors at a time when global borrowing costs remain elevated but demand for bank paper still looks deep enough to absorb new supply.
Doha Bank prices five-year dollar bond at 170 bps
The Qatari lender, rated A by Fitch and Baa1 by Moody’s, is marketing the Regulation S notes at around 170 basis points over U.S. Treasuries. The deal, expected to list on the London Stock Exchange’s International Securities Market, gives Doha Bank a fresh way to raise term funding in dollars and extend its liability profile without relying solely on deposits.
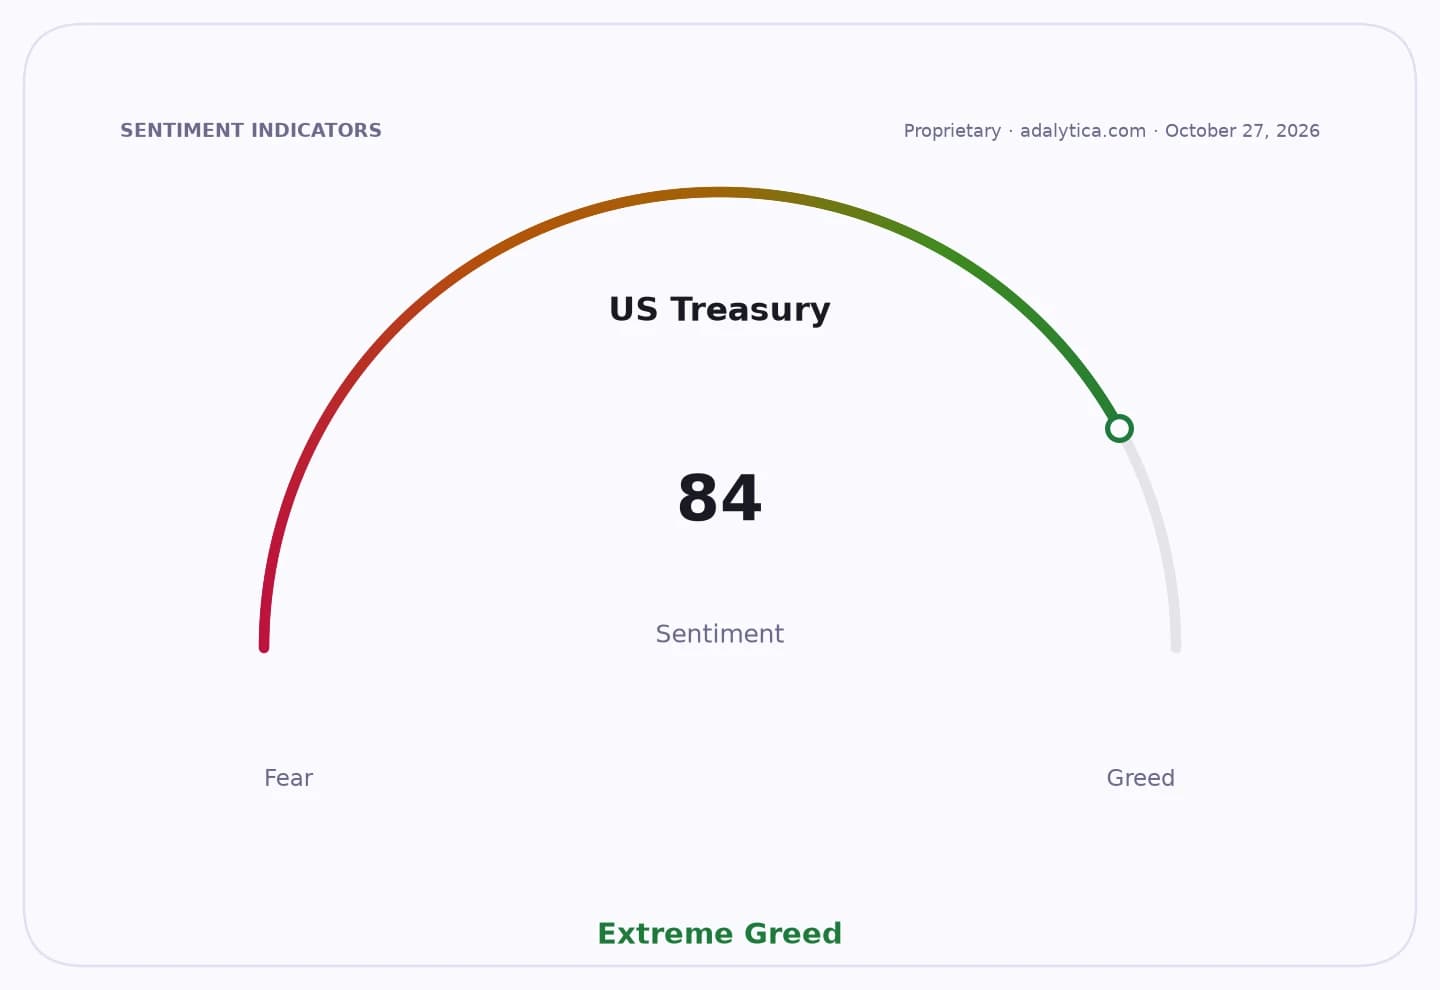
Sentiment IndicatorsⓘProprietary · adalytica.com · October 27, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters because bank bond issuance is one of the clearest gauges of funding appetite in the Gulf. When regional lenders come to market with benchmark deals, they are not just refinancing themselves; they are testing how much risk investors are willing to take on financial institutions exposed to local growth, rate volatility and broader credit conditions. In a world where five-year U.S. Treasury yields are still near 4.8% and credit spreads remain meaningful, every basis point matters.
For investors, the takeaway is straightforward: higher-rated Gulf banks continue to have access to international capital, but they are paying up for it. The 170-basis-point spread over Treasuries suggests buyers are still asking for a premium over government debt, even from an investment-grade issuer. That premium can make these bonds attractive for income-focused investors if they believe the bank’s balance sheet remains solid and Qatar’s banking system stays resilient.
It also fits a broader pattern in credit markets. Borrowers are using the window available to secure funding before conditions shift again, while investors remain selective as volatility in rates and foreign exchange stays in the background. With U.S. Treasury markets still pricing a fairly high level of long-term rates and credit spreads not especially tight, borrowers that can print size today may prefer to do so now rather than wait.
For long-term investors, the story is less about one bond than about a durable theme: strong regional banks in the Gulf still have access to global dollar funding, and that access is a competitive advantage when markets tighten. Doha Bank’s deal is worth watching, especially for fixed-income investors looking for yield without stepping too far down the credit ladder.
| Entity | Gains | Losses |
|---|---|---|
| Doha Bank | ▲Dollar funding access | ▼Higher interest expense |
| Bond investors | ▲Investment-grade yield | ▼Rate and credit risk |
| U.S. Treasury holders | ▲Relative safety | ▼Less yield pickup |
| Competing regional banks | ▲Market benchmark | ▼Attention to own funding costs |