Copper’s climb to about $6.60 a pound is reshaping the economics of mining in the Dominican Republic, turning deposits that were once secondary to gold and silver into potential new sources of export revenue and investment.
Dominican Republic Copper Output Outlook Improves
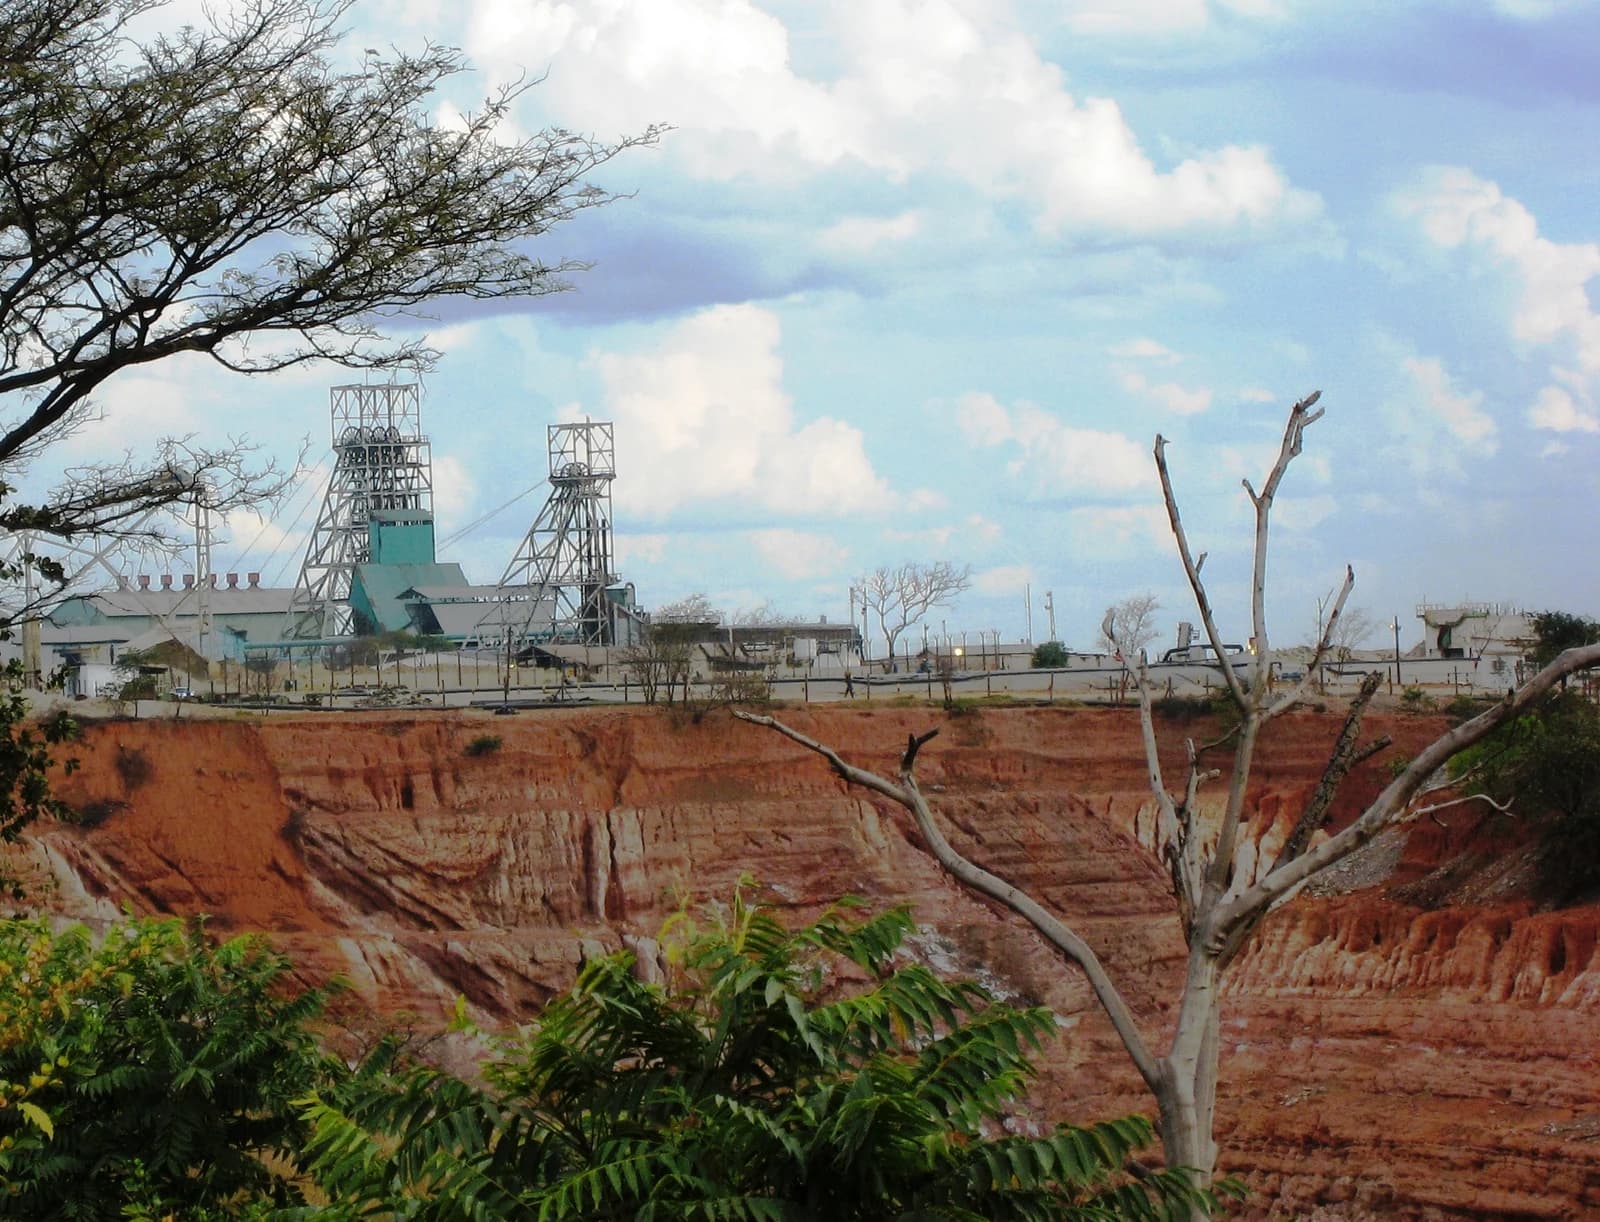
The move matters because the country’s largest mineral projects are already tied to copper-bearing geology, and higher prices improve the case for processing material that was previously left in tailings or treated as a byproduct. At Pueblo Viejo, where Barrick Gold and Newmont operate one of the region’s biggest mines, the original deposit was identified as a copper porphyry with associated gold and silver, and a copper line has already been installed but largely sat in wait for better prices.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That wait may now be over. The report says authorities from the Energy and Mines Ministry are pressing Barrick-Pueblo Viejo to bring copper production online, a move that could unlock value from material now sitting in the El Llagal tailings dam. A second tailings facility scheduled for 2029 would also widen the potential resource base if copper recovery becomes part of the long-term plan.
The same price backdrop strengthens the economics at Cerro Maimón, where Cormidom, owned by China’s Perilya, has already extracted a high-grade surface copper ore body and still produces copper and zinc for export to China. For a country trying to expand mineral exports, every dollar higher in copper increases the appeal of extracting metals that were once uneconomic.
The rally also revives interest in other Dominican deposits, including Unigold’s Los Candelones project in Restauración, which geologists now describe as a possible much larger copper porphyry system than Cerro Maimón. If that assessment holds, the Dominican Republic could be moving from a gold-and-silver story to a broader copper-producing jurisdiction.
For investors, the implication is straightforward: rising copper prices improve margins, extend mine lives and make expansion spending easier to justify, especially for operators with existing infrastructure. The wider copper market has been supported by supply disruptions, tighter inventories and demand from electrification and data-center buildout, while oil, industrial production and dollar signals point to a still-uncertain global backdrop.
The near-term catalyst is whether Barrick, Newmont and local authorities move from discussion to commissioning at Pueblo Viejo. If they do, the Dominican mining sector could enter a new cycle with copper as a bigger contributor to exports, earnings and project valuations.
| Entity | Gains | Losses |
|---|---|---|
| Barrick Gold / Newmont | ▲Higher recoverable value at Pueblo Viejo | ▼Idle copper line, lower byproduct upside |
| Cormidom / Perilya | ▲Stronger copper-zinc export margins | ▼Less pressure from weak pricing |
| Dominican Republic | ▲Bigger export base, mining investment | ▼Tailings remain underused if stalled |
| Copper buyers/importers | ▲More supply if projects advance | ▼Higher feedstock costs today |