Poultry and egg prices in eastern markets are under pressure today as a bird flu scare and weaker demand drive shell-egg prices below production costs in major producing hubs, a development that threatens farmer margins and could ripple through regional food inflation.
Eastern Poultry and Egg Prices Fall on Weak Demand
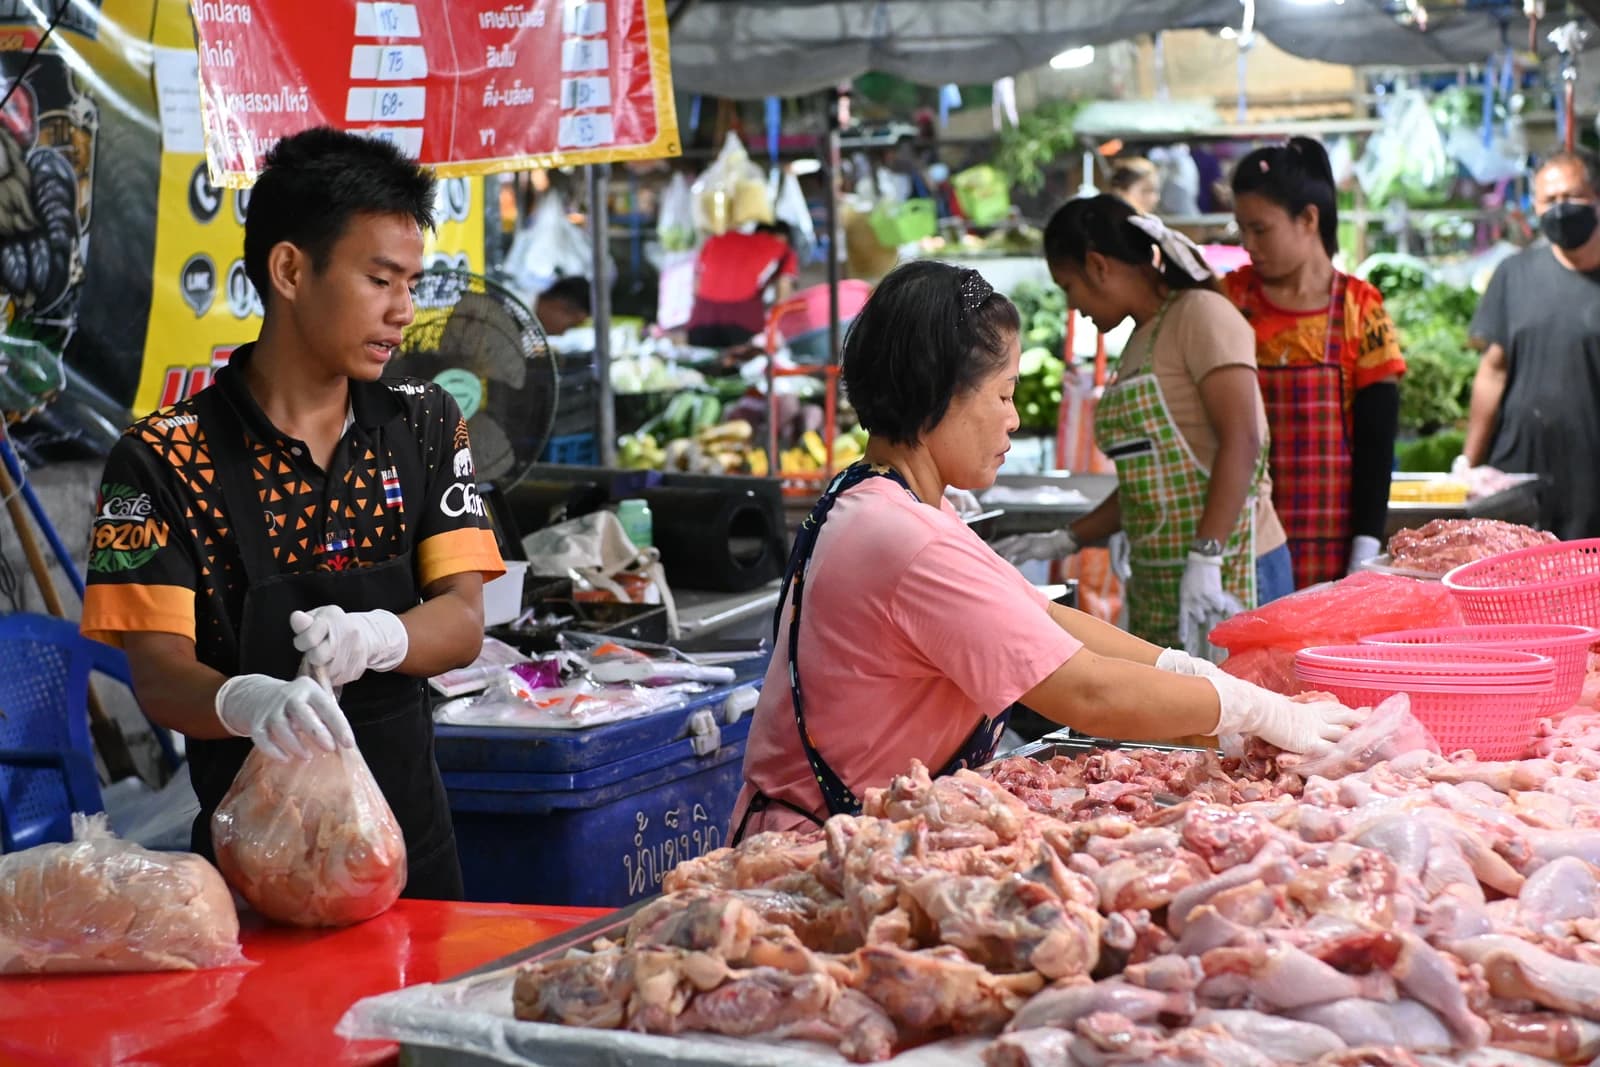
The most important shift is not a one-day move in retail tags, but the squeeze on producers. When eggs trade below the cost of production, poultry farms lose the ability to cover feed, labor and biosecurity expenses, forcing smaller operators to cut output or absorb losses. That matters economically because poultry is one of the fastest-moving proteins in household budgets: any disruption in farm economics can quickly feed into supply, employment and consumer prices.
Sentiment Indicators
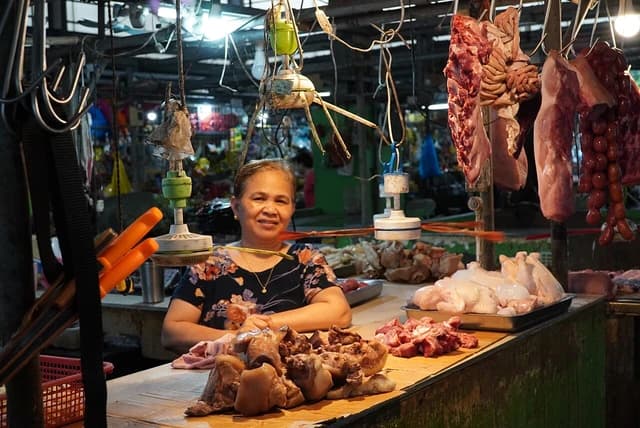
The stress is already visible in export channels. The drop in prices has been accompanied by a sharp pullback in exports from Namakkal, one of the key egg-producing centers, while chicken farmers in Polman are facing similar price declines and bankruptcy risk. For buyers, that may translate into near-term relief at the checkout counter. For producers, it raises the odds of consolidation, culling and less investment in capacity just as disease risk stays elevated.
The broader backdrop is one of fragile food pricing. U.S. data in the context show consumer inflation at 337.476 in October and a forecast 338.6475 for November, while producer prices are projected to rise to 297.076. Even if those figures are not directly tied to the poultry trade, they underscore a market where food and farm input costs remain elevated and volatile. Feed is still the critical pressure point: Tyson Foods said corn, soybean meal and other feed ingredients made up about 52% of the cost of raising a live chicken domestically in fiscal 2026, leaving producers highly exposed when end-market prices fall faster than input costs.
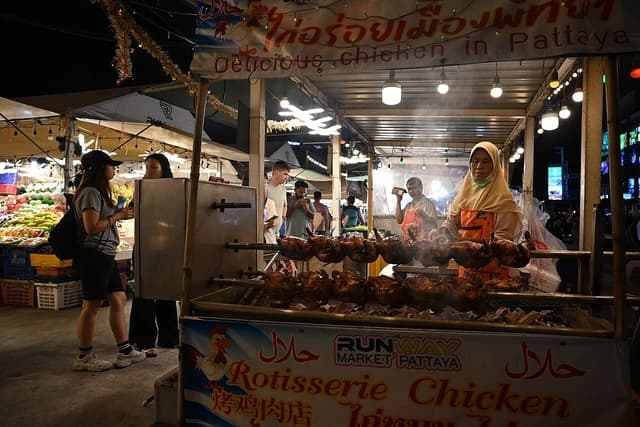
For investors, the setup is a classic divergence trade. Integrated meat companies with scale, pricing power and hedging tools can navigate volatility better than smaller farms and independent egg producers. But if disease fears deepen and supply contracts, downstream processors and retailers may eventually face tighter availability and higher procurement costs, even after a near-term price drop. The market underestimates how quickly a poultry bust can flip into a supply shock.
The takeaway: eastern poultry and egg markets are offering consumers a temporary bargain, but the real story is margin destruction for producers and the growing probability of a later supply rebound. That makes the sector attractive only for the strongest operators and the toll-road businesses around them — feed suppliers, processors and branded protein platforms that can survive the squeeze and gain share when weaker farms exit.
| Entity | Gains | Losses |
|---|---|---|
| Consumers | ▲Lower egg prices | ▼Less stable supply later |
| Small poultry farmers | ▲— | ▼Negative margins, bankruptcy risk |
| Integrated processors | ▲Market share gains | ▼Short-term input volatility |
| Feed suppliers | ▲Demand resilience | ▼Producer distress limits growth |