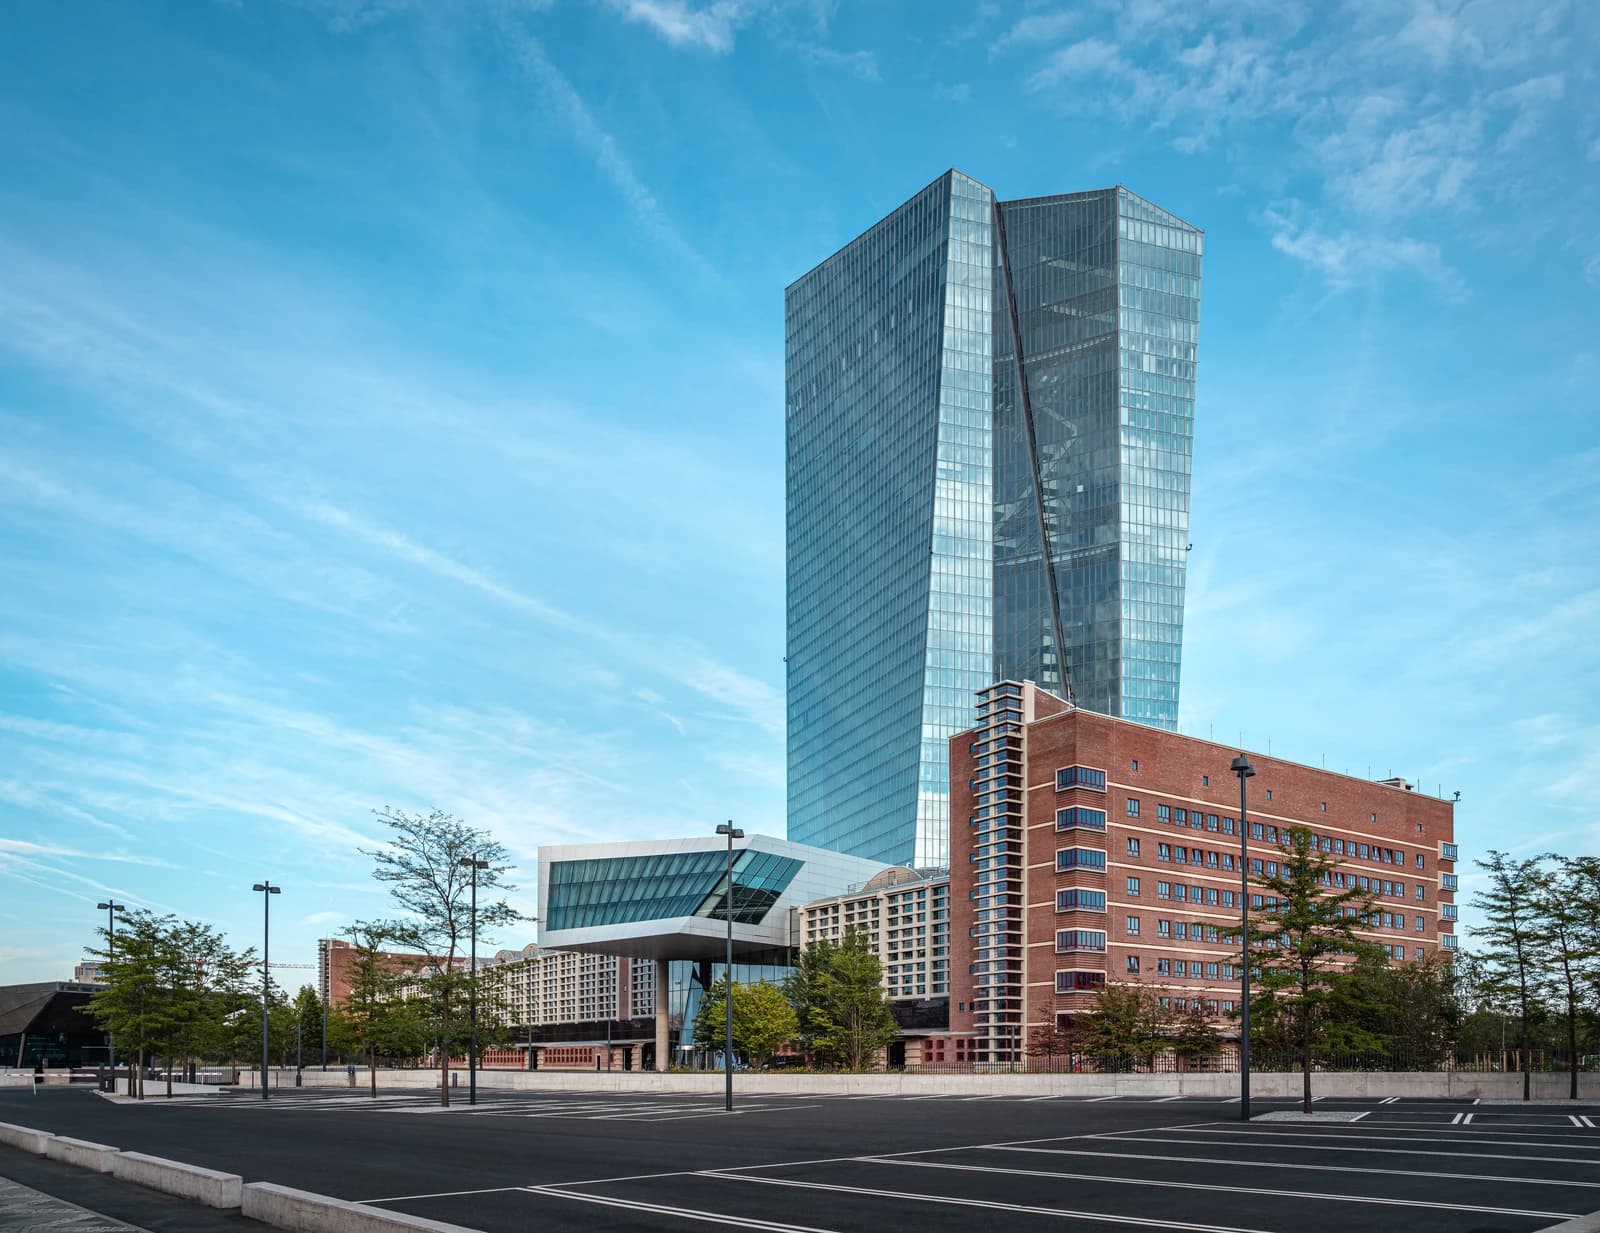
The European Central Bank risks losing room to maneuver if high debt levels and the rise of non-bank lenders keep financial conditions fragile, ECB board member Isabel Schnabel said, a warning that matters because it goes to the heart of how far the central bank can ease without unsettling markets.
ECB Debt and Non-Banks Limit Rate-Cut Room
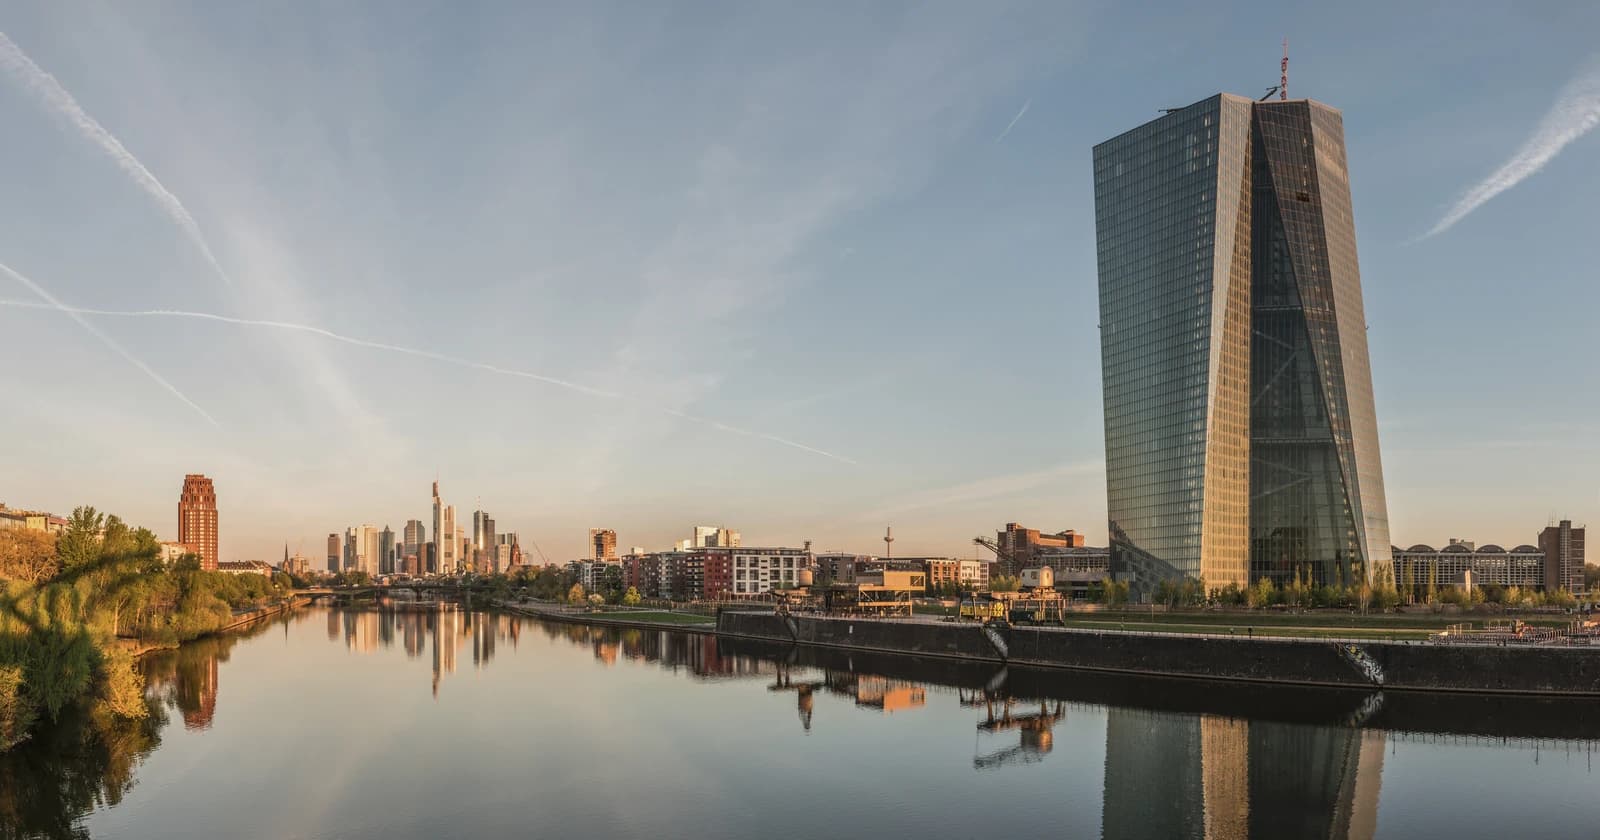
For investors, that is the key issue: the ECB may be able to start trimming rates, but it may not be able to cut as aggressively as growth-hungry borrowers hope. When leverage is already elevated, and more credit sits outside the traditional banking system, policy moves can have faster and messier spillovers. That makes every rate decision more consequential for sovereign borrowers, companies and financial stocks across Europe.
Sentiment Indicators
The backdrop is already uncomfortable. U.S. benchmark yields are still near 4.8% and the Fed funds rate is just under 3.9%, keeping global financing conditions tight. The ECB is operating in an environment where debt servicing costs remain sensitive to even modest shifts in rates, and where eurozone credit markets are increasingly shaped by funds, private lenders and other non-bank institutions that do not respond to policy in the same way as commercial banks.
That matters economically because central banks rely on transmission: a cut is supposed to ease lending conditions, support investment and help households and businesses breathe a little easier. But if the private credit ecosystem has grown large enough, the ECB may find that lower policy rates do not translate cleanly into easier financing. Worse, if debt loads are high, the central bank may hesitate to tighten for fear of causing stress, even if inflation proves sticky. That is how policy flexibility gets constrained.
The market reaction helps explain the tension. U.S. long bonds have been firming, with the iShares 20+ Year Treasury Bond ETF around $81.92 and Adalytica’s U.S. Treasury trade signal showing extreme greed, while the euro trades near $1.12 against the dollar. That combination suggests investors are still trying to handicap a world of slower growth, stubborn debt burdens and uneven policy support. In Europe, the same backdrop can be read as a reminder that rate relief may come, but not in a straight line.
Bank investors should watch this closely. Higher-for-longer rates can support net interest margins for a while, but they also raise credit risk and can expose weaker borrowers. Non-bank lenders, meanwhile, may continue to gain share if banks remain conservative, but they also face funding and refinancing risk when markets turn. The winners are likely to be the strongest lenders and the best-capitalized borrowers; the losers are highly leveraged balance sheets that need policy to do too much.
Schnabel’s warning is ultimately a reminder that central banking is no longer just about inflation and growth. In a world of heavy debt and sprawling shadow credit, the ECB may have less freedom than markets assume. That makes European credit selection, not just direction on rates, the more important long-term investing question.
| Entity | Gains | Losses |
|---|---|---|
| Strong European banks | ▲Wider margins, safer borrowers | ▼Less policy support if growth weakens |
| Non-bank lenders | ▲More lending share | ▼Higher refinancing risk |
| Highly leveraged borrowers | ▲Easier funding if cuts come | ▼Tight conditions if ECB hesitates |
| ECB | ▲Greater caution on stability | ▼Less room to cut freely |