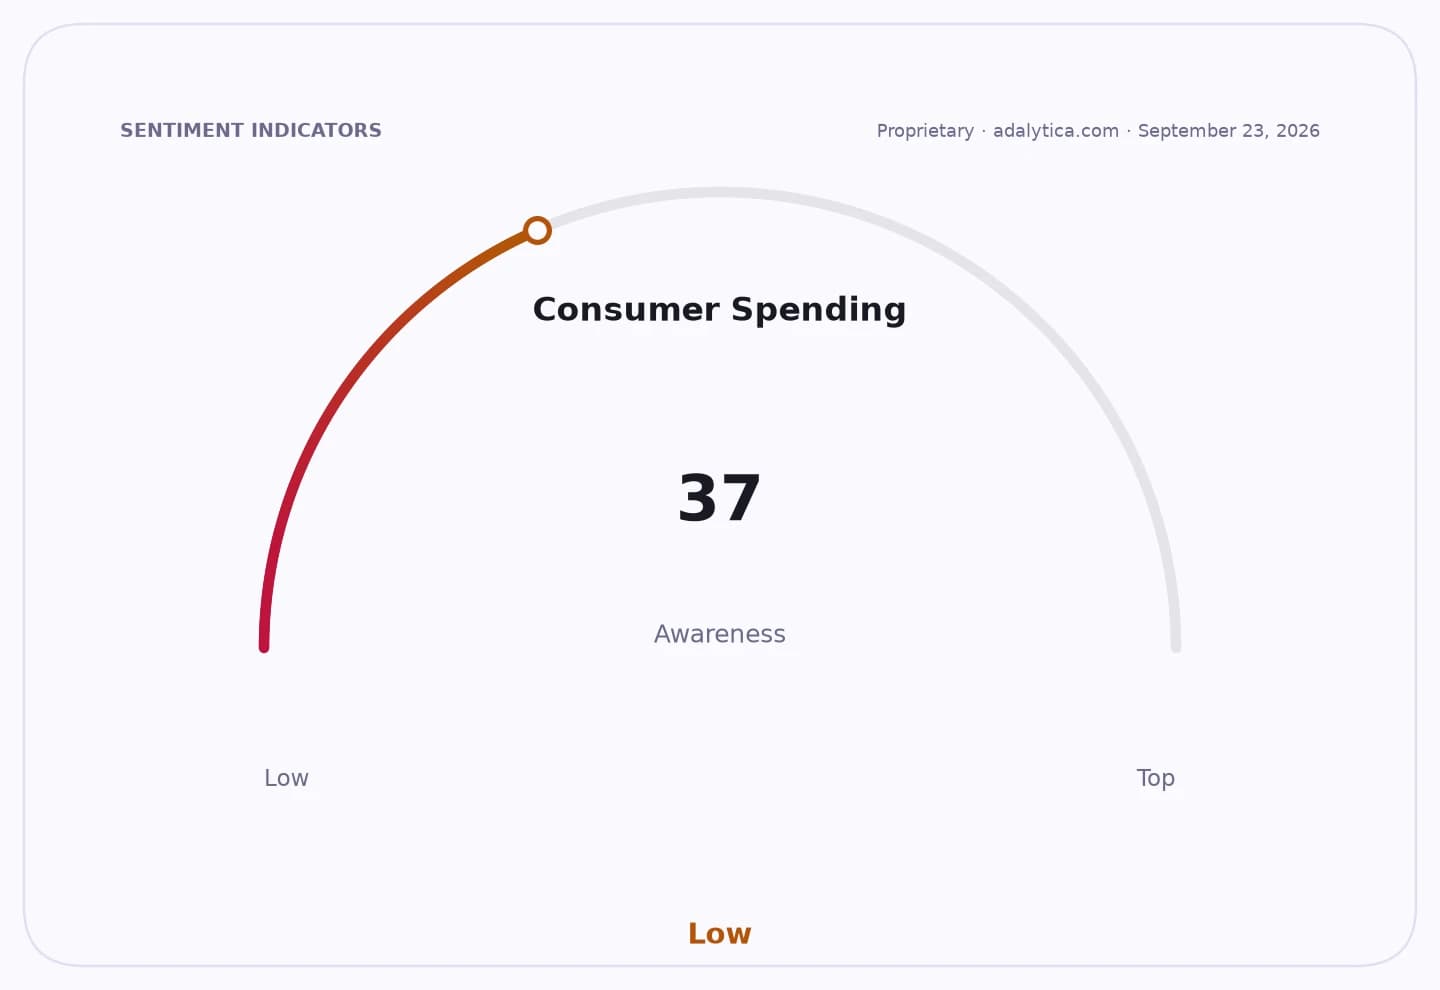
European households are spending nearly half their budgets on food, housing, energy and transport, underscoring how inflation and higher utility costs are squeezing disposable income and forcing consumers to shift money toward smaller discretionary buys rather than broad-based spending cuts.
EU households spend 46% on essentials

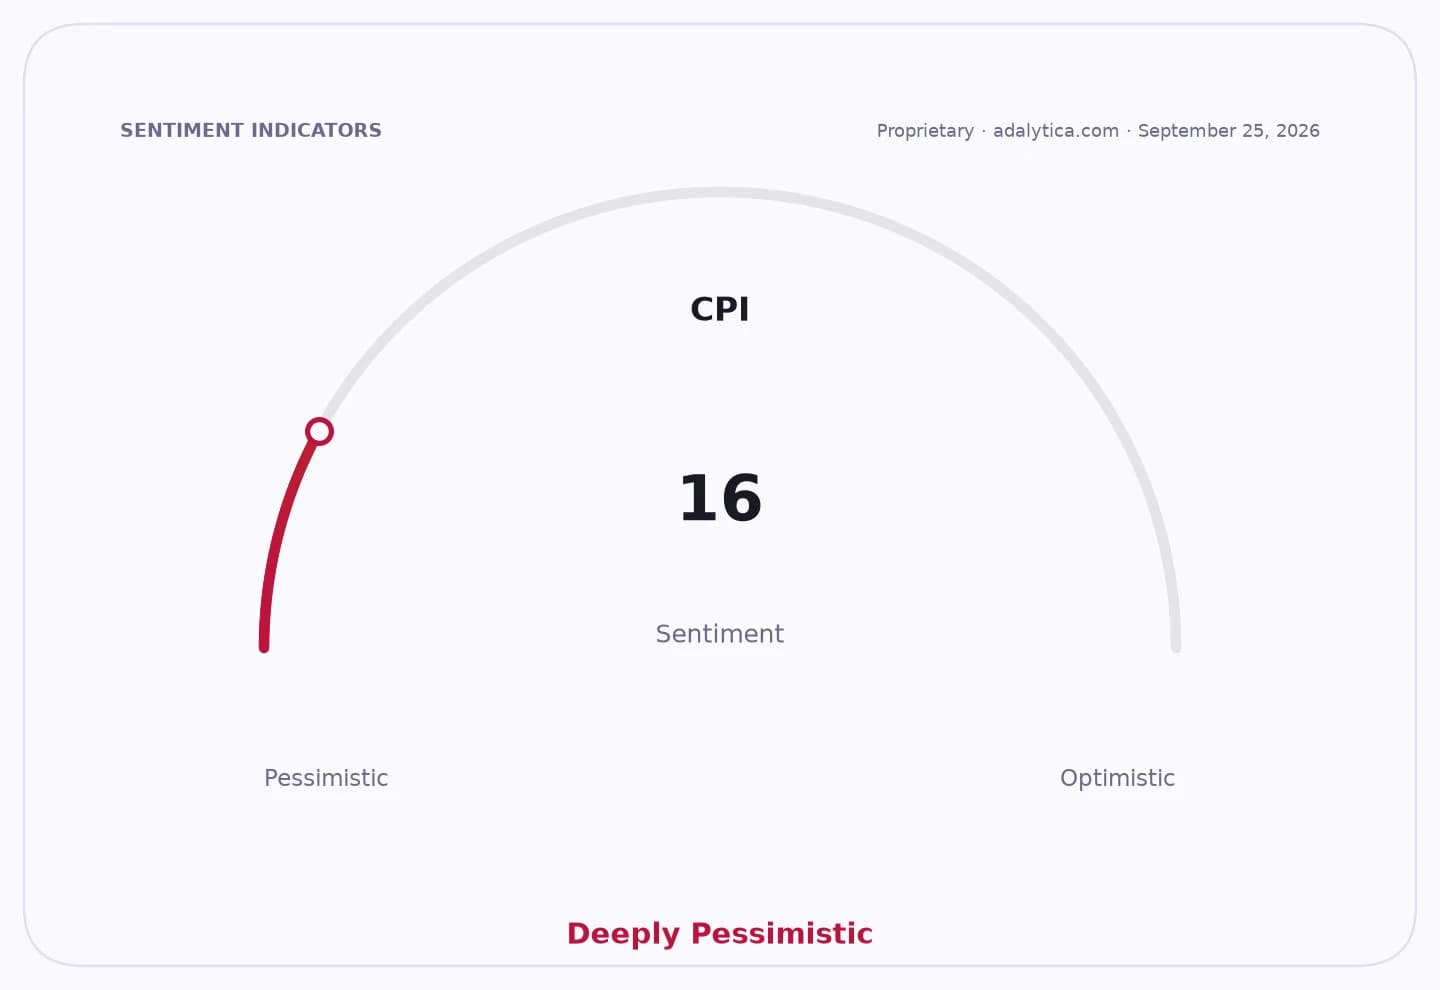
Those essentials account for about 46% of every euro spent in the EU, according to Eurostat-based data, making them the biggest economic constraint on household demand. With euro area inflation at 3.3%, the highest in three years, and energy costs up 14.3%, the data show that sticky living costs are still dominating family finances even as price pressures ease from their peaks.
For investors, that matters because the composition of spending is as important as the headline inflation rate. When housing, groceries and transport absorb so much of the household budget, demand becomes less elastic in staples and more selective in discretionary categories, favoring firms tied to affordable food, utilities and everyday mobility while pressuring categories that rely on broad consumer confidence.
The spending pattern also helps explain why Europe’s consumer recovery remains uneven. Eurostat said recreation, sport and culture saw the biggest increase in budget share, up 1.2 percentage points between January 2025 and January 2026, while restaurants and hotels rose 0.3 percentage points and education 0.1 point.
That shift suggests higher-income households are still able to protect lifestyle spending even as they trim elsewhere. At the same time, transport’s share of spending fell 0.4 percentage point and information and communication dropped 0.3 point, showing how families are cutting back on some recurring costs to preserve room for dining out, entertainment and wellness.
The split is economically important because lower-income households have far less flexibility: they are forced to absorb higher food and utility bills without much room to reallocate spending. That means the benefits of any consumption rebound are likely to be concentrated among middle- and higher-income consumers, rather than spreading evenly across the bloc.
For markets, the message is that Europe’s consumer base is not collapsing, but it is fragmented. Staples, public transport, food retailers and utility-linked businesses remain backed by necessity demand, while discretionary names tied to travel, leisure and culture may see pockets of resilience even in a high-cost environment.
Further pressure will come from ongoing energy and geopolitical risks, which have kept housing and utility costs elevated and could slow any normalization in household purchasing power. The next read on consumer spending and inflation will show whether Europe’s families keep trading down on essentials or whether stubborn cost-of-living pressures begin to bite into even discretionary outlays.
| Entity | Gains | Losses |
|---|---|---|
| Food, housing, energy and transport providers | ▲steady necessity spending | ▼tighter household budgets |
| Discretionary leisure and hospitality | ▲pockets of resilient demand | ▼lower-income consumers |
| Lower-income households | ▲none | ▼limited ability to reallocate spending |
| Middle- and higher-income households | ▲ability to protect lifestyle spending | ▼pressure from higher living costs |