Europe’s shoulder season is turning into the smartest trade in travel, and that matters because it shifts bookings from peak-summer chaos to a longer, more profitable demand window for online travel platforms, hotels and airlines.
Europe shoulder season boosts travel bookings
For investors, the key is not the postcard appeal of Venice, Nice or Barcelona. It’s the economics. When travelers move trips into March-to-May and September-to-November, they tend to book earlier, hunt for value and fill inventory that would otherwise sit underutilized outside peak months. That supports pricing power for Expedia, Booking and Airbnb while reducing the all-or-nothing dependence on midsummer demand. It also broadens the operating runway for European carriers, hotel groups and attraction operators that can monetize steady traffic without relying solely on the July-August surge.
The travel thesis is already visible in the market. Expedia has spent the year moving above its 200-day average and still trades well above that long-term trend, a sign that investors are rewarding durable demand even after recent volatility. Booking has also shown the kind of cyclical resilience that comes from owning distribution rather than inventory alone, while Airbnb remains the purest lever on flexible, lower-cost stays that fit shoulder-season behavior. The broader point: consumers are still traveling, but they are becoming more value-conscious and more flexible about timing.
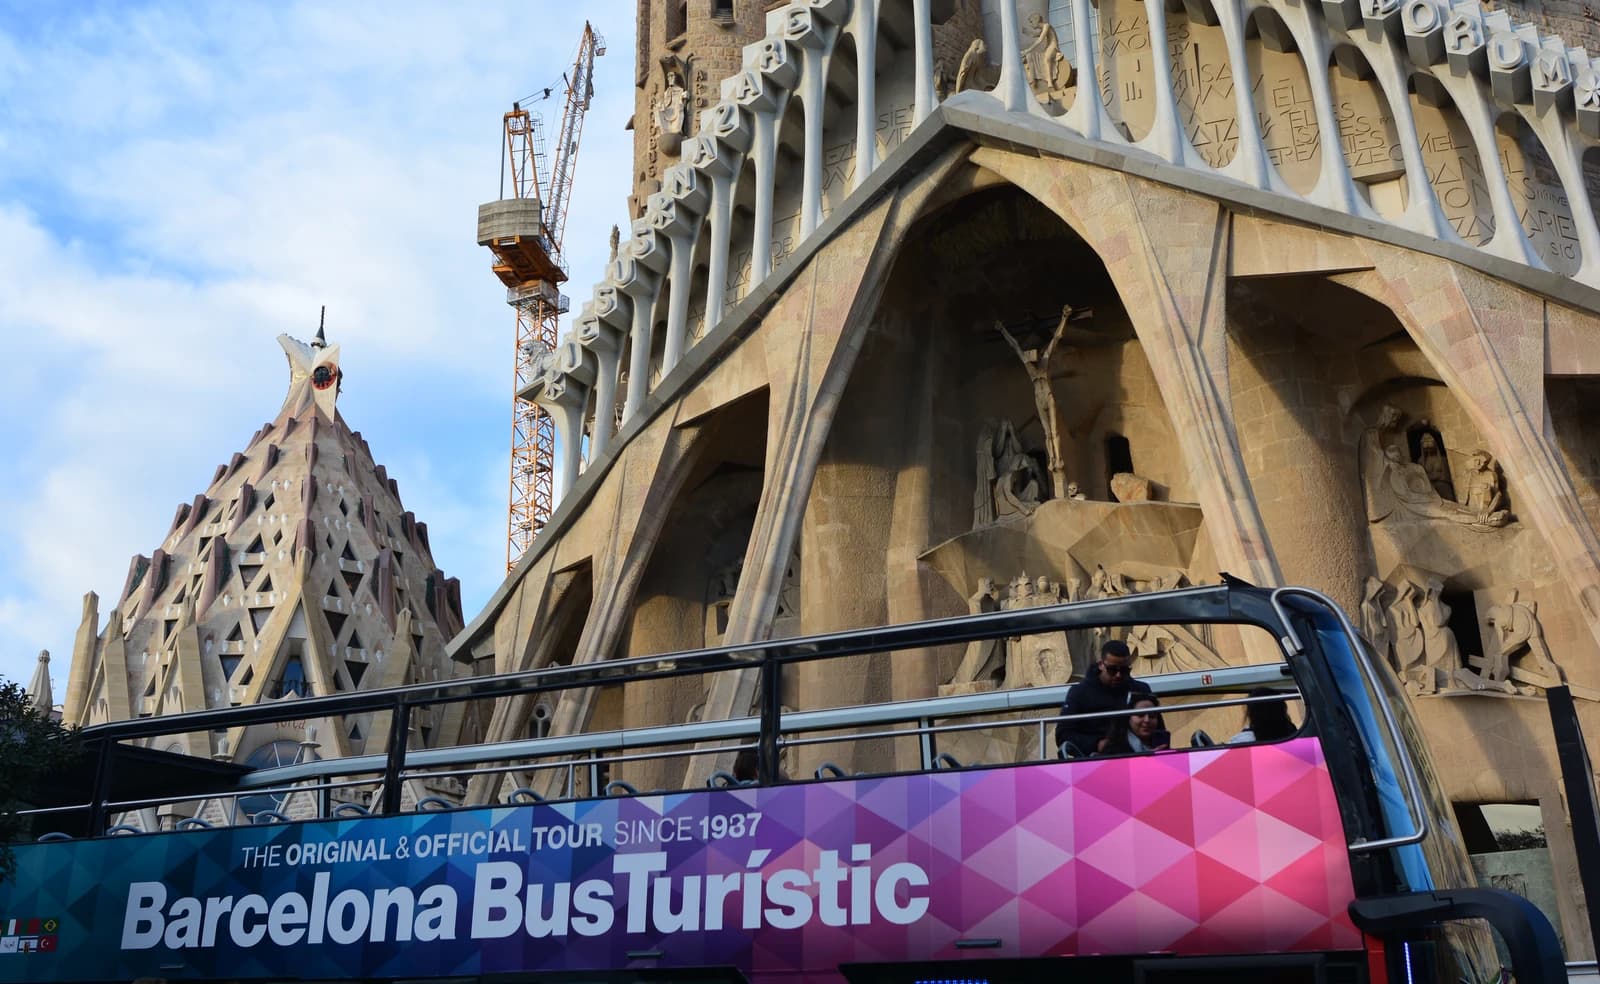
That is exactly why shoulder season is attractive. Venice, which draws roughly 30 million tourists a year, is far less congested in spring and fall. Nice still offers warm weather in September and October, but at lower accommodation costs than the summer crush. Barcelona, meanwhile, can absorb visitors outside peak heat while forcing travelers to book hotels rather than scarce vacation rentals as housing restrictions tighten. Munich and Lisbon fit the same pattern: strong destination appeal, but better economics when crowds thin and rates soften.
The market underestimates how much this behavior favors the platforms that capture flexible demand. Expedia and Booking benefit when travelers compare prices across airlines, hotels and packages. Airbnb benefits when cost-conscious travelers trade up from expensive city-center hotels to apartments and alternative stays. And because shoulder season extends beyond Europe, the same pattern supports global travel demand into the second half of the year, especially as holiday airfares rise and consumers search for smarter alternatives.
My thesis is simple: the next leg in travel will not come from more people traveling once a year, but from travelers spreading trips across more of the calendar. That is an asymmetric setup for the best online travel operators and the accommodation platforms with the strongest pricing and distribution engines. Investors looking for a durable travel theme should be positioning around that shift now.
| Entity | Gains | Losses |
|---|---|---|
| Expedia | ▲More flexible bookings | ▼Peak-season dependence |
| Booking | ▲Higher-value distribution | ▼Direct hotel pricing power |
| Airbnb | ▲Budget-conscious travelers | ▼Scarce summer inventory |
| European hotels | ▲Longer demand season | ▼Empty off-peak rooms |