Expand Energy’s push to become a natural gas powerhouse is arriving at a tricky moment for the trade: oil is surging, the dollar is wobbling and credit markets are still pricing in a world where commodity swings can turn quickly. For investors, that matters because Expand Energy’s growth story depends on disciplined capital spending and a constructive gas market, while a broader energy rotation can either amplify returns or expose how fragile the rally in gas producers really is.
Expand Energy Stock Rises on Gas Powerhouse Plan
That tension is showing up across the sector. WTI crude has climbed to about $86.74 a barrel in the latest read, up sharply from $83.99 only days earlier and far above levels seen in April. At the same time, the high-yield credit spread, a key barometer of risk appetite, has tightened to 2.69 percentage points from 3.13 in early August, suggesting markets are willing to fund energy names for now. But the move in oil is not automatically a tailwind for gas-focused producers like Expand Energy. It can also pull capital toward integrated and oilier names, leaving dry-gas stories fighting for attention unless gas prices and volume growth justify the premium.
Sentiment IndicatorsⓘProprietary · adalytica.com · August 26, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Expand Energy’s shares have recovered to $94.66 from $87.99 in late July, with the stock now trading back above its 50-day moving average and with RSI readings suggesting momentum has improved. That rebound matters because it shows investors are still willing to pay for the company’s scale story after a rough summer. But the shares remain below the 200-day moving average, a reminder that the market has not fully bought into a durable rerating yet.
The bigger issue is the commodity backdrop. Natural gas sentiment, using Adalytica’s market trade signals, is neutral at 48, even as awareness is near extreme greed at 98. In plain English: the market is paying attention, but conviction is not matching the hype. That is exactly the kind of setup that can create opportunity — or disappointment — for a company trying to build a natural gas powerhouse. If gas prices firm and production discipline holds, Expand Energy can turn scale into cash flow leverage. If not, growth may look like capital intensity without enough margin expansion.
Oil WTI vs EXEadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse

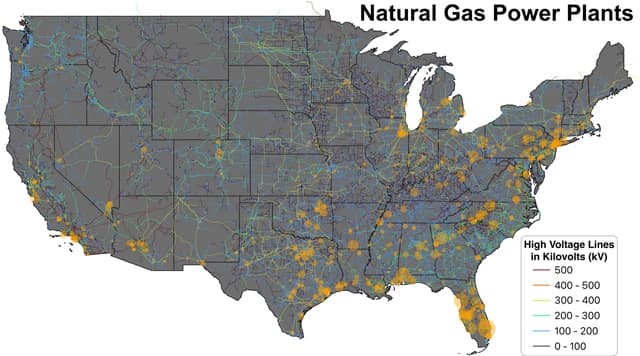
The investment case therefore hinges on second-order effects. Expand Energy is not just a producer; it is a bet on whether the market starts rewarding gas as a strategic fuel for power demand, LNG exports and AI-driven electricity growth. That theme is still underappreciated. Data center buildouts, grid constraints and the need for reliable baseload power are structural supports for gas over the next several years. In that world, the companies with the best acreage, the lowest lifting costs and the most disciplined hedging strategy should command the premium — not the ones simply chasing volume.
That is why Expand Energy deserves attention now. The market underestimates how quickly a higher-demand, tighter-supply gas environment can reprice the entire group, especially if oil stays firm and capital keeps flowing into energy. But the same setup also means investors should watch for any sign that growth is being bought too expensively or that gas pricing fails to follow through. The best trade here is to own the highest-quality gas leverage, not the most aggressive growth narrative.
| Entity | Gains | Losses |
|---|---|---|
| Expand Energy (EXE) | ▲Scale premium if gas tightens | ▼Multiple compression if growth disappoints |
| Gas bulls | ▲Better cash flow leverage | ▼Narrative fades without price support |
| Oil-focused energy names | ▲Capital rotation into hydrocarbons | ▼Less attention if gas rerates |
| Credit investors | ▲Tighter spreads, better funding mood | ▼Wider spreads if commodity volatility spikes |