Faisal Islamic Bank of Sudan has expanded its digital banking offer by letting new and existing customers open flexible U.S. dollar accounts and activate Visa Pay, a move that could deepen access to hard currency and online payments in a country where dollar liquidity and payment rails remain key constraints.
Faisal Islamic Bank of Sudan adds USD accounts, Visa Pay
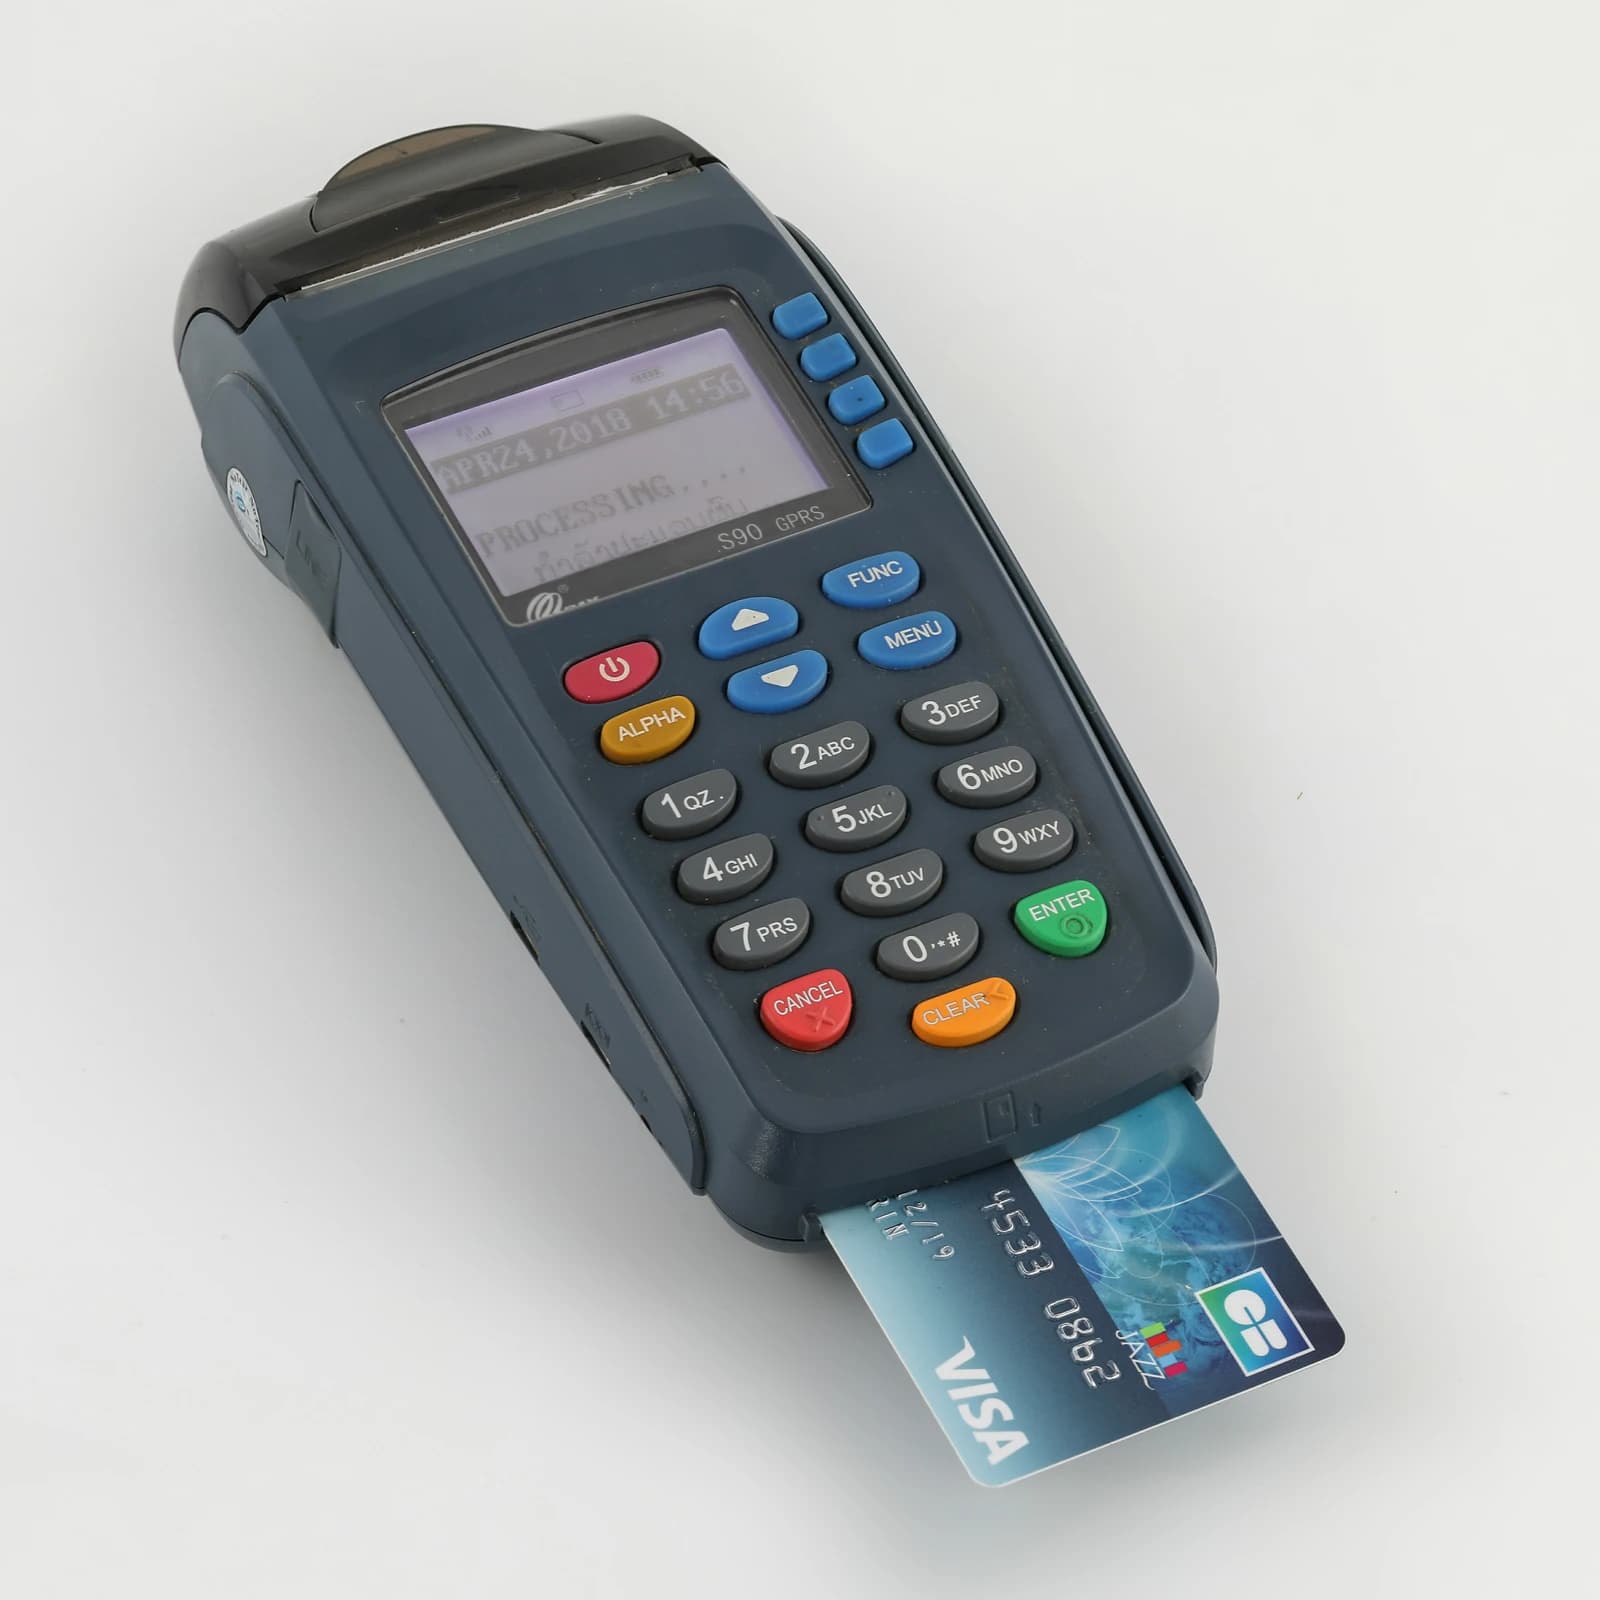
The bank said prospective customers can open the account online through a dedicated platform without visiting a branch, while existing clients can complete the process in person. Visa Pay can then be activated within 24 hours, giving account holders the ability to receive dollar transfers, deposit cash in dollars at branches and use a free virtual Visa card for online shopping and payments.
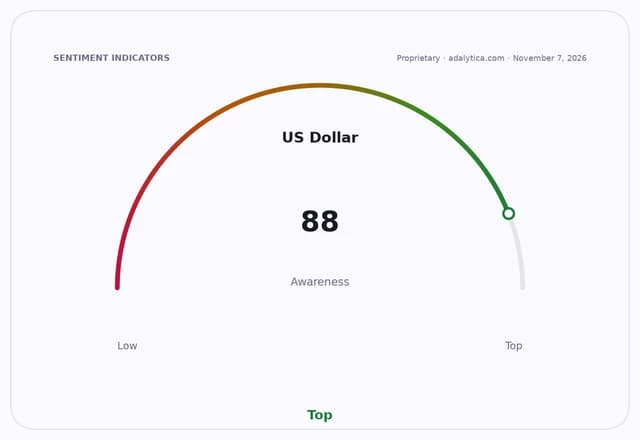
Sentiment Indicators
For Sudanese households and businesses, the significance is less about a new product than about access. In economies where local-currency volatility, cross-border payment frictions and cash handling costs are persistent, a bank-linked dollar account can serve as a practical store of value and a gateway to international commerce. The ability to receive funds directly in dollars and spend through a virtual card broadens the bank’s utility beyond traditional deposits.
The offering also fits a wider push by banks to move core services onto digital channels. By allowing non-customers to onboard remotely, Faisal Islamic Bank is lowering the operational burden on branches and widening its reach in a market where physical access can be difficult. That may help it attract deposits, especially from customers looking for faster access to foreign-currency balances and e-commerce tools.
For investors and competitors, the development underscores how banks are competing on payment functionality rather than rates alone. In markets under pressure from inflation, currency shortages or capital controls, the institutions that can combine deposit gathering with digital transfer and card services often gain the strongest customer retention. The model also creates a more recurring revenue base if transaction activity scales.
There are limits, however. The proposition depends on reliable digital infrastructure, foreign-currency funding and continued trust in the banking system. If dollar inflows are thin, or if transaction services are disrupted, the appeal of the account could fade quickly. Still, the move suggests Sudanese banks are adapting to customer demand for hard-currency access and digital convenience, with Visa Pay now part of the competitive toolkit.
| Entity | Gains | Losses |
|---|---|---|
| Faisal Islamic Bank of Sudan | ▲more deposits and users | ▼higher digital-service costs |
| Customers seeking dollar access | ▲easier USD accounts and payments | ▼branch-based banking friction |
| Visa Pay / virtual card users | ▲faster online spending in dollars | ▼reliance on bank and network uptime |
| Rival Sudanese banks | ▲pressure to match digital FX services | ▼weaker customer retention |