Indonesia’s migrant-worker remittance market is emerging as a larger financial pipeline, with money sent home by Pekerja Migran Indonesia reaching Rp288 trillion in 2025, up about 14% from a year earlier. That scale is now forcing regulators and industry players to tighten cross-border payment safeguards as digital transfers accelerate and the risk of fraud, compliance lapses and operational failures rises with volume.
Indonesia Remittance Market Reaches Rp288 Trillion
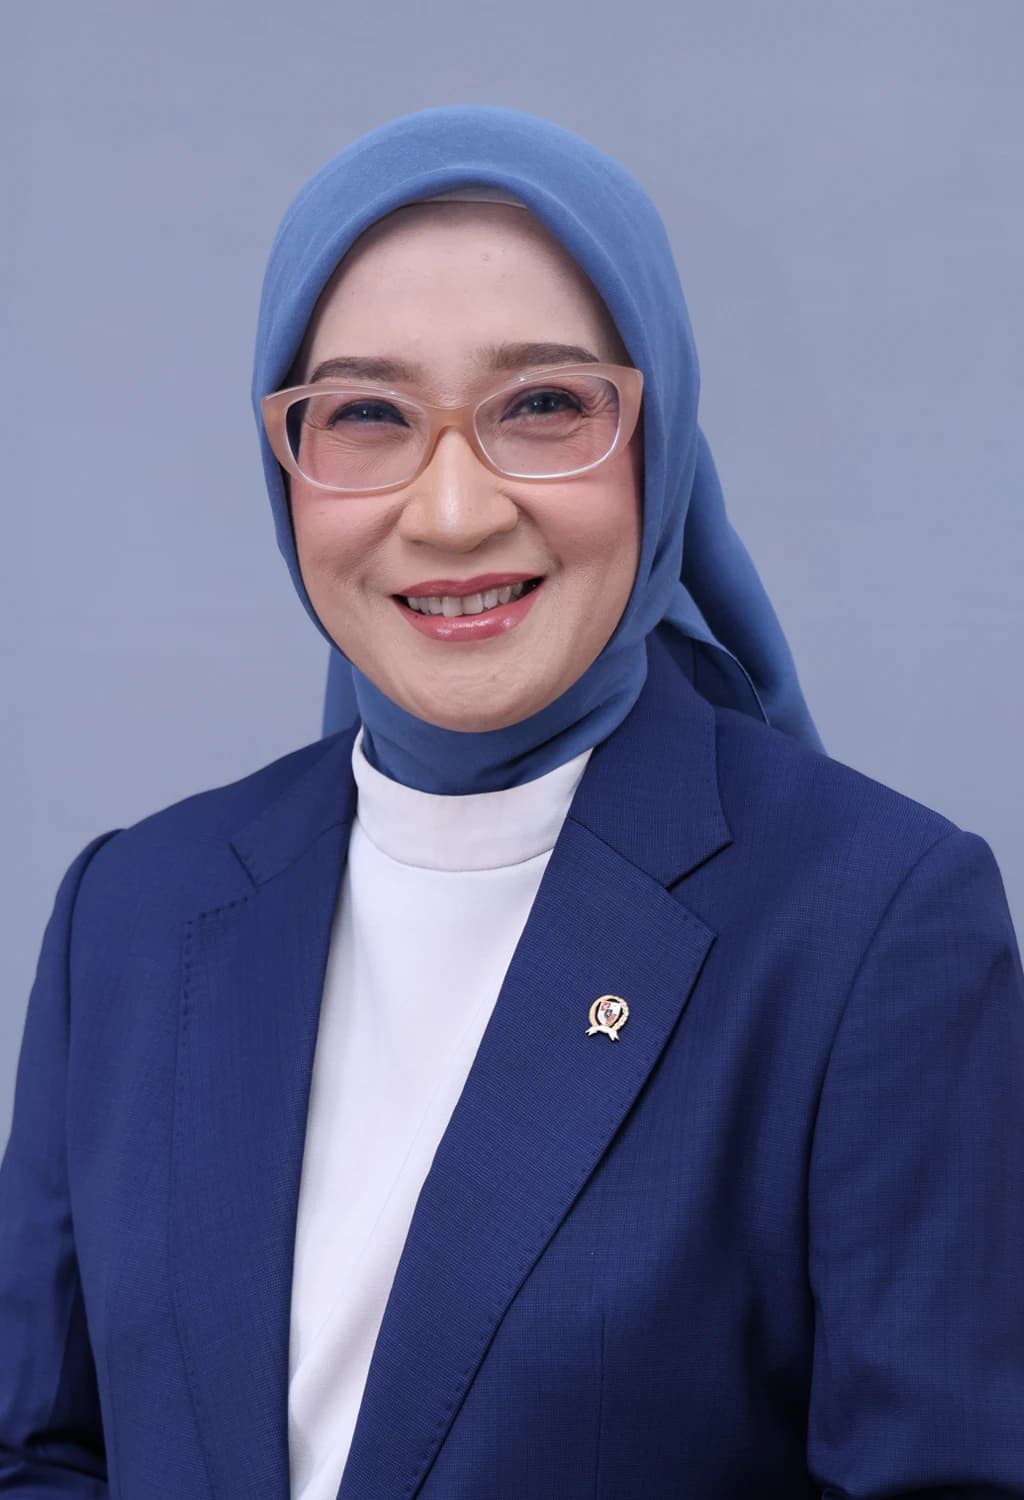
Bank Indonesia and the Indonesian Money Transfer Providers Association, or APPUI, used the Indonesia Remittance Forum 2026 in Jakarta to push for stronger service standards and legal compliance across the industry. BI Deputy Governor Filianingsih Hendarta said remitance services must grow “acceleration” while remaining resilient, calling for systems that are fast, easy, cheap, safe and reliable — the CEMUUAH standard she introduced for today’s transfer market.
The economic stakes are substantial. Remittances are a key source of household income for migrant families and a steady foreign-currency inflow that helps support consumption in local communities. At Rp288 trillion, the flow is big enough to matter for the broader payments ecosystem, making reliability and trust a financial stability issue rather than just a consumer-protection concern.
For investors, the message is that the remittance business is becoming more regulated and more competitive at the same time. Operators that can scale digital services while meeting compliance and security standards are positioned to gain market share, while weaker players face higher costs, tighter oversight and reputational risk.
APPUI chairman Eddy Hadiyanto said firms cannot compete only on speed and low fees, arguing that the security of funds sent to families is the core asset. The association also wants clearer rules that support licensed operators and curb an uneven playing field.
The next catalyst is whether BI and industry groups turn these standards into tougher operating requirements for cross-border transfer providers, potentially raising the bar for technology investment, customer verification and settlement controls.
| Entity | Gains | Losses |
|---|---|---|
| Licensed remittance firms | ▲Stronger trust, clearer rules | ▼Higher compliance costs |
| Migrant-worker families | ▲Safer, faster transfers | ▼More friction in weak systems |
| Bank Indonesia / regulators | ▲Better system resilience | ▼Added oversight burden |
| Noncompliant operators | ▲— | ▼Tighter scrutiny, lost share |