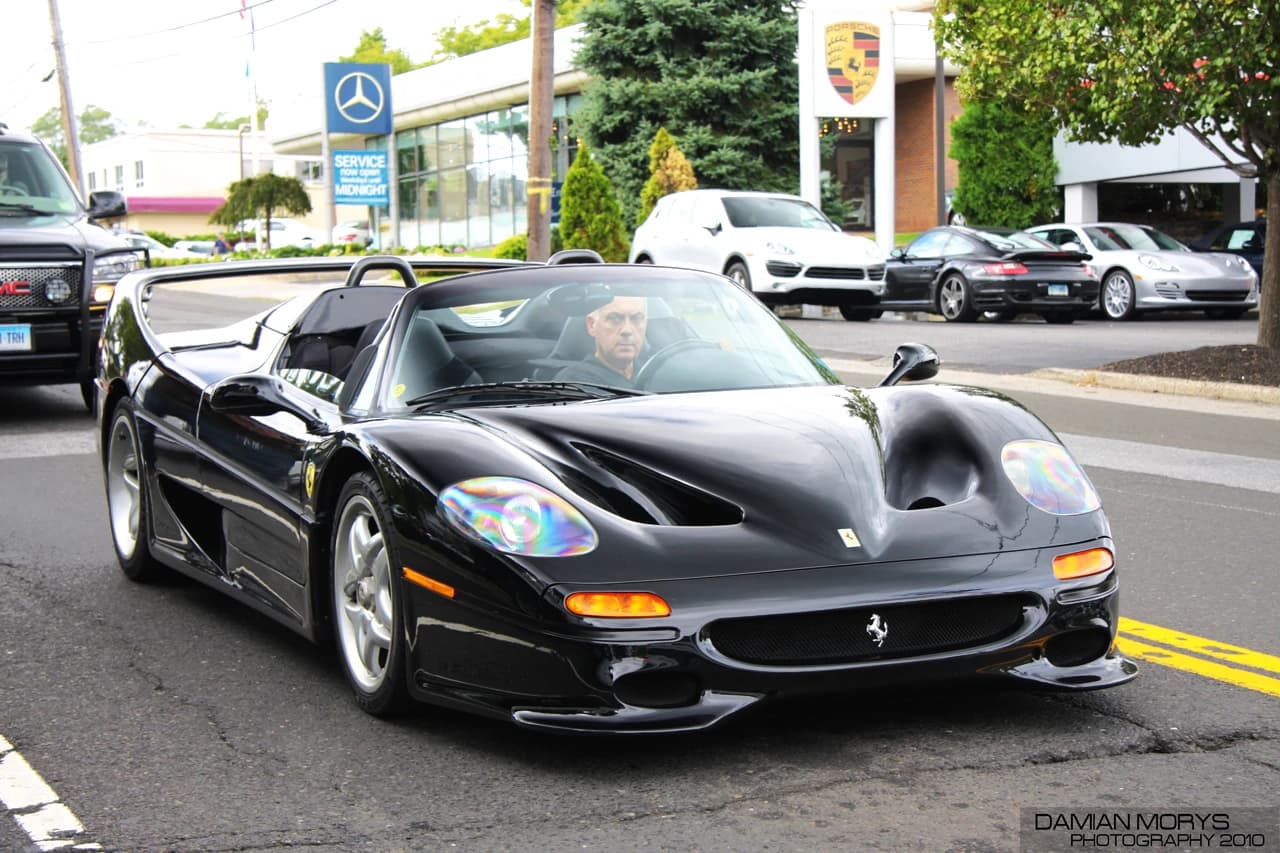
Ferrari’s stock pushed to a fresh 2026 high on Nov. 3, a sign that investors remain focused on the company’s rare pricing power and long-term earnings engine rather than headline-grabbing car fraud stories.
Ferrari Stock Hits Fresh 2026 High
The shares closed at $414.77, up from $403.09 the day before and well above the 50-day moving average of about $402.56, while the 200-day moving average sat near $368.55. The move came on heavier volume and with the relative strength index at 71.2, a reading that often points to strong momentum in conventional technical analysis. For long-term investors, the bigger message is that Ferrari remains one of the market’s most durable luxury franchises, even when broader sentiment around high-end consumer goods is uneven.
That matters economically because Ferrari is not just selling cars — it is selling scarcity, status and margin. In a world where many consumer brands rely on discounts to clear inventory, Ferrari has built a model around waiting lists, tightly controlled production and deep brand loyalty. That gives it unusual resilience in a slower global economy and helps explain why the stock can keep attracting buyers even as headlines about luxury-car fraud or consumer caution ripple through the market.
The wider context is less about one isolated crime and more about the health of the luxury ecosystem. Fraud cases can dent trust at the margins, but they do not change the fact that ultra-high-end buyers still want differentiated assets, whether that means a Ferrari, a watch or a rare collectible. For investors, that makes Ferrari a different kind of luxury play: less dependent on fashion cycles and more tied to brand equity, disciplined supply and pricing power.
There is still a valuation risk. After a strong run, Ferrari shares are no bargain, and short-term traders could easily point to the overbought RSI reading as a reason for caution. But buy-and-hold investors tend to care more about whether the company can keep compounding revenue and free cash flow over the next five to 10 years. On that score, Ferrari continues to look like a category leader with room to keep rewarding patience.
For investors, the takeaway is simple: the stock’s latest move looks more like confirmation of Ferrari’s long-term moat than a reaction to a news cycle. It is worth watching, but the bigger story is that premium brands with real scarcity can keep performing even when the headlines are messy.
| Entity | Gains | Losses |
|---|---|---|
| Ferrari shareholders | ▲Momentum and brand premium | ▼Little in the near term from fraud headlines |
| Long-term buyers | ▲Exposure to a durable luxury compounder | ▼Must pay up after the rally |
| Short-term traders | ▲Volatility to trade | ▼Risk of chasing an overbought stock |
| Fraud victims / investigators | ▲More attention to controls | ▼Trust and resources strained |