French savers are putting money back into Livret A accounts, but the rebound is modest and may not last, underscoring how higher regulated rates are colliding with squeezed household purchasing power.
France Livret A deposits rebound modestly in August
After six difficult months, net deposits into the Livret A turned positive again in July and stayed in the black in August, when households added 460 million euros more than they withdrew, according to Caisse des Dépôts data. The closely watched savings vehicle, a cornerstone of French household cash management, had suffered its worst first-half performance in nearly two decades before the government-linked rate reset lifted its yield to 1.7% on Aug. 1.
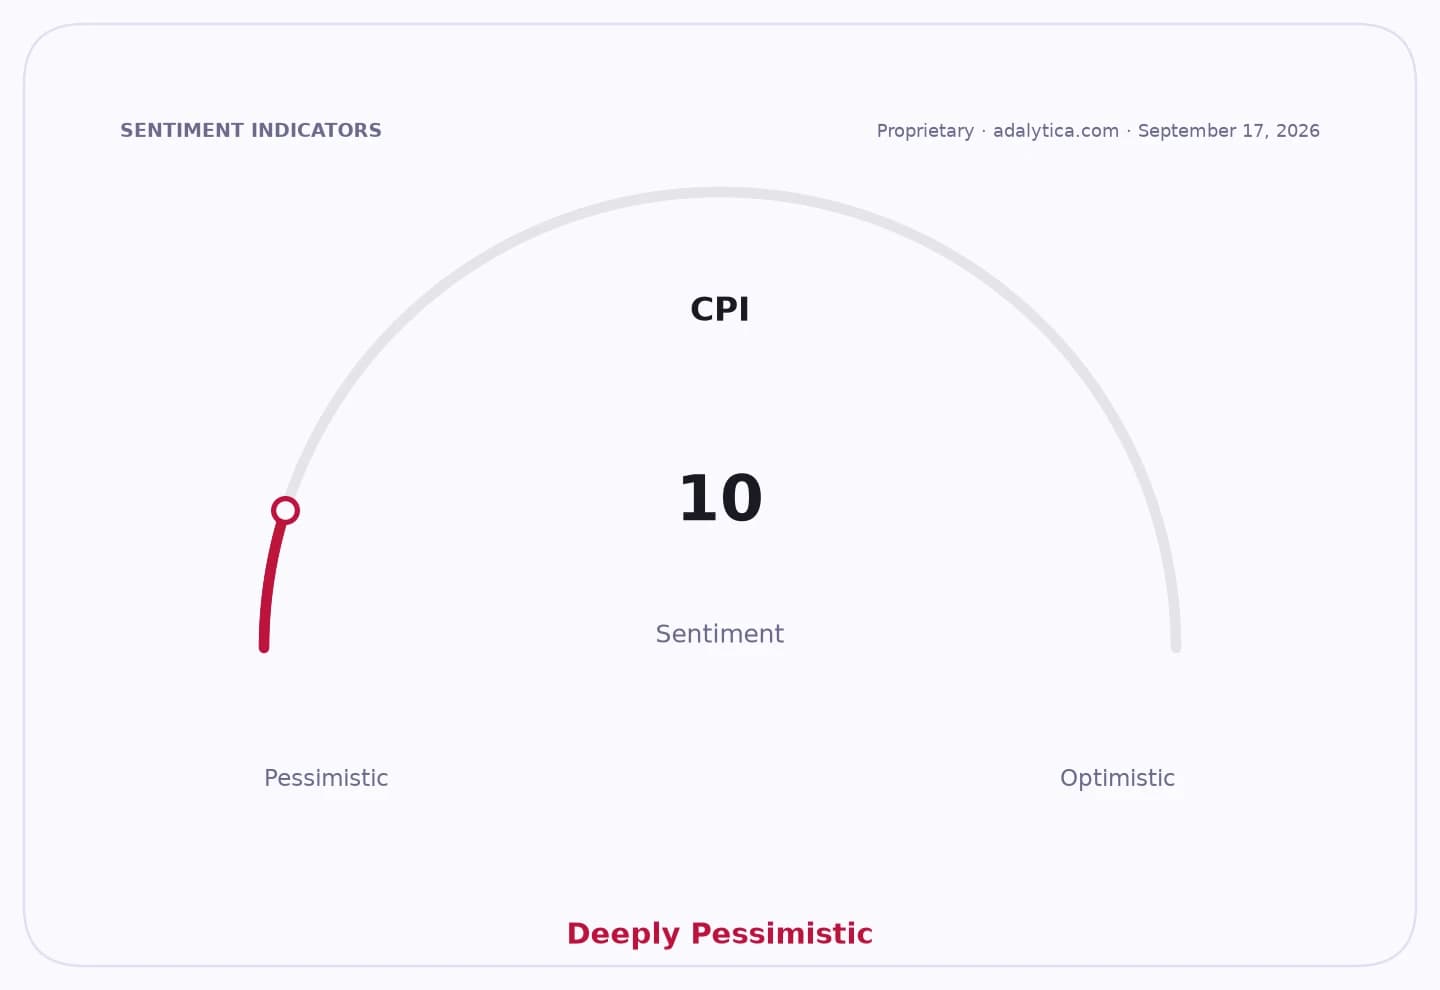
Sentiment IndicatorsⓘProprietary · adalytica.com · September 27, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters because the Livret A is more than a savings account: it is a barometer of how French households are balancing caution, inflation and income stress. When flows recover, it usually means savers are once again willing to park cash in guaranteed, tax-free products. When they falter, it often points to households being forced to spend rather than save, or to looking elsewhere for better returns.
The August improvement was helped by the higher rate, but it was still weak by historical standards. During the 2023-2025 period, when the Livret A rate sat at 3% for 24 months, inflows were much stronger. The sister LDDS account also recorded a small net inflow of 80 million euros in August, while the more income-targeted LEP stopped a string of outflows with a 60 million-euro gain.
For investors, the message is not that French savings are booming. It is that regulated savings remain caught between two opposing forces, as Philippe Crevel of the Cercle de l’épargne put it: better returns on paper, but weaker household purchasing power in practice. Energy prices remain elevated, and the household savings rate fell to 17.2% of disposable income in the second quarter from 17.9% in the first, a sign that consumers are under pressure to dip into cash.
That creates a useful read-through for the broader French economy. If households keep favoring day-to-day spending over banked savings, it supports consumption in the near term but also signals tighter budgets and less room for discretionary purchases. If, on the other hand, regulated savings rates rise further without real income growth, the money may simply rotate back into deposits rather than into broader economic activity.
The biggest winner here is the safety-seeking saver, but only if the rate advantage lasts. The biggest loser is the household that is trying to save while absorbing higher living costs. For long-term investors, the key takeaway is simple: this is a reminder that in France, household liquidity is still highly sensitive to inflation and policy settings, and that can influence consumption, retail demand and the attractiveness of defensive savings products. Worth watching, not because the Livret A is explosive, but because it tells you how resilient French consumers really are.
| Entity | Gains | Losses |
|---|---|---|
| Livret A / LDDS savers | ▲Better guaranteed returns | ▼Lower household spending room |
| French banks / regulated savings system | ▲Deposit inflows stabilize | ▼Higher funding costs, tighter margins |
| French consumers | ▲Safer cash parking options | ▼Erosion from energy and living costs |
| Retailers / discretionary spenders | ▲— | ▼Softer spending if savings pressure deepens |