France’s mortgage market is tightening again as banks raise rates month after month, pushing some home loans close to 4% and shutting out more buyers across Lyon and the rest of the country.
France mortgage rates rise near 4% as lending tightens
That matters because housing affordability is deteriorating just as France’s financing backdrop turns less forgiving. Average mortgage rates have climbed to 3.50% on 15-year loans, 3.66% on 20-year loans and 3.75% on 25-year loans, according to broker Pretto, up sharply from 3.22% on 20 years in March and 3.25% in June.
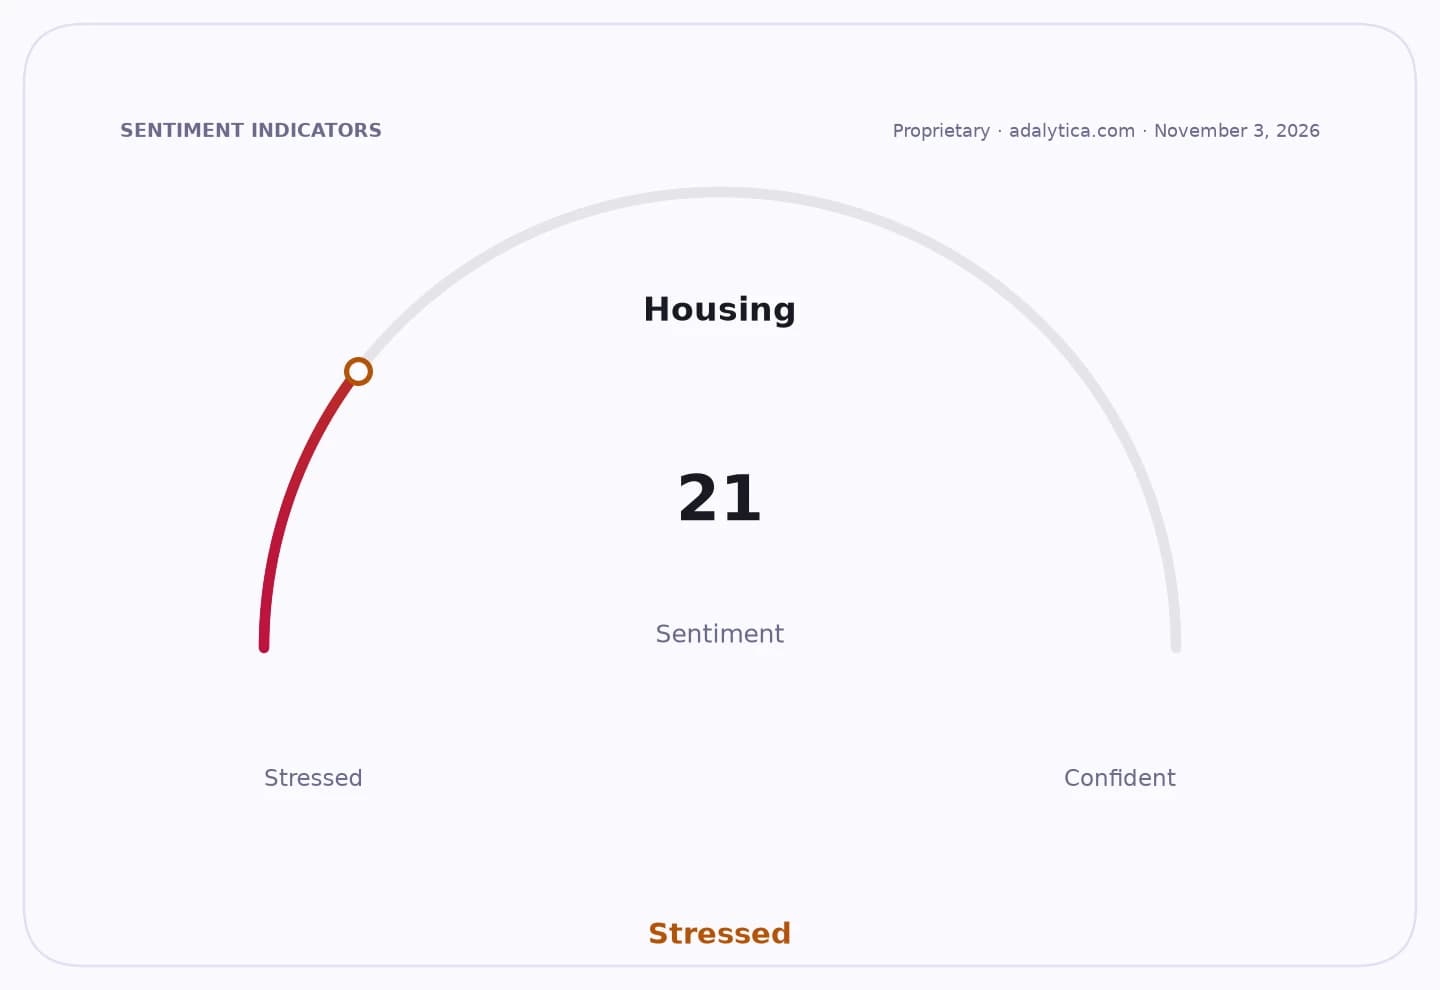
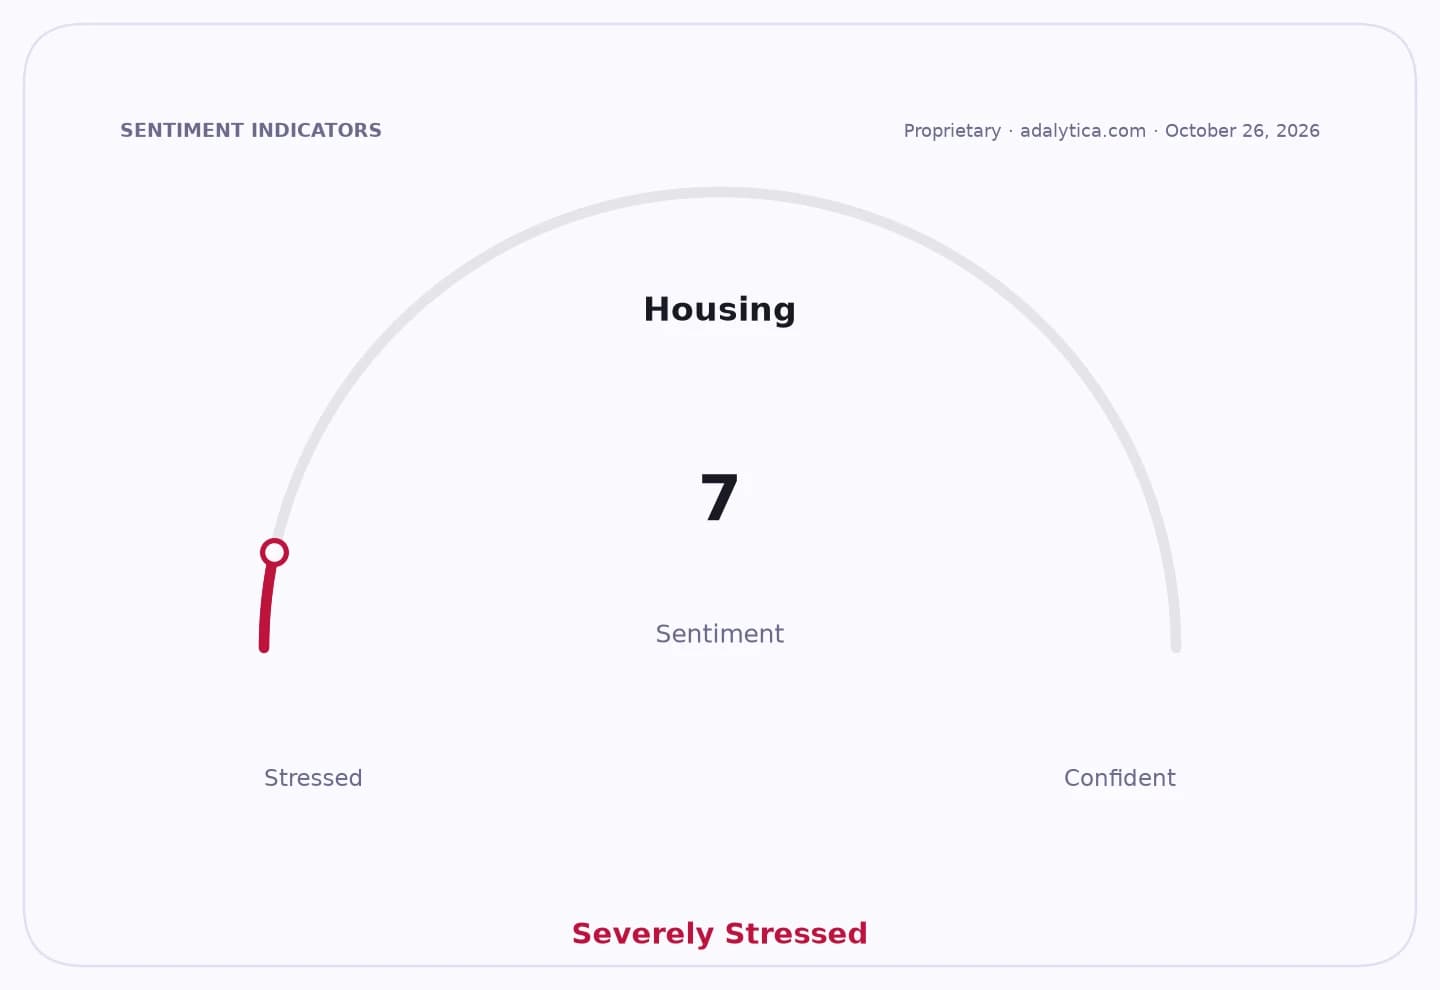
Sentiment Indicators
Lenders are passing through a more costly funding environment as the French state borrows at higher rates and the European Central Bank keeps monetary conditions tight. France’s 10-year borrowing cost hit 5.14% on Oct. 22, the highest since 2002, while brokers say banks have been lifting mortgage prices by 0.10 to 0.20 percentage point every month since summer.
The result is a deeper freeze in the housing market. Fewer buyers can clear underwriting thresholds, sellers are reluctant to cut prices enough to match the new reality, and transactions are stalling. FNAIM’s Rhône chapter says the market is “frozen,” with activity drying up rather than merely slowing.
The pressure is most acute for first-time buyers, lower-income households and borrowers already close to France’s 35% debt-service cap. Older applicants and people with health issues are also getting squeezed, because mortgage insurance can push total borrowing costs above France’s usury ceiling of 5.40%, making some loans impossible to approve.
If rates stay near 4%, about 230,000 households could be excluded from mortgage credit, according to broker simulations cited by Le Figaro Immobilier. The national loan market is already weakening, with the number of mortgages granted down 8.1% in the third quarter versus a year earlier, while Cafpi says loan applications have fallen 5% to 10% since the start of the school year.
For investors, the message is that France’s housing slowdown is no longer a regional issue but a broader macro drag. Weaker mortgage demand hits real-estate brokers, builders, banks and consumer spending, while the latest rise in sovereign borrowing costs adds to pressure on French assets and on policymakers already facing fiscal strain and political unrest.
The key catalyst now is whether banks keep lifting rates into year-end and whether regulators revisit the usury-rule framework if more borrowers are pushed out of the market. Absent relief, the country’s housing market looks set to remain stuck in low gear into 2027.
| Entity | Gains | Losses |
|---|---|---|
| Banks | ▲Wider loan pricing | ▼Lower mortgage volumes |
| Homebuyers | ▲Few rate-holdouts | ▼Higher monthly payments |
| First-time buyers | ▲Some with large deposits | ▼Limited access to credit |
| French housing market | ▲Potential price adjustment | ▼Frozen transactions |