Galantas Gold has locked in a US$10 million advance payment facility with Ocean Partners tied to dore purchases, a financing move that matters because it gives the small miner immediate liquidity while linking future metal sales to a much larger counterparty in the gold trade.
Galantas Gold Secures $10 Million Ocean Partners Facility
For Galantas, the deal is less about optics than survival and execution. Junior gold producers often struggle to bridge the gap between producing metal and getting paid, especially when operating cash flow is tight and capital markets remain selective. An advance against dore can reduce near-term funding pressure, support working capital and keep development plans moving without forcing the company back into the equity market at a weak valuation. For investors, that can be the difference between a miner that can scale and one that stays permanently constrained by dilution and debt.
The transaction also fits a broader pattern across the gold sector: producers and refiners are leaning harder on streaming, prepayment and off-take structures as bullion remains elevated and financing conditions stay uneven. That matters economically because it shifts some financing risk away from fragile balance sheets and toward metal counterparties with stronger access to capital and trading networks. In practical terms, it can keep ounces flowing through the system and preserve supply at a time when demand for gold exposure remains supported by macro uncertainty.
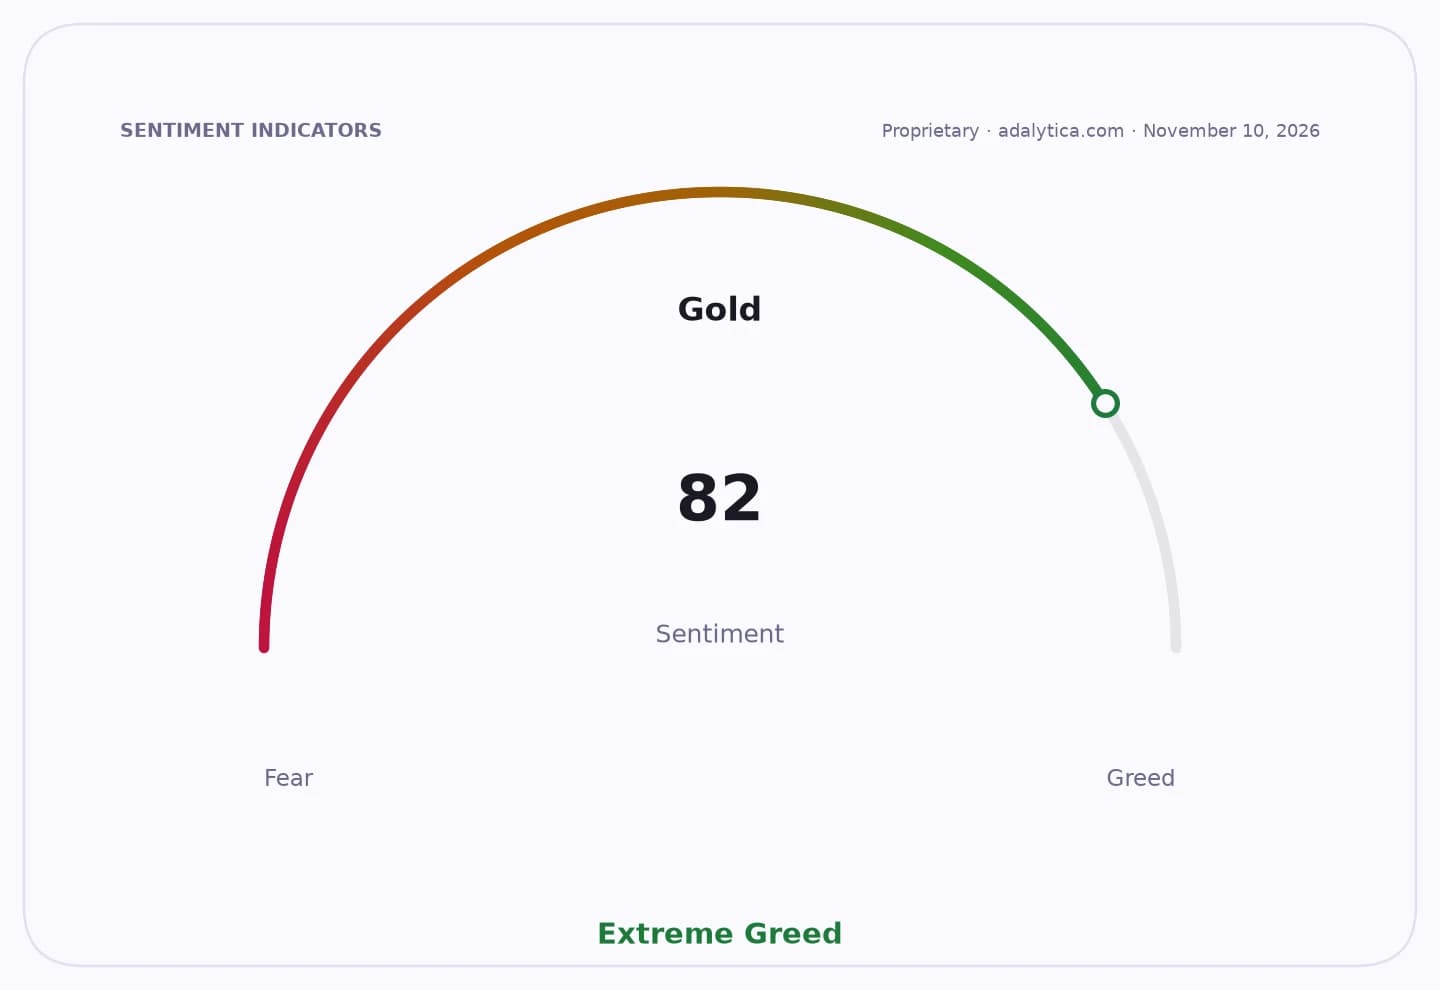
Gold itself remains a powerful backdrop. The metal has traded well above its 50-day moving average in recent sessions, and while momentum has cooled from earlier peaks, prices still reflect persistent demand for defensive assets. That backdrop improves the economics of advance-sale structures: the higher the gold price, the more valuable each ounce becomes for both producer and financier, and the more room there is for juniors to negotiate working-capital support.
For Ocean Partners, the arrangement strengthens its position as a financier and marketing partner in a market where traders with balance sheet strength can earn attractive returns by funding supply. For Galantas, the key question is whether this facility is a bridge to sustainable production growth or simply a stopgap. Investors should see it as a positive signal that the company has secured access to non-dilutive capital, but also as a reminder that junior miners are still operating in a world where financing is as important as geology.
The real takeaway is that the gold cycle is now increasingly being financed through structured deals rather than straight equity. That is where the opportunity often becomes asymmetric: not only in bullion itself, but in the small producers and trading houses that can convert higher gold prices into cash flow. If Galantas can translate this facility into steadier output and stronger operating discipline, the market may eventually rerate the stock from funding-risk story to production leverage story.
| Entity | Gains | Losses |
|---|---|---|
| Galantas Gold | ▲Immediate liquidity | ▼Dilution pressure eases |
| Ocean Partners | ▲Financing yield | ▼Counterparty credit exposure |
| Existing shareholders | ▲Lower near-term funding risk | ▼Still face execution risk |
| Equity investors in juniors | ▲Better funding visibility | ▼Less upside from scarcity of capital |