Odyssey Gold’s latest drilling results may strengthen the long-term case for its Murchison gold projects in Western Australia, but the market has chosen to focus on execution risk, dilution and the long wait between discovery and production.
Odyssey Gold reports high-grade drilling at Tuckanarra
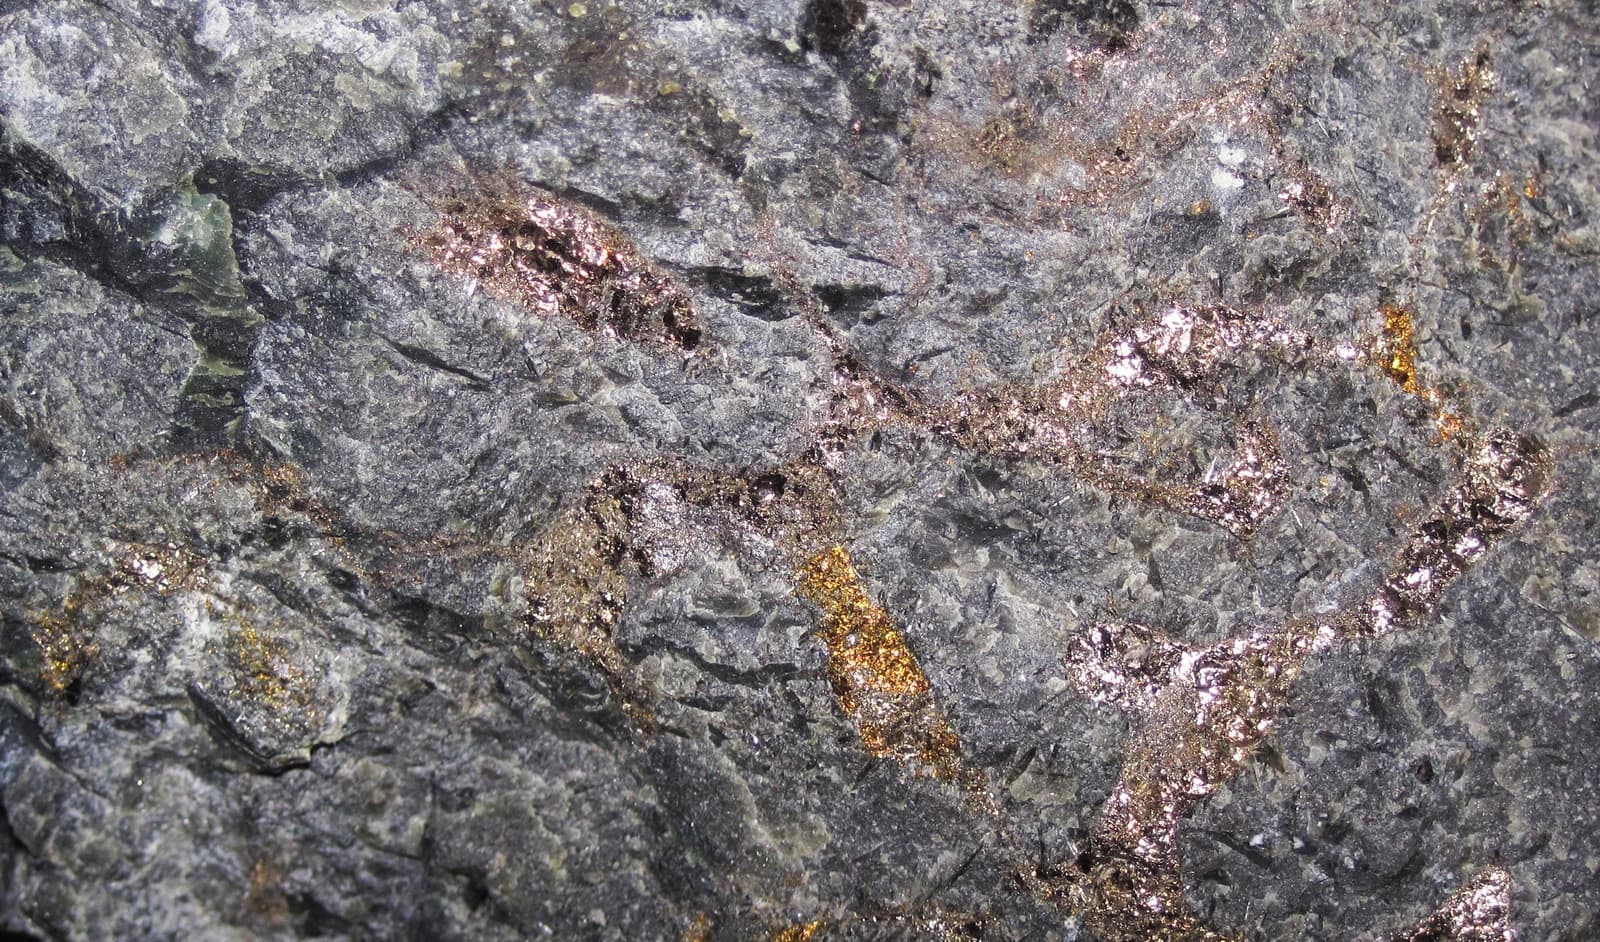
That is the real story behind the stock’s 14.63% slide. Odyssey said reverse-circulation drilling at its Tuckanarra project intersected multiple high-grade gold zones at Cable West, including 5 metres grading 16.1 grams per tonne from 30 metres, with 2 metres at 36.7 g/t, and another 9 metres at 6.8 g/t from 99 metres. The company also reported 5 metres at 6.7 g/t at Argos and 11 metres at 2.4 g/t in a hanging-wall structure. For an explorer, those are the kinds of numbers that can change the conversation around resource growth.
Why it matters economically is simple: higher-grade, shallower gold intersections can improve the economics of future mining, raise the odds of a resource upgrade and, eventually, support a development decision. Odyssey said the new holes suggest several parallel veins west of Cable are not yet captured in the mineral resource estimate and that tighter spacing could help move inferred ounces into the indicated category in the next update. In a sector where ounces in the ground only matter if they can be mined profitably, continuity and grade are the whole game.
But investors are not paying for geology alone. They are paying for a path to cash flow, and that path is still distant. The company says the drilling is part of a 20,000-metre program, with results from about 60 holes still pending. Even supporters in the market are talking about patience, with some pointing to a possible toll-milling start only around 2027. That timeline matters because junior miners often see their shares drift or swing violently long before any production benefit is visible. Financing needs, dilution and the risk that promising holes do not translate into mineable tonnage all weigh on sentiment.
The broader backdrop is mixed but constructive for the sector. Gold remains an attractive hedge in a volatile macro environment, yet the recent price action has reminded investors that momentum can reverse quickly. That makes explorers like Odyssey more of a story stock than a direct play on bullion. The upside case is leverage to rising gold prices and a bigger resource at Tuckanarra. The downside is that every step toward feasibility takes capital, time and more drilling success.
For long-term investors, Odyssey is still a watchlist name, not a destination. The latest holes improve the narrative around Cable West and Argos, but the market will want evidence of scale, continuity and funding discipline before it rewards the company with a higher valuation. If Odyssey can keep turning high-grade hits into a larger, more coherent resource, the shares could eventually rerate. Until then, this remains an explorer to follow for years, not weeks.
| Entity | Gains | Losses |
|---|---|---|
| Odyssey Gold | ▲Resource upside | ▼Short-term traders |
| Long-term holders | ▲Potential rerating | ▼Impatient shareholders |
| Future gold production | ▲Better project economics | ▼Near-term cash needs |
| Competitors without new hits | ▲Less attention | ▼Mindshare and capital |