GH Bank is rolling out a 20 billion baht home-loan promotion to mark its 73rd anniversary, offering an introductory rate of 0.73% a year for the first three months in a bid to support Thai household demand and keep the housing market moving.
GH Bank launches 20 billion baht home-loan promotion
The campaign matters because housing affordability remains a major drag on demand in Thailand, where elevated borrowing costs have squeezed first-time buyers and slowed mortgage uptake. By pairing a headline rate below 1% with fee waivers and repayment terms of up to 40 years, the state-owned lender is effectively using its balance sheet to widen access to credit at a time when the sector needs easier financing to clear inventory.
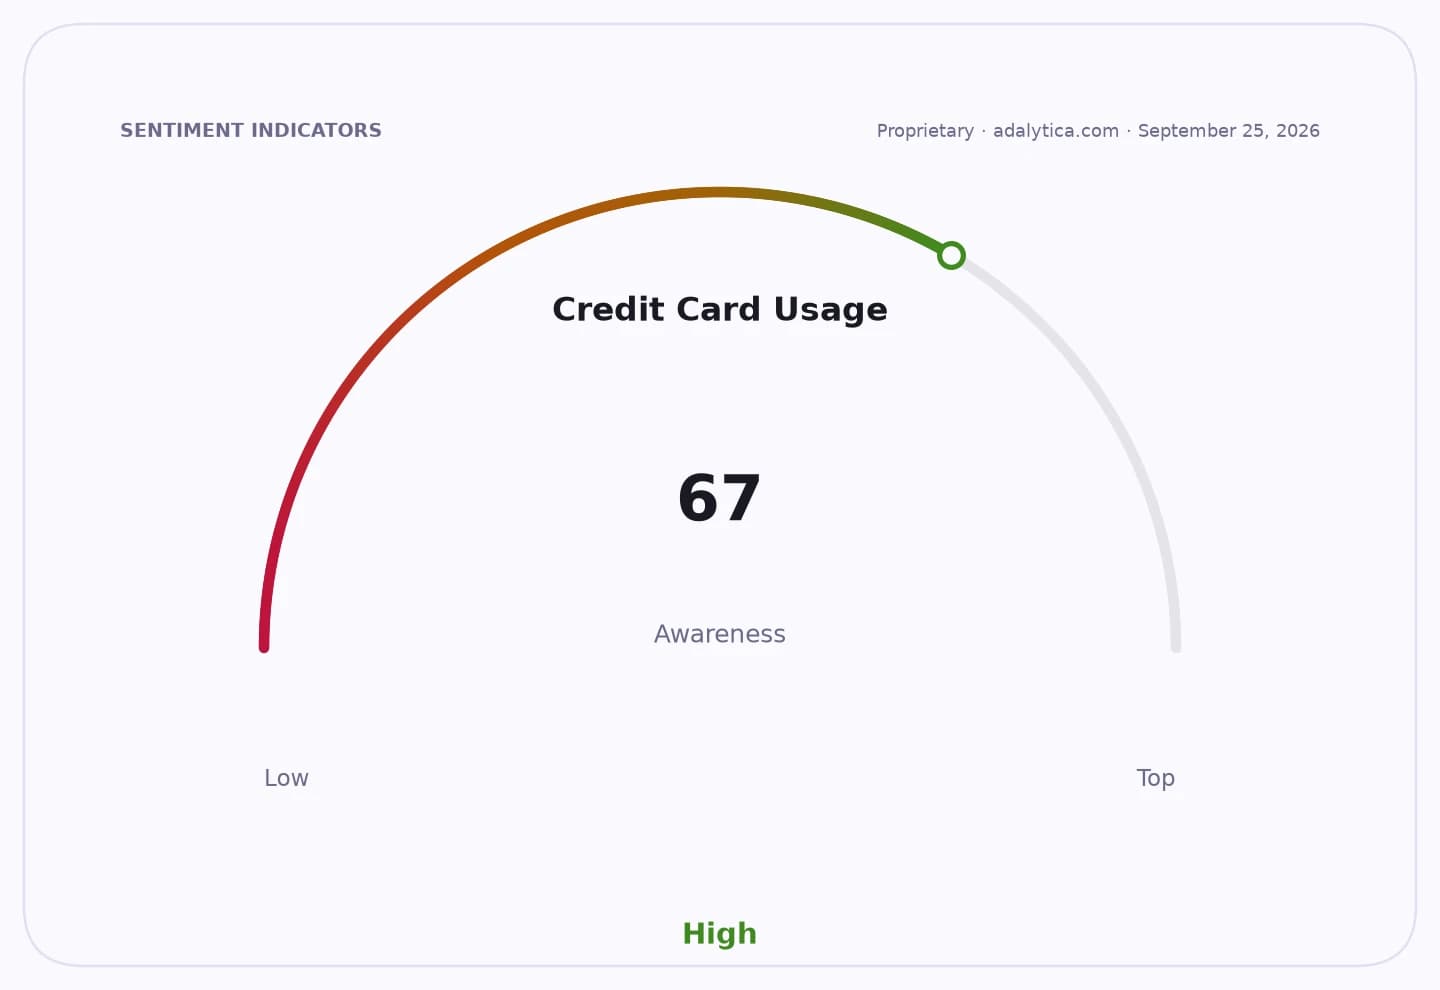
Sentiment IndicatorsⓘProprietary · adalytica.com · September 7, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Under the “GH Bank 73 Years Beyond” package, borrowers can tap rates of 0.73% in months one to three, 1.73% in months four to nine, and then move to MRR-linked pricing, with the bank’s current MRR at 6.145%. For salaried welfare customers, rates are set at MRR minus 1 percentage point, while retail borrowers get MRR minus 0.50 point. Customers borrowing to buy equipment or refinance debt pay MRR.
The lender said a 1 million baht loan over 40 years would require monthly payments of about 2,500 baht, underscoring how aggressively it is trying to stretch affordability. Refinance borrowers also get free mortgage registration fees of 1% of the loan amount, capped at 200,000 baht, plus free appraisal fees for applications filed through Sept. 30, 2026.
For investors, the move is less about near-term earnings than about loan growth, asset quality and the broader direction of Thai housing demand. A promotional campaign of this size can support disbursements and refinancing volumes, while also pressuring margins if funding costs remain sticky, especially with benchmark rates still elevated by recent standards.
The announcement also fits a wider pattern of policy-style support for credit in Thailand, where housing and grassroots lending are being used as tools to stimulate spending and household resilience. The key test now is whether lower teaser rates translate into actual home purchases and refinancing activity over the next few quarters, or merely pull forward demand without materially improving the housing cycle.
| Entity | Gains | Losses |
|---|---|---|
| GH Bank | ▲Loan growth and customer acquisition | ▼Near-term interest margin pressure |
| Thai homebuyers | ▲Lower entry costs and fees | ▼Risk of higher payments after teaser period |
| Refinancing borrowers | ▲Cheaper debt rollover | ▼Less pricing leverage at other lenders |
| Rival lenders | ▲None明显 | ▼Share loss in mortgage market |