Gold is under pressure again as U.S. Treasury yields stay elevated and the dollar trade signal weakens, raising the risk of a deeper pullback after this year’s sharp run-up.
Gold Pulls Back as Treasury Yields Stay Elevated

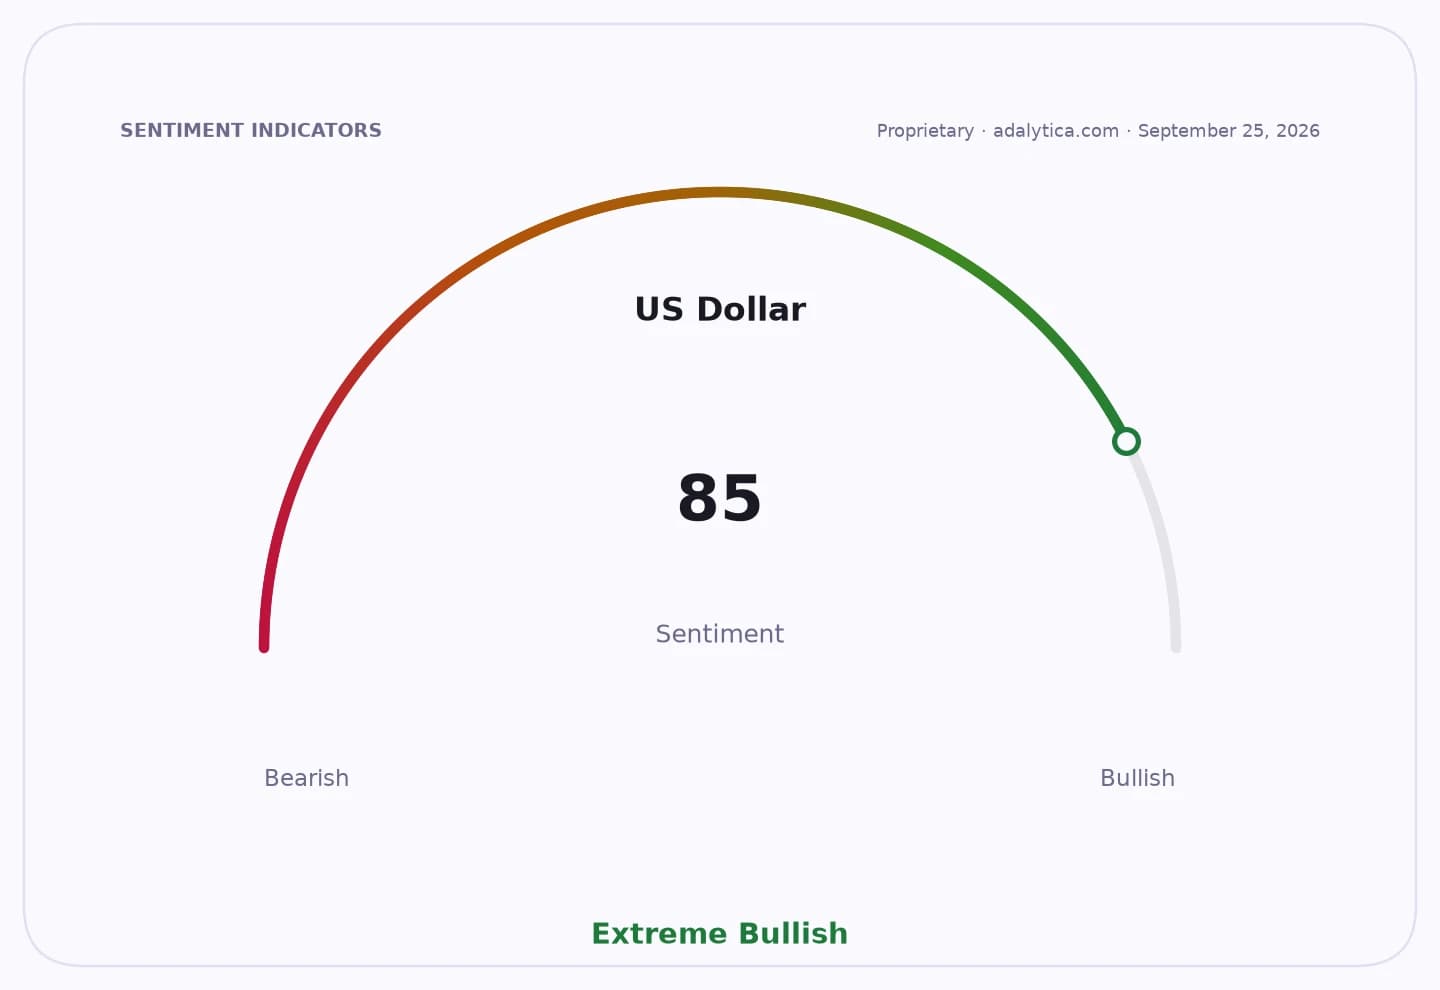
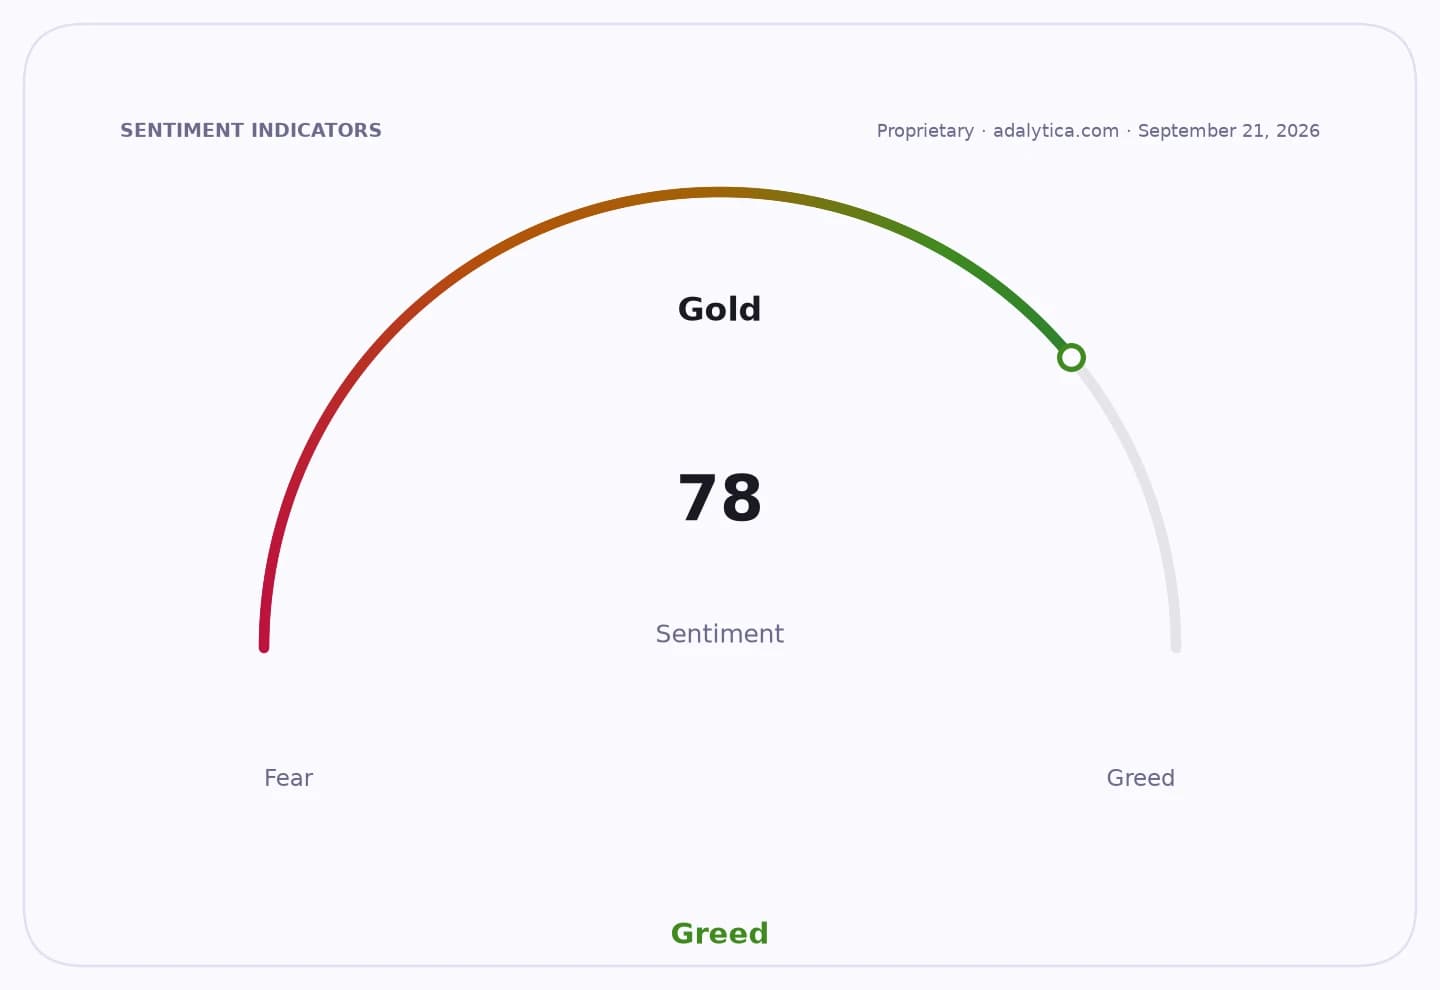
The 10-year Treasury yield is forecast at 4.628%, while the 2-year is seen at 4.169%, levels that keep the opportunity cost of holding non-yielding bullion high. At the same time, Adalytica’s Gold Fear & Greed Index has dropped to 27, deep in fear, from 70 at the end of August, while the U.S. dollar trade snapshot shows sentiment at 17 even as awareness remains high, a mix that points to unstable macro trading conditions rather than a clean breakout.
Sentiment IndicatorsⓘProprietary · adalytica.com · August 30, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That backdrop matters because gold had been priced for perfection. The front-month Comex contract, GC=F, hit 4,609.7 on Aug. 27 before sliding to 4,529.9 on Aug. 28, while GLD fell to 408.89 from 422.6 a day earlier. Both remain far above their 200-day moving averages — 4,513.66 for GC=F and 414.79 for GLD — but the latest drop came with stronger turnover, a sign that traders are actively de-risking rather than waiting for a shallow dip.
The move also arrives after a volatile stretch that saw bullion power to new highs and then reverse quickly. GLD’s RSI has eased to 54.2 from overbought levels above 70 earlier in the week, and the contract’s momentum has cooled even as the broader uptrend remains intact. PHYS, another gold-backed fund, also slipped to 33.8 from 35.0, underscoring that the pullback is broad-based rather than limited to one vehicle.
For investors, the key question is whether rising yields and a firmer real-rate backdrop can keep cap gold prices lower in the near term. If the 10-year stays near 4.6% and the dollar steadies, bullion could struggle to reclaim recent peaks. But if inflation data or growth worries revive rate-cut bets, gold’s safe-haven bid could return quickly.
| Entity | Gains | Losses |
|---|---|---|
| Treasury yields | ▲Carry and fixed-income demand | ▼Gold bulls |
| U.S. dollar | ▲Relative support versus bullion | ▼Importers buying gold |
| Gold miners and bullion funds | ▲None in the short term | ▼Near-term momentum traders |
| Gold buyers/jewelers | ▲Lower entry prices | ▼Holders near recent highs |