Gold climbed in U.S. trading after a much softer-than-expected September employment report pushed Treasury yields lower and sharply reduced expectations for another Federal Reserve rate increase this month.
Gold Rises After Softer September Jobs Report
Spot gold was last around $4,186 an ounce late Oct. 2, up about $8 on the session, while December futures traded near $4,211. The move came after the U.S. economy added just 29,000 jobs in September, far below forecasts for roughly 88,000 to 90,000, and the unemployment rate rose to 4.2%.
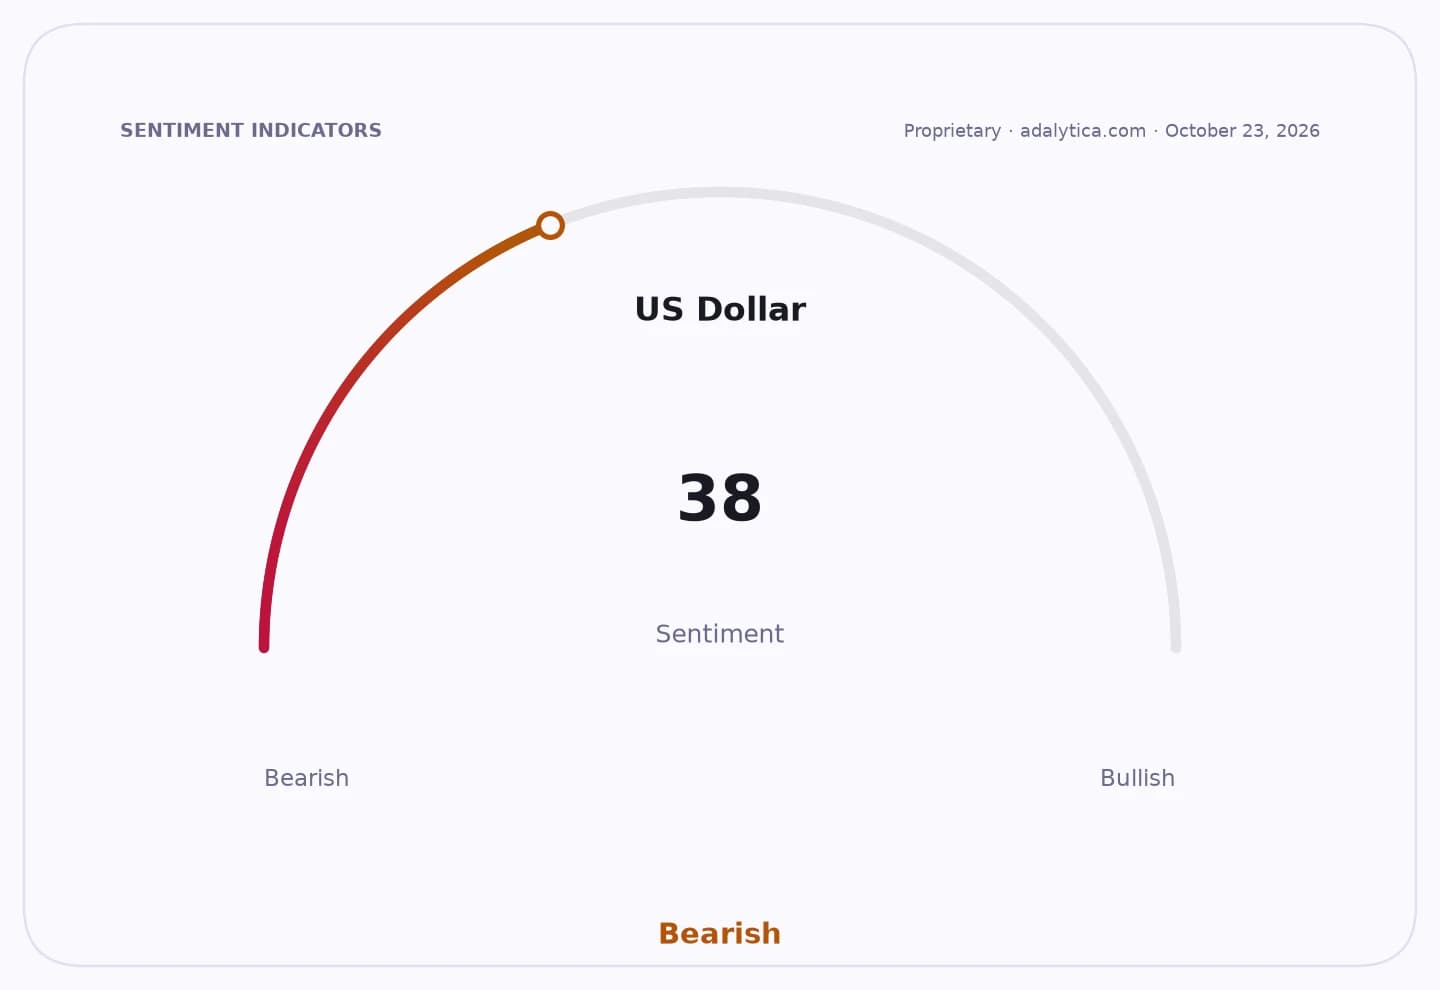
Sentiment IndicatorsⓘProprietary · adalytica.com · October 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The labor data matters because it weakens the case for the Fed to keep tightening into year-end. Markets quickly trimmed the probability of an October hike to below 20% from more than 25% before the report, while the 10-year Treasury yield eased to around 5.18%, reducing the opportunity cost of holding non-yielding gold.
The report also showed cooling underneath the headline number. Average hourly earnings for private-sector workers rose just 0.1% from August and 3% from a year earlier, while prior payrolls for July and August were revised down by a combined 60,000 jobs.
For investors, the combination is supportive for bullion and gold-linked funds because lower yields and a softer rate outlook tend to boost demand for haven assets. GLD, the SPDR Gold Trust, remains under pressure from a recent pullback, with technical readings still subdued: its close of $380.14 on Oct. 2 sat below the 50-day moving average of about $396.29, while RSI readings around 38 point to weak but not exhausted momentum.
Miners also tracked the move, though less cleanly. GDX, the VanEck Gold Miners ETF, ended Oct. 2 at $87.78, still below its 50-day average near $91.44, suggesting the sector has not fully confirmed the rebound in bullion.
Adalytica’s Gold Fear & Greed Index remained in “Extreme Fear” at 13, underscoring how fragile sentiment is even as prices bounce. That leaves the market focused on the next round of U.S. data, including factory orders, manufacturing activity, the New York Fed’s gauge and the ISM services index, before September CPI becomes the next major test for Fed expectations.
| Entity | Gains | Losses |
|---|---|---|
| Gold bulls | ▲Lower yields, softer Fed outlook | ▼Near-term volatility |
| Treasury bond holders | ▲Price support from falling yields | ▼Inflation risk if CPI stays hot |
| Fed hawks | ▲Little gain from weak labor data | ▼Case for an October hike |
| Gold miners | ▲Better bullion backdrop | ▼Still-weak technical setup |