Government Savings Bank has given GROREIT a six-month reprieve on its 1.35 billion baht loan, delaying a repayment crunch that could have forced a more disruptive asset sale or a sharper hit to cash distributions.
GROREIT Gets Six-Month Loan Extension
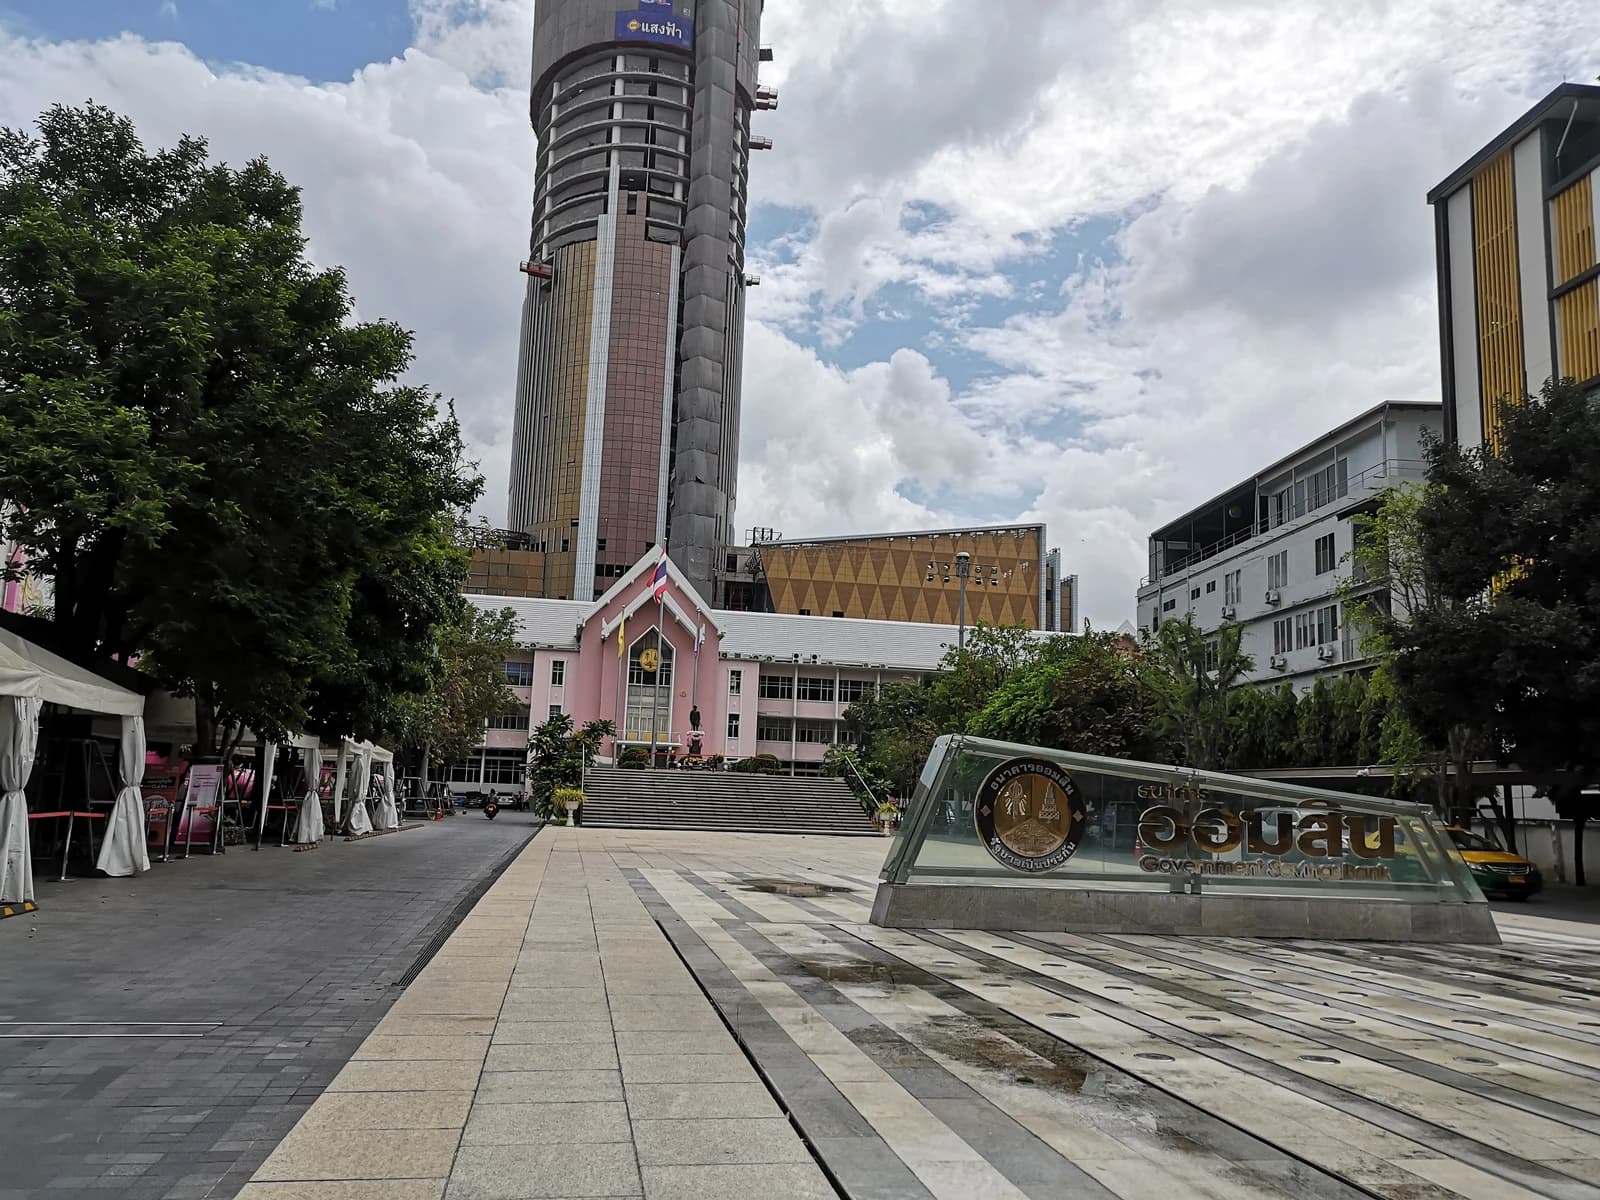
The extension matters because it buys time, not relief. GROREIT still faces repayment due Jan. 15, 2027, must keep paying down principal monthly at no less than 25% of cash left from hotel operations, and remains barred from distributing dividends to unitholders until the bank is fully repaid. The lender also agreed to let the trust dispose of pledged assets, underscoring that this is a workout, not a clean refinancing.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 18, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the message is straightforward: this is a balance-sheet story first and a yield story second. GROREIT’s leverage over the Royal Orchid Sheraton Hotel & Towers remains the central risk, and the lender’s approval suggests management had limited room to maneuver in a tighter funding environment. That kind of constraint matters in a market where higher-for-longer rates are still squeezing property owners, especially those reliant on hotel cash flow and asset monetization.
The move also fits a broader pattern in Thailand’s real estate investment trust market, where debt extensions are becoming a key survival tool rather than an exception. It signals that creditors may prefer staged recovery over immediate enforcement, which can stabilize the asset in the short term but leaves equity and unit holders with capped upside until deleveraging is complete.
GROREIT’s unit price has already reflected that tension. The trust has been trading below its recent highs, with technical indicators showing a softer trend than earlier in the year, even as investors periodically chased relief rallies on debt-workout headlines. That volatility is typical of overlevered property vehicles: the upside comes quickly on extension news, but the real rerating only arrives when balance-sheet risk is materially reduced.
For now, the extension keeps the asset in operation and avoids an immediate forced sale, which is good for lenders who want to preserve value and for bulls who believe the hotel can keep generating enough cash to bridge the gap. But until the debt is brought down and dividend restrictions are lifted, GROREIT remains a leveraged bet on tourism recovery and creditor patience.
The tradeable takeaway is clear: this is not yet a recovery story, but a distress-management story with optionality. Investors looking for asymmetric exposure should focus on whether GROREIT can convert the extension into a durable deleveraging path; until then, the bank has the cleaner claim on the asset value.
| Entity | Gains | Losses |
|---|---|---|
| Government Savings Bank | ▲Higher recovery odds | ▼Immediate enforcement risk |
| GROREIT | ▲Six-month breathing room | ▼Dividend ban, continued leverage |
| Unitholders | ▲Chance of orderly workout | ▼Frozen payouts, capped upside |
| Hotel asset / operator | ▲Avoids forced sale | ▼Ongoing cash flow pressure |