Kepler Cheuvreux has initiated coverage of Swedish housing portal Hemnet with a “hold” recommendation and a price target of 72 kronor, a call that frames the shares as fairly valued after a strong run and leaves investors looking for clearer upside catalysts.
Hemnet Gets Hold Rating, 72-Kronor Target
The note matters because Hemnet sits at the intersection of Sweden’s housing market, online real-estate advertising and a business model that has increasingly appealed to investors for its recurring revenue and high margins. A hold rating from a sell-side house typically signals that the company’s quality is not in doubt, but that the current share price already reflects much of the earnings outlook.
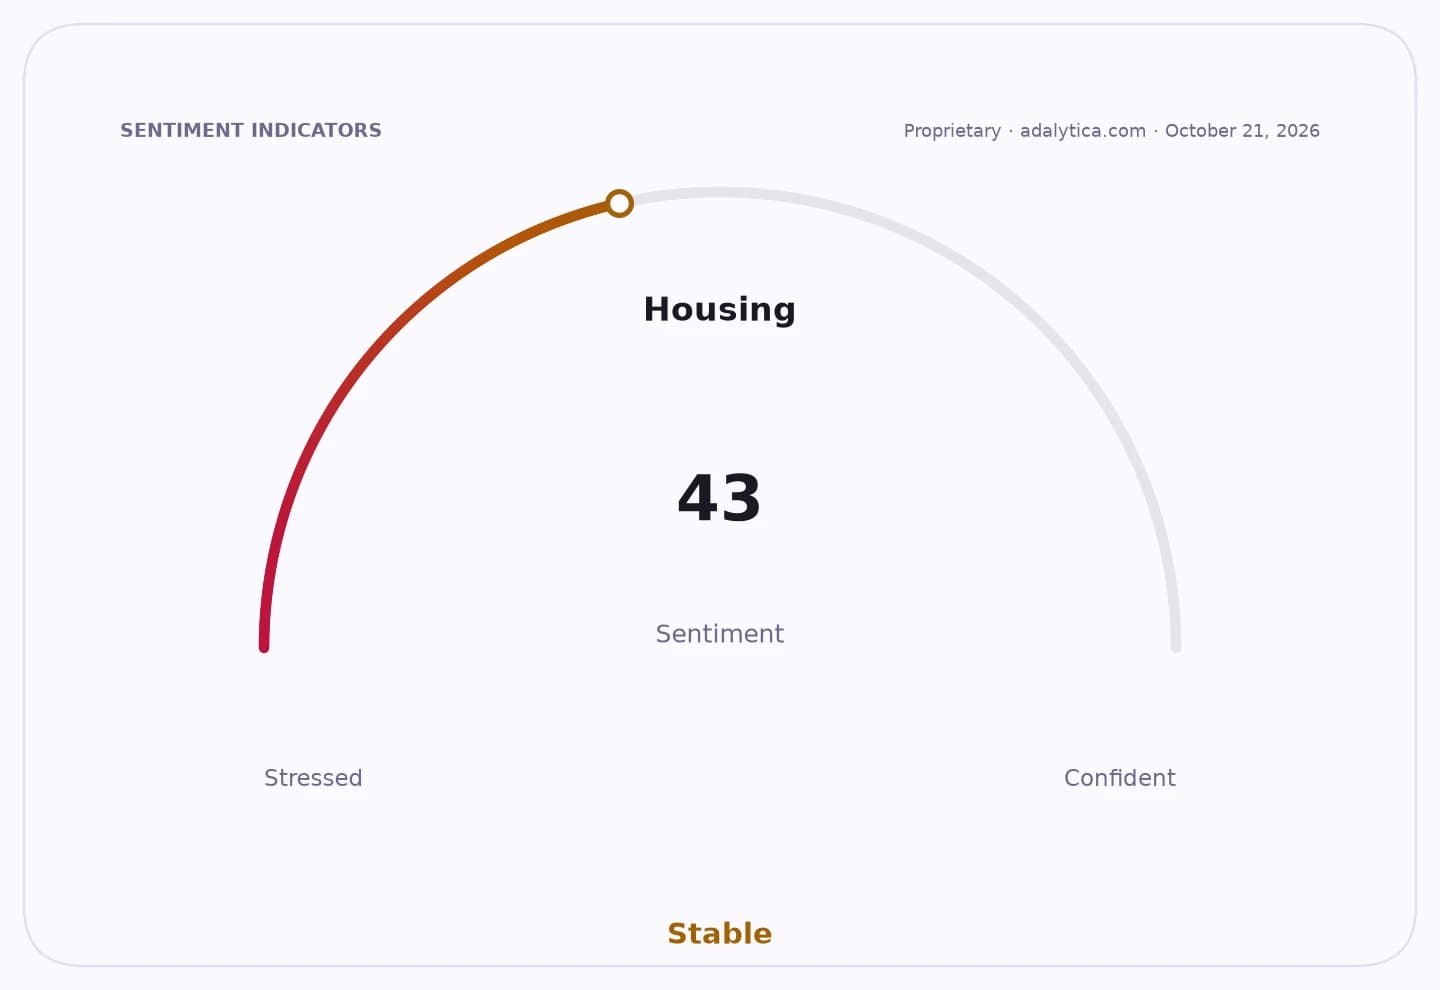
Sentiment IndicatorsⓘProprietary · adalytica.com · October 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the key question is not whether Hemnet remains a dominant property platform, but whether growth can keep justifying a premium multiple in a market that is still sensitive to housing turnover, mortgage rates and broader consumer confidence. If transaction volumes recover, Hemnet’s ad and listing revenues should benefit. If the Swedish housing market stays subdued, the company’s leverage to activity could cap near-term upside.
The 72-kronor target also gives the market a reference point for expectations around valuation discipline. In a sector where digital marketplaces can attract premium pricing on network effects and scale, research coverage can shift attention from the quality of the franchise to the pace at which earnings and free cash flow can compound from here.
That makes the stock a balancing act between a structural bull case and a cyclical bear case. Bulls will argue Hemnet remains the clear leader in a relatively defensive digital asset with strong monetization power. Bears will point to a slower housing backdrop and the risk that the shares already discount much of the long-term story.
What investors will watch next is whether Hemnet can continue converting its market position into faster revenue growth without depending on a broad housing rebound. Any signs of improved Swedish home sales, better pricing power or stronger user engagement would strengthen the case for re-rating. Absent that, the stock may remain in the “quality company, limited upside” category that a hold recommendation implies.
| Entity | Gains | Losses |
|---|---|---|
| Kepler Cheuvreux | ▲Coverage relevance | ▼Calls for limited upside |
| Hemnet bulls | ▲Franchise validation | ▼Immediate re-rating hopes |
| Existing shareholders | ▲Stable market view | ▼Bigger valuation premium |
| Potential buyers | ▲Entry point clarity | ▼Upside if housing stays weak |