Hewlett Packard Enterprise is suddenly looking like one of the cleaner ways to invest in the AI buildout after a strong quarter, a raised annual forecast and a fresh Oracle-related partnership push sent the stock sharply higher.
HPE Raises Guidance After AI Infrastructure Demand
That matters because HPE is no longer just a mature hardware vendor trying to keep up with cloud spending cycles. It is increasingly tied to the infrastructure that powers artificial intelligence — the servers, networking gear and storage systems that companies need before they can sell a single AI service. When management can point to real demand and then raise guidance, investors get something rare in this market: evidence that AI adoption is translating into revenue, not just headlines.
The Oracle angle adds another layer. Oracle has spent the past year positioning itself as a core player in AI infrastructure, and HPE’s involvement suggests the ecosystem around enterprise AI is widening beyond the usual hyperscaler names. For investors, that broadens the opportunity set. The winners of the AI boom are not limited to chipmakers like Nvidia; there is also money to be made in the picks-and-shovels layer where HPE operates.
The market is already rewarding that story. HPE shares have climbed to $51.83 in the latest session, leaving the stock well above its 50-day moving average and far ahead of its 200-day average of $32.81. The move reflects more than momentum chasing. It shows that investors are willing to pay up when a company can tie AI demand to better earnings visibility and stronger order flow.
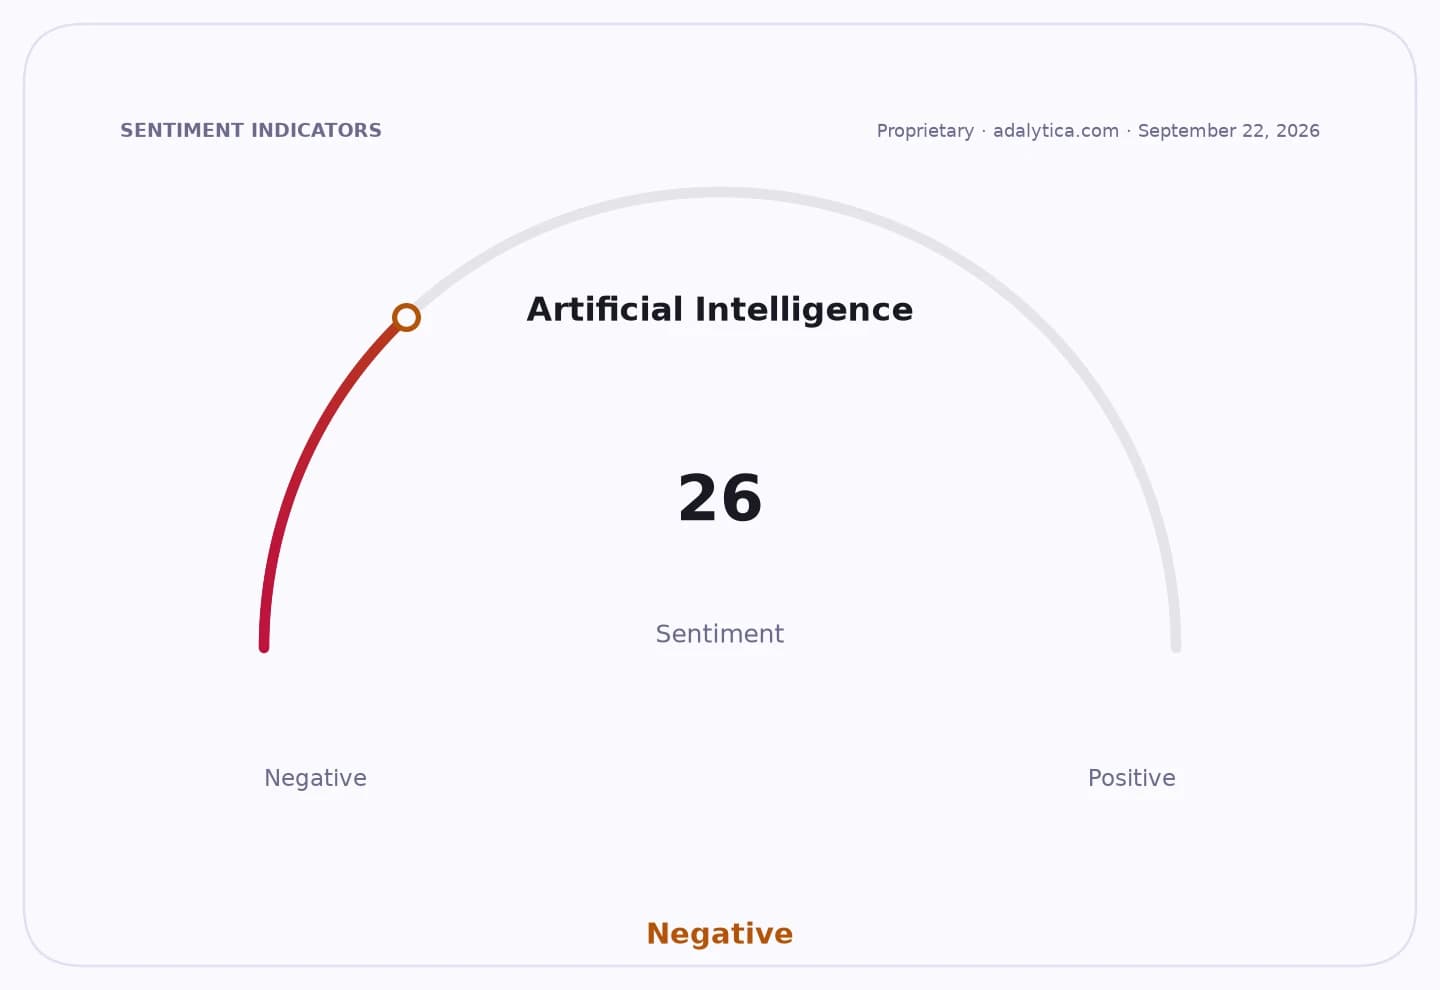
Artificial Intelligence — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
Still, the setup is not without risk. HPE has had a huge run, and its RSI reading around 26 on the most recent data points to a stock that has cooled quickly after an earlier surge. That can create opportunity, but only for investors who are thinking in years, not weeks. AI infrastructure spending is likely to remain lumpy, competitive and capital intensive, and not every partnership will become a meaningful profit engine.
The longer-term case is straightforward: if enterprises, governments and cloud providers keep building out AI capacity, companies like HPE should keep finding work. Oracle’s continued push into AI infrastructure only strengthens that backdrop. For investors building a portfolio for the next three to five years, HPE now deserves a place on the watchlist — and potentially the buy list — if you believe the AI spending cycle is still early.
| Entity | Gains | Losses |
|---|---|---|
| HPE shareholders | ▲Higher guidance, AI demand | ▼Chasing after the rally |
| Oracle and AI partners | ▲Bigger ecosystem, more adoption | ▼Less exclusivity |
| Enterprise AI buyers | ▲More infrastructure choices | ▼Higher competition for capacity |
| Short sellers | ▲Volatility to trade | ▼Momentum and upgrade risk |