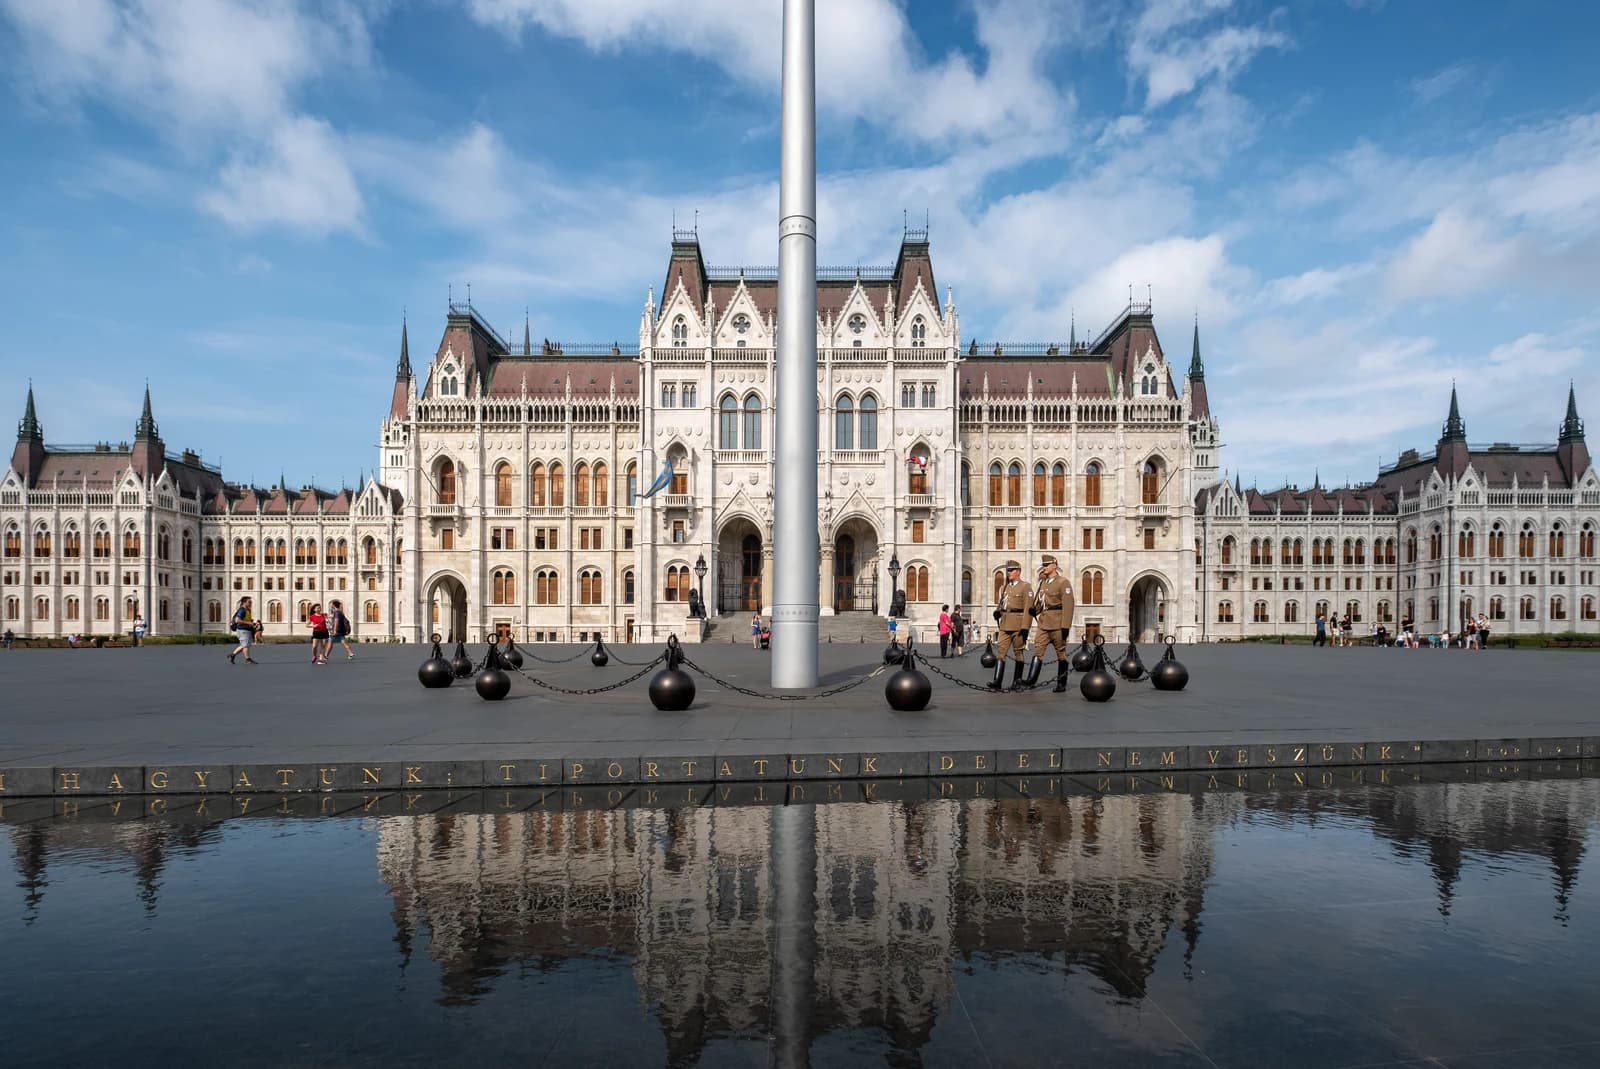
Hungary’s inflation came in cooler than expected in September, giving policymakers and investors a better case for lower interest rates — even if rising energy costs and a shakier forint could keep the central bank cautious for now.
Hungary inflation cools in September
Consumer prices rose 1.6% from a year earlier, below economists’ 1.8% forecast and still modest by international standards, according to the statistical office. The print was stronger for households than the market had feared, and it extended a run of softer-than-expected inflation readings over the summer. For long-term investors, that matters because inflation is the key variable behind Hungary’s rate path, the forint’s stability and the valuation of local bonds and stocks.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The most important detail is that core inflation, which strips out volatile items and better reflects underlying price pressure, also slowed from August. That suggests the recent disinflation is not just about one-off effects, but about more restrained pricing behavior by companies and slower wage pass-through. In practical terms, that gives the Hungarian central bank room to think about easing eventually, even if not immediately.
Market reaction will hinge on a familiar balancing act. Lower inflation normally supports rate cuts, which would be positive for borrowers and for interest-rate sensitive assets such as Hungarian government bonds. But policymakers are also watching imported inflation risks. Higher energy prices are already feeding through producer costs, and global food prices have started rising again. If those pressures reach supermarket shelves, the next few months could look less benign.
That is why the forint remains so important. A weaker currency lifts the local cost of imports, especially energy and food, and can quickly undo some of the inflation progress. Several local economists said the central bank is likely to stay cautious because of geopolitical uncertainty, higher global yields and the risk that a softer forint reignites price pressure. Some even see a small chance of a December rate cut if inflation continues to surprise on the downside, but the base case remains a pause.
For investors, the message is straightforward: Hungary’s disinflation story is still intact, and that is supportive for fixed income and for any assets that benefit from lower borrowing costs. But the trade is not one-way. If energy stays elevated, wage growth cools more slowly than expected, or the currency weakens, inflation could reaccelerate in early 2027. That would limit how fast the central bank can ease and could keep valuations under pressure.
The broader narrative is that Hungary is moving closer to a normal inflation backdrop, which is exactly what markets want to see after the shock of the past few years. If that holds, the country’s assets can continue to reprice on the possibility of lower rates and steadier growth. If it doesn’t, the forint and imported costs will quickly remind investors how fragile the progress still is.
| Entity | Gains | Losses |
|---|---|---|
| Hungarian bondholders | ▲Lower rate expectations | ▼Inflation rebound risk |
| Borrowers and consumers | ▲Easier financing, calmer prices | ▼Energy and food pass-through |
| Forint bulls | ▲Softer inflation backdrop | ▼Currency weakness from global risk-off |
| Hungarian central bank | ▲More room to ease later | ▼Pressure to stay cautious now |