India’s fast-growing gold loan market is showing the first cracks, and that matters because the segment has been one of the most dependable engines of growth for non-bank lenders in a high-interest-rate environment. When borrowers start to struggle against the very asset that backs the loan, it can quickly turn a supposedly safe product into a source of earnings pressure, higher credit costs and tighter underwriting across the industry.
India gold loan market shows early stress
The warning from leading NBFCs is especially important for investors in gold-finance names such as Muthoot Finance and Manappuram Finance, which have built large businesses around loans secured by household gold. These lenders typically benefit when demand for short-term borrowing stays strong and gold prices support high loan-to-value ratios. But early repayment stress suggests more customers may be unable to service or roll over debt as inflation, stretched household budgets and weaker cash flows bite.
Sentiment Indicators
That is why the issue goes beyond one lending niche. Gold loans are often marketed as quick, collateralized credit with relatively low loss rates, but stress in the book can still hurt margins if lenders need to collect more aggressively, restructure accounts or hold back on fresh growth. Investors should also watch for any sign that rising stress is concentrated among small borrowers, where affordability can deteriorate quickly if incomes lag.
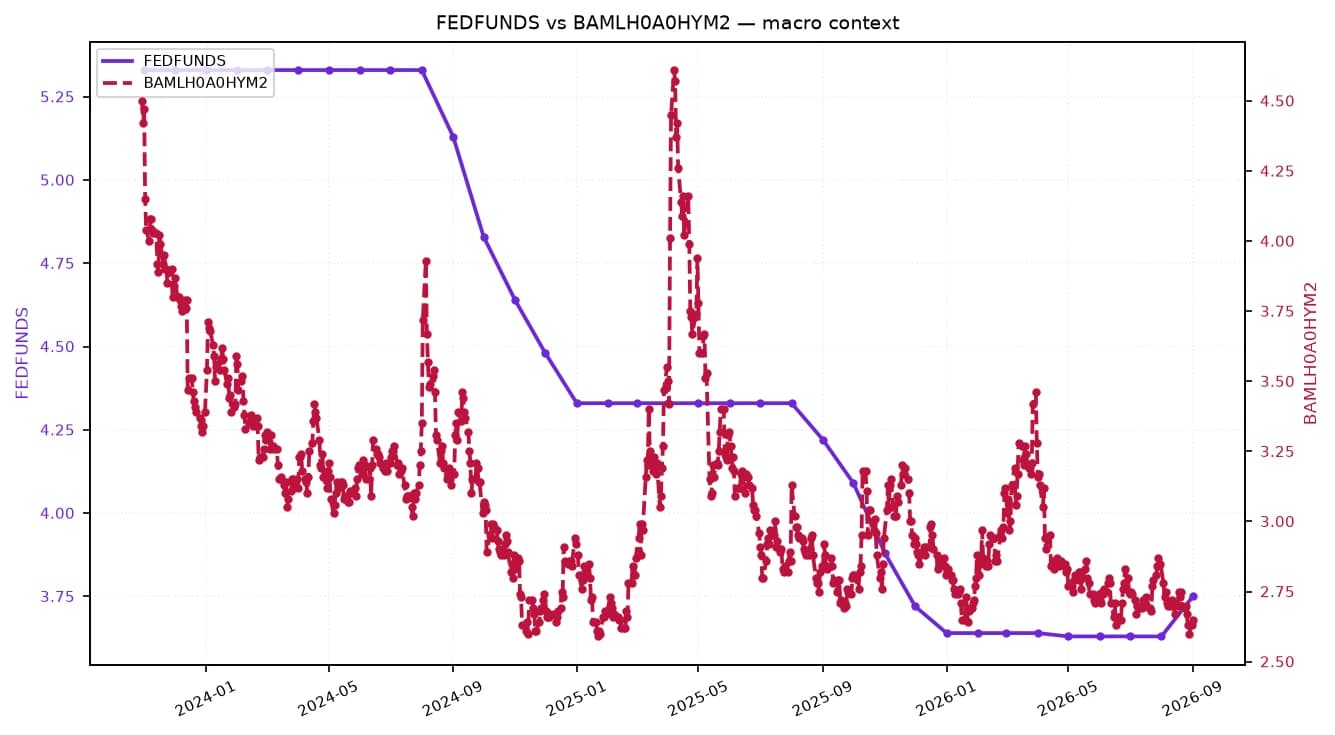
The broader macro backdrop matters too. With the US dollar showing recent weakness and risk appetite bouncing around in global markets, gold has remained an important store of value for households. Yet even a stronger gold price cannot fully offset repayment pressure if borrowers tapped the same collateral to fund consumption or business expenses and now face tighter cash flow. In other words, asset values can cushion losses, but they do not eliminate credit risk.
For long-term investors, the key question is whether this is a brief delinquency uptick or the start of a more cautious phase in India’s secured lending cycle. Gold loan lenders still have powerful structural advantages — deep distribution, loyal customers and collateral that is easier to monitor than unsecured credit — but even those advantages depend on disciplined underwriting and healthy borrower behavior.
If repayment stress stays contained, the sector could remain a reliable compounder. If it widens, expect slower growth, more scrutiny from lenders and a reset in how the market prices the stocks. For now, gold loan NBFCs are still worth watching closely rather than writing off, but the early signs of stress should make investors more selective.
| Entity | Gains | Losses |
|---|---|---|
| Well-capitalized gold NBFCs | ▲market share from rivals | ▼tighter lending growth |
| Borrowers with pledged gold | ▲access to quick credit | ▼higher rollover stress |
| Investors in Muthoot/Manappuram | ▲potential buying setups on dips | ▼earnings and credit-cost risk |
| Smaller, weaker NBFCs | ▲limited benefit | ▼higher default exposure |