India’s factory growth lost a little steam in October, with the manufacturing purchasing managers’ index easing to 54.7 as new orders and production expanded at a slower pace.
India Manufacturing PMI Eases to 54.7 in October
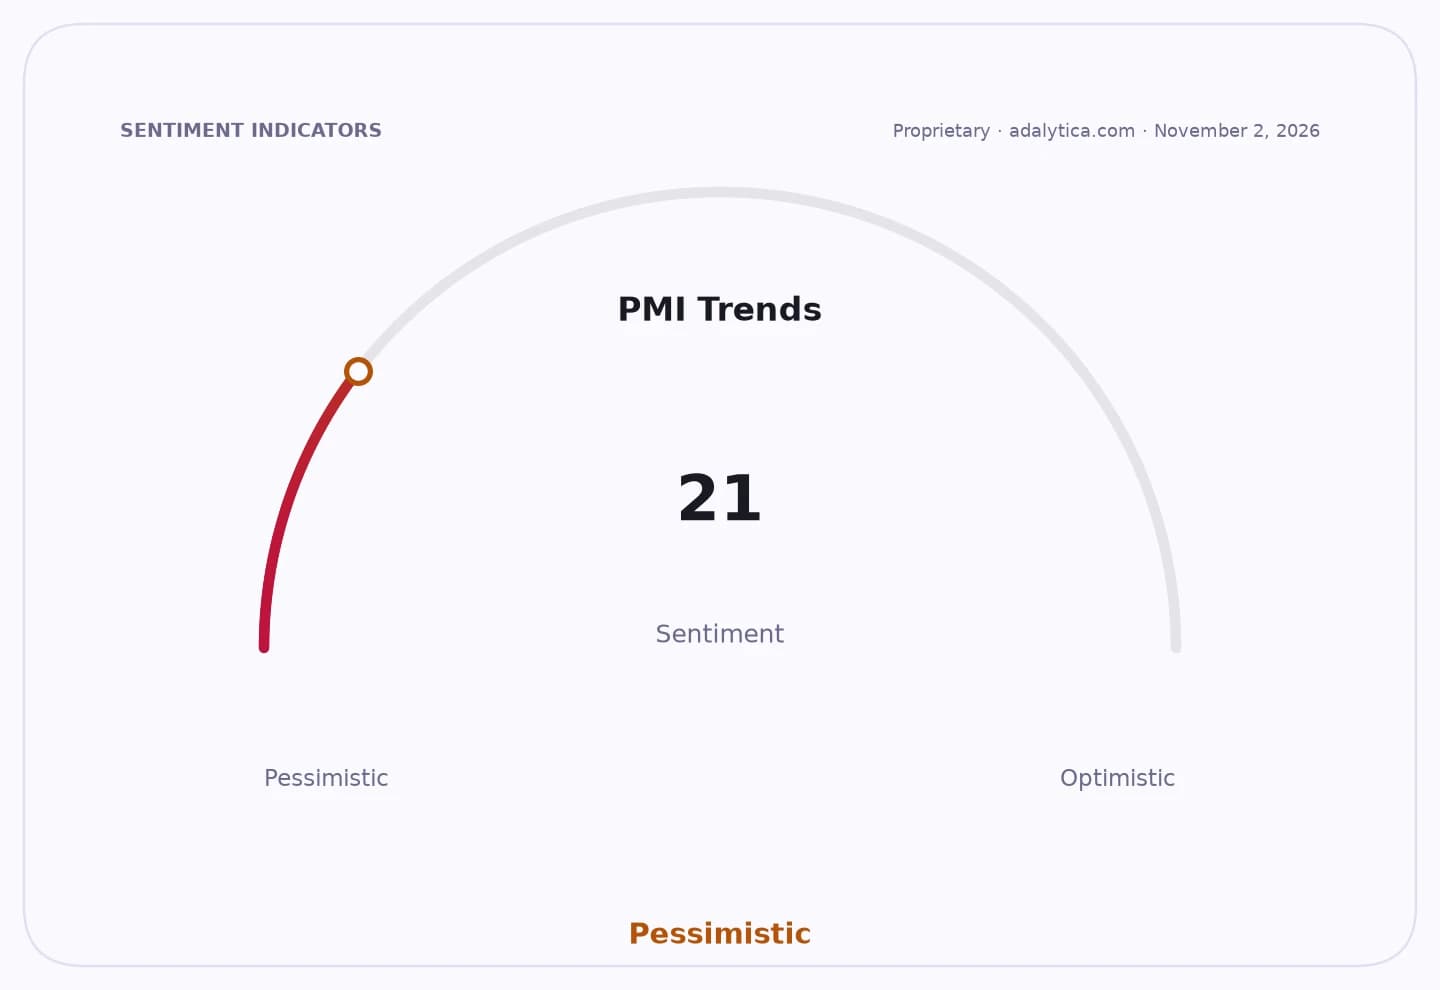
PMI Trends
That still leaves India in expansion territory, but the direction matters. For an economy that has leaned on manufacturing as one of its cleanest growth stories, a softer PMI is a reminder that momentum can cool before it cracks. Investors should care because factory data often shows whether domestic demand, export demand and corporate pricing power are holding up well enough to support earnings.
Sentiment Indicators
The slowdown is not dramatic enough to rewrite the bull case on India, but it does make the market’s next questions more important: Are companies still seeing enough order flow to justify capital spending? Can manufacturers keep hiring and passing on costs? And will the recent run in India-focused exchange-traded funds prove durable if activity keeps easing?
On the market side, India country funds such as INDA, EPI and INDY have already seen volatility tied to growth expectations. INDA has recovered from an October low near $45.56 to around $48.45, while EPI and INDY have also bounced back from their weakest levels. That rebound suggests investors are still willing to pay for India exposure, but they are not ignoring macro risk. Technical readings across the funds have improved from oversold conditions, though they remain below longer-term trend markers in some cases, showing sentiment is stabilizing rather than euphoric.
The broader narrative is straightforward: India remains one of the world’s most attractive long-term growth markets, but even the best compounders move in cycles. A manufacturing PMI of 54.7 says expansion continues, yet the pace of that expansion is no longer accelerating. For investors, that argues for patience rather than excitement. India still deserves a place on the watchlist, but the best approach is to own it as part of a diversified, multiyear portfolio rather than chase every strong print.
| Entity | Gains | Losses |
|---|---|---|
| Indian manufacturers | ▲Still expanding output | ▼Slower order momentum |
| India-focused ETFs | ▲Recovery in long-term case | ▼Near-term growth premium |
| Domestic investors | ▲Ongoing economic expansion | ▼Less upside from surprise acceleration |
| Export-oriented peers | ▲Relative demand remains firm | ▼Global slowdown risk |